
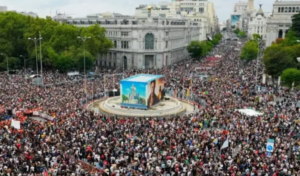
Spanish Prime Minister Pedro Sánchez announced the dissolution of parliament and the holding of early parliamentary elections on November 29, 2026, after a fragmented parliament blocked a number of key government initiatives, including measures to combat the housing crisis.
On October 5, Sánchez announced the convening of an extraordinary cabinet meeting to initiate the procedure for dissolving parliament. The early election will take place nearly a year ahead of schedule.
The decision was made following yet another escalation of the housing crisis in Spain. Last week, parliament rejected the government’s proposed housing measures, and on October 3, tens of thousands of people took to the streets in protests across approximately 50 cities nationwide.
In Madrid alone, according to Reuters, about 70,000 people took part in the demonstrations. Protesters demanded tougher measures against rising rents, evictions, and the shortage of affordable housing. Protests also took place in Valencia and other major cities.
The housing crisis in Spain has worsened in recent years amid rapidly rising prices, insufficient supply of new housing, and high rental costs in major cities and tourist regions.
According to the latest Eurostat data, published on October 1, 2026, residential real estate prices in Spain rose by 12.1% in the second quarter compared to the second quarter of 2025. By comparison, housing prices across the European Union rose by an average of 4.7% during this period, and by 4% in the eurozone. Thus, the rate of price growth in Spain is more than double the European average.
Moreover, prices continue to rise on a quarterly basis: in the second quarter, prices in Spain rose by another 3.4% compared to the first quarter of 2026. In the first quarter, the annual growth rate was 12.8%.
High growth rates are also being seen in the resale market. According to indices published in early October by Spain’s largest real estate portals, the average price of resale housing continued to grow at double-digit rates in the third quarter. According to Idealista, prices rose by 11.8% year-over-year—to 2,930 euros per square meter—while Fotocasa estimates annual growth at 13.8% and the average price at approximately 3,140 euros per square meter.
At the same time, the situation is complicated by lending conditions. The Bank of Spain reported in July that in the second quarter of 2026, banks tightened lending conditions, and public demand for mortgage loans declined. Banks also expected lending conditions to tighten further in the third quarter.
Consequently, the housing issue has evolved from a primarily social and economic problem into one of the central factors on the Spanish political agenda. The rapid rise in real estate prices, the shortage of affordable housing, the situation in the rental market, and mass protests increased pressure on the government at a time when Sánchez’s cabinet was already struggling to pass bills in parliament.
Early parliamentary elections in Spain are scheduled for November 29, 2026.
Starting January 1, 2027, the UK will significantly reduce government support for the Homes for Ukraine program: monthly payments to British households providing housing to Ukrainians will drop from £350 to £100, according to The Guardian.
As a result, the so-called “thank you payment” will be reduced by 71.4%.
The new rules will apply to both current hosts already participating in Homes for Ukraine and new participants in the program.
At the same time, the British government is also cutting funding to local authorities responsible for implementing the program. The payment to municipalities per arriving Ukrainian will decrease from 5,900 to 3,300.
According to The Guardian, since the launch of Homes for Ukraine in March 2022, 181,000 of the approximately 234,000 Ukrainians who arrived in the UK after the start of the full-scale war have received support through the program. The British government has already allocated more than £1.81 billion to implement the program.
The funding cut is raising concerns among Ukrainians and host families about the program’s continued ability to provide free housing. Program participants interviewed by The Guardian said that the reduction in payments could force some hosts to withdraw from the program.
As one option for continued residency, the British government suggests that hosts could transition from their current status to a standard landlord-tenant relationship, under which Ukrainians would pay for their housing themselves.
This could be a particularly sensitive issue for elderly Ukrainians, people with disabilities, and low-income families, who would find it difficult to pay rent on their own in the British housing market.
It is important to note that the £350 is not rent paid to Ukrainians, but a government payment to the host household. Only one such payment may be made per address, regardless of the number of guests staying there.
For Ukrainians who have transitioned from the Homes for Ukraine visa to the Ukraine Permission Extension (UPE) program, payments to the host may be made for no more than 18 months from the date the guest first transitioned to UPE. After this period, the government’s “thank you payment” ceases.
Homes for Ukraine was launched by the British government on March 14, 2022. The program allowed UK residents to provide Ukrainians with housing in their homes or separate properties, while receiving a monthly compensation payment from the government.
Residential real estate prices in Italy rose 4% in the second quarter of 2026 compared to the same period last year, according to preliminary data from the Italian National Institute of Statistics (Istat).
The pace of housing price increases slowed slightly: in the first quarter, the year-over-year increase was 5.1%.
Compared to the first quarter of 2026, the housing price index increased by 1.7%. Newly built homes rose in price by 5% over the year, while existing homes rose by 3.7%. In the previous quarter, these figures were 6.7% and 4.6%, respectively.
On a quarterly basis, prices for new housing rose by 2.7%, and for existing housing by 1.5%.
Among major Italian cities, housing prices rose the fastest in Turin. In the second quarter, prices there were 8.5% higher than a year earlier, whereas in the first quarter, the year-over-year increase was only 3.8%.
In Rome, residential real estate prices rose by 6.4% following a 5.5% increase in the first quarter.
In contrast, in Milan—which in previous years had been one of the country’s most dynamic real estate markets—the pace of growth slowed sharply. Prices rose by 2.4% year-over-year, compared to 7.1% in the first quarter.
The most noticeable slowdown in Milan was recorded in the new-construction segment: after a 20.1% jump in the first quarter, year-over-year growth in the second quarter was only 1.1%.
Regionally, Istat recorded the highest price growth in Central Italy—5.1%. In the northeast, housing prices rose by 4.2%; in the northwest, by 3.9%; and in the south and on the islands, by 2.6%.
The rise in prices is occurring against a backdrop of a de facto stabilization in the number of transactions. According to data from the Italian Tax Agency’s Real Estate Market Observatory, the number of housing transactions in the second quarter increased by only 0.1% year-over-year, following a 4.4% increase in the first quarter.
Based on the results of the first two quarters, the cumulative increase in the housing price index for 2026 stands at approximately 3.8%. Istat plans to release its next market assessment on December 17, 2026.
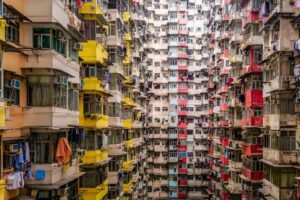
Hong Kong remains the least affordable metropolis for homebuyers among the cities surveyed by UBS: a skilled service sector worker needs about 15 years’ worth of annual income to purchase a 60-square-meter apartment near the city center.
These figures are contained in the UBS Global Real Estate Bubble Index 2026, published on September 22.
More than ten years’ income is also required to purchase a similar apartment in Tokyo, Paris, London, and Seoul.
UBS also notes a high burden on buyers’ incomes in Singapore, Lisbon, Zurich, Geneva, São Paulo, Munich, Sydney, Milan, and New York.
At the other end of the ranking are Miami and Dubai. A 60-square-meter apartment there costs roughly five times the annual income of a skilled worker.
However, a relatively lower ratio of real estate prices to wages does not necessarily mean affordable housing. In the U.S. and Canada, affordability is further limited by high mortgage rates, bank requirements, and other costs of homeownership.
According to UBS’s calculations, compared to 2021, the average skilled worker in the cities surveyed can now afford about one-third less living space on their income.
Separately, UBS compared real estate prices to rent. The highest ratio was recorded in Zurich: the cost of an apartment is equivalent to approximately 46 years of rent. In Geneva, the ratio is about 40 years, while in Munich, Frankfurt, and Hong Kong, it exceeds 30 years.
A high ratio of purchase price to rent may indicate that investors are anticipating further significant price increases. If such expectations wane, the risk of property value losses increases, notes UBS.
Kyiv was not included in this study.
According to Experts.news, Lisbon was included in the UBS Global Real Estate Bubble Index for the first time and was immediately classified as a city at high risk of a housing price “bubble.”
The Portuguese capital’s index stood at 1.04 in 2026, according to a UBS study published on September 22. The bank classifies readings between 1.0 and 1.5 as “elevated risk.”
Over the past decade, real housing prices in Lisbon have risen by an average of nearly 7% annually—the highest rate among all 23 cities included in the study.
Since mid-2025 alone, housing prices, adjusted for inflation, have risen by an additional 10% or so.
UBS attributes the market’s long-term upswing, in particular, to policies aimed at attracting foreign investment and new residents.
However, analysts note that the factors that previously supported growth are gradually weakening. Lisbon has become one of Europe’s least affordable housing markets; rent growth has stalled, and demand is beginning to shift toward more affordable areas outside the city.
UBS cites Portugal’s shift toward a more selective immigration policy as an additional factor.
In terms of risk, Lisbon now ranks just behind Zurich, Tokyo, Miami, Dubai, Seoul, and Geneva. At the same time, it ranks ahead of Amsterdam, Madrid, Frankfurt, Munich, Paris, and London.
The study does not imply that UBS is forecasting a drop in prices in Lisbon. The index points to a buildup of imbalances between real estate prices, household incomes, rental rates, lending volumes, and other fundamental indicators.
Kyiv was not included in this study.
Zurich and Tokyo were the only two of the world’s 23 largest cities that UBS classified in 2026 as having a high risk of a housing real estate bubble.
According to the UBS Global Real Estate Bubble Index 2026, published on September 22, Zurich’s index stood at 1.69 and Tokyo’s at 1.54. UBS considers an index above 1.5 to indicate high risk.
The “elevated risk” category included Miami with an index of 1.41, Dubai at 1.16, Seoul at 1.13, Geneva at 1.12, and Lisbon at 1.04.
Moderate risk was recorded in Amsterdam at 0.95, Madrid at 0.86, Los Angeles at 0.69, Sydney (0.68), Frankfurt (0.64), Toronto (0.63), Vancouver (0.62), Munich and Hong Kong (both 0.61), Singapore (0.54), and Milan (0.50).
UBS classified Paris (0.33), London (0.32), New York (0.28), San Francisco (-0.02), and São Paulo (-0.24) as low-risk markets.
In Zurich, real housing prices have risen by nearly 140% over the past 20 years, while rental rates have increased by approximately 40% and household incomes by 30%. The ratio of purchase price to rental cost has reached 46 years—the highest figure among all cities studied by UBS.
In Tokyo, inflation-adjusted housing prices are now about 50% higher than they were seven years ago. Over the past year, they have risen by another 6% or so.
UBS notes that, on average, real housing prices in all surveyed cities rose by only 0.5% over the past year; however, a significant gap has emerged between individual markets.
The bank emphasizes that a high index reading does not predict an inevitable crash. A correction could occur due to changes in interest rates, investor sentiment, or a significant increase in housing supply.



