
According to Experts Club, on October 30, 2026, the international rating agency Fitch Ratings unexpectedly revised its outlook on France’s long-term sovereign credit rating from “stable” to “negative,” while maintaining the rating itself at A+. This decision is linked to the deterioration of public finances in the eurozone’s second-largest economy, a slowdown in economic growth, and rising debt-service costs, Reuters reported, citing a statement from Fitch.
The rating agency noted that since its previous review in August 2026, France’s credit metrics have deteriorated sharply. Economic growth has been weaker than expected, government bond yields have risen significantly, and the prospects for reducing the budget deficit have become less certain.
Fitch is particularly concerned about the trend in public debt, which, according to the agency’s forecast, will rise from 115.7% of GDP in 2025 to approximately 124% of GDP in 2028.
Thus, over the next three years, France’s debt burden could rise by more than 8 percentage points of GDP, despite the government’s stated plans for fiscal consolidation.
According to Fitch’s assessment, the total fiscal adjustment required to stabilize public debt now stands at about 3.5% of GDP, compared with 3% of GDP in the August forecast.
An additional challenge is the rise in public debt servicing costs. The agency expects interest payments on the debt to increase from 2.5% of GDP in 2025 to 3.3% of GDP in 2028.
This means that an increasingly large share of budgetary resources will be directed toward payments to creditors, which will limit the ability to finance other government expenditures without raising taxes or taking on new debt.
Fitch forecasts that France’s general government deficit will reach 5.5% of GDP in 2027. This significantly exceeds the 3% of GDP benchmark set by European fiscal rules.
Meanwhile, the French government expects to reduce the deficit to 5% of GDP in 2027. Fitch’s higher forecast reflects the agency’s doubts about the feasibility of implementing the planned austerity measures and generating additional budget revenues.
The negative economic trends are also confirmed by the latest official statistics.
According to a preliminary estimate by France’s National Institute of Statistics and Economic Studies (INSEE), published on October 30, the country’s GDP contracted by 0.1% in the third quarter of 2026, following zero growth in the second quarter.
At the same time, exports fell by 1.7% compared to the previous quarter, and fixed capital formation declined by 0.6%.
Inflation added to the pressure; according to INSEE data for October, it accelerated to 3.4% on a year-over-year basis.
The situation in the government bond market also reflects growing investor concern.
The yield on 10-year French bonds exceeded 5.14% at the end of October, reaching its highest level since 2002.
Rising yields mean higher costs for the government to raise new funds and a gradual increase in the cost of refinancing existing debt.
Of particular significance is the widening spread between French and German government bond yields, which are traditionally used as a benchmark for assessing debt risks in the eurozone.
In October, this spread reached 178 basis points, compared with approximately 85 points in early September, indicating a notable increase in the risk premium on French government debt.
Fitch also highlights the political constraints on fiscal policy.
The French government lacks a stable parliamentary majority, and the approaching 2027 presidential election complicates efforts to agree on spending cuts and tax changes.
Mass protests over the cost of living, funding for public services, and socioeconomic reforms are creating additional pressure.
According to the agency’s assessment, political fragmentation and a tense social climate make it difficult to implement a consistent, multi-year policy to reduce the budget deficit.
At the same time, Fitch believes that the 2027 budget could be adopted using the mechanisms provided for in the French Constitution, even without a stable majority in the National Assembly.
However, the mere adoption of the budget does not guarantee that the stated financial targets will be met if economic growth remains weak and debt service costs continue to rise.
French Minister of Economy and Finance Roland Lescure stated in an official announcement on October 30 that the government takes note of Fitch’s decision.
According to him, it confirms the need to adopt a responsible budget by the end of the year, aimed at reducing the public finance deficit to 5% of GDP.
The minister emphasized that the government intends to continue fiscal consolidation and ensure predictable conditions for economic activity.
Fitch’s decision marked yet another warning from the major international rating agencies regarding France’s financial situation.
On October 23, Moody’s maintained the country’s credit rating at Aa3 with a negative outlook. Meanwhile, S&P Global Ratings rates France at A+ with a stable outlook.
Thus, two of the three largest international rating agencies now have a negative outlook on French government debt.
Fitch plans to conduct its next review of France’s rating no later than the end of February 2027.
A negative outlook does not imply an automatic downgrade, but it does indicate an increased risk of such a decision in the future if public finances continue to deteriorate.
At the same time, the agency emphasizes that the current A+ rating is supported by the size and diversification of the French economy, high household income levels, the resilience of government institutions, membership in the eurozone, and a relatively stable banking sector.
For the European economy, the deterioration in France’s fiscal outlook is significant primarily due to the size of its public debt and the role of the French financial market in the eurozone.
A further rise in the cost of government borrowing could increase debt-service costs, limit the scope for fiscal stimulus, and intensify pressure on public finances.
In addition, persistently high yields on government bonds could affect lending conditions for French companies and households, as the cost of sovereign borrowing serves as one of the benchmarks for the financial market.
Fitch Ratings is one of the three largest international credit rating agencies, alongside S&P Global Ratings and Moody’s. The agency assesses the creditworthiness of governments, corporations, and financial institutions. An A+ rating falls within the investment-grade category and indicates the borrower’s relatively high ability to meet its financial obligations.
Previously, a video analysis of countries’ external debt was prepared by the Experts Club think tank — https://youtube.com/shorts/fUTLp6l_fTY?si=A2hpjEt0CCViKKnh
Members of Parliament began the first reading of Bill No. 16000 on the State Budget of Ukraine for the coming year.
“We have received 5,236 amendments from you to the draft state budget for 2027. This is a record for the past 24 years, but that has not prevented us from carefully reviewing all of your proposals. According to preliminary estimates, incorporating the submitted amendments would require an additional 13.5 trillion hryvnias in total. That is nearly two budgets for next year,” said Roksolana Pidlasa (Servant of the People faction), chair of the Budget Committee, at a plenary session of the Verkhovna Rada on Tuesday.
According to her, many proposals for the draft budget do not meet procedural requirements because they are unbalanced or the proposed funding sources are not supported by calculations and are not realistic.
Pidlasa also reported that the working group and the Budget Committee proposed incorporating 90 budget proposals across all areas of life—from defense to social policy.
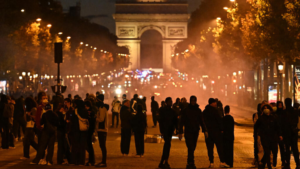
On October 17, 2026, large-scale nationwide protests took place in France against the rising cost of living, increasing fuel prices, and cuts in funding for public services. According to the country’s Ministry of the Interior, approximately 550,000 people took part in the demonstrations, while organizers estimate the number of participants at 800,000, Reuters and the French newspaper Le Monde report.
A total of 110 demonstrations took place across the country. In Paris alone, according to Interior Minister Laurent Nuñez, approximately 110,000 people took to the streets. The protests also spread to Marseille, Lyon, Lille, Bordeaux, Toulouse, and other major cities.
The participants’ main demands included higher wages and pensions, measures to curb food and energy prices, increased funding for education and healthcare, and the preservation of social guarantees.
Trade unions, student organizations, representatives of farmers’ associations, transport sector workers, and activists from the “yellow vests” movement, which emerged in France in 2018 due to rising fuel prices, joined the demonstrations.
The current wave of protests began in September with student demonstrations against teacher shortages, the poor condition of educational institutions, and insufficient government funding for education. Subsequently, the demands expanded to include issues of purchasing power, social inequality, and the government’s economic policy.
Despite the predominantly peaceful nature of the demonstrations, clashes with police, vehicle arson, vandalism and looting of shops, and attacks on administrative buildings occurred in several cities.
In Paris, the most tense situation was observed near Place de la République, where some groups of rioters threw stones and pyrotechnic devices at police officers. Law enforcement officers used tear gas and water cannons. There were also reports of shops being looted and bank branches being damaged.
In Marseille, a group of protesters entered the city council building; in Lyon, a tourist office was set on fire; and in Limoges, a fire damaged the town hall building. Incidents involving damage to administrative buildings were also recorded in other cities.
According to preliminary data from the French Ministry of the Interior, police detained approximately 400 people. Authorities reported injuries among law enforcement officers and civilians. A separate investigation was launched following the serious injury of a minor participating in a protest in Saint-Étienne.
French President Emmanuel Macron condemned the violence and stated the need to hold those responsible accountable. Prime Minister Sébastien Lecornu emphasized that the government would not allow the unrest to be used to exert pressure on state institutions.
At the same time, protest organizers emphasize that the overwhelming majority of participants demonstrated peacefully and demanded a revision of the state’s socioeconomic policy.
The mass demonstrations are taking place against the backdrop of a difficult situation in France’s public finances. According to the draft state budget for 2027 presented on October 1, the government plans to reduce the deficit from a projected 5.4% of GDP in 2026 to 5% of GDP in 2027.
To achieve this goal, overall fiscal consolidation measures totaling €54 billion are envisaged, including €43 billion within the framework of the draft laws on the state budget and the financing of the social security system.
At the same time, the government forecasts a slowdown in France’s economic growth to 0.5% in 2026, with a possible acceleration to 1% in 2027. Public debt servicing costs could rise from €79.2 billion in 2026 to €91.2 billion the following year.
Trade unions fear that measures to limit public spending will increase the burden on households, primarily those with low and middle incomes.
The protests have already caused disruptions to urban public transport, the temporary closure of certain Paris Metro stations, and damage to commercial properties. A final assessment of the economic damage caused by the unrest has not yet been released.
The new wave of social discontent is increasing political tensions in France ahead of the 2027 presidential election and complicating discussions on fiscal policy. Further developments will depend, among other things, on negotiations between the government, trade unions, and representatives of the student movement.
France is the second-largest economy in the eurozone after Germany and one of Ukraine’s largest trade and economic partners in the European Union.
According to Fixygen, Greece plans to introduce a 10% tax on capital gains from cryptocurrency transactions, Reuters reports.
The corresponding bill was submitted for public comment on October 8. The bill is expected to be submitted to parliament for consideration in November.
Earlier, in June, the possibility of setting the tax rate at 15% was discussed. The new version of the bill provides for a tax exemption on income from cryptocurrency transactions amounting to less than 500 euros per year.
Currently, Greece lacks a comprehensive legal framework for taxing cryptocurrency transactions. At the same time, there is no unified system for taxing income from crypto assets within the European Union.
According to Reuters, capital gains tax rates on cryptocurrency transactions in European countries range from approximately 8% to 30%.
Greek authorities have previously noted that they cannot accurately assess the size of the domestic cryptocurrency market, as a significant portion of investors use foreign platforms.
Consequently, the government does not yet have precise estimates of potential additional budget revenues following the introduction of the new tax.
In September 2026, the State Customs Service of Ukraine transferred 75.2 billion hryvnia in customs duties to the state budget, which is 18.1 billion hryvnia more than in the same month last year.
According to Open4Business, citing data from the State Customs Service, revenues increased by 31.7% compared to September 2025, when 57.1 billion hryvnias were transferred to the budget.
The agency noted that actual revenue in September exceeded the indicative target set by the Ministry of Finance by 4.6 billion hryvnia.
One of the main factors driving the growth in revenue was the increase in the volume of taxable imports. In September 2026, this volume amounted to $7.3 billion, which is 23.7% more than a year earlier.
In particular, revenue from customs clearance of natural gas rose significantly—by 2.8 billion hryvnias—as did revenue from passenger cars (2.2 billion hryvnias), petroleum products (1.8 billion hryvnias), and coal (1.3 billion hryvnias).
Additional revenue was also generated by imports of telephones—by 0.9 billion UAH, power generators—by 0.7 billion UAH, and trucks—by 0.6 billion UAH.
At the same time, customs duty exemptions granted during customs clearance of goods in September totaled 25.3 billion UAH, which is 5.9 billion UAH, or 30.4%, more than in September of last year.
The largest amounts of exemptions were for defense-related goods—13.1 billion UAH, goods imported under free trade agreements—5.7 billion UAH, and energy equipment—2.4 billion UAH.
Thus, despite the increase in the volume of exemptions granted, the growth in imports and payments for certain major commodity groups allowed the State Customs Service to significantly increase revenues to the state budget.
The State Customs Service administers customs payments when goods cross Ukraine’s customs border. Customs revenues—primarily import VAT, excise taxes, and duties—are one of the largest sources of revenue for the state budget.
Despite delays in receiving external financing, the Ministry of Finance of Ukraine will currently refrain from significantly increasing the volume of borrowing on the domestic debt market in order to avoid raising the cost of servicing that debt, said First Deputy Minister of Finance Roman Yermolychev.
“We will monitor the status of the Single Treasury Account. We must understand that these are debt obligations that we must fulfill in any case,” the First Deputy Minister noted during a budget discussion organized by the Center for Economic Strategy last week.
“Raising more funds would require raising interest rates, which we would prefer to avoid,” Yermolichev emphasized.
He recalled that at the most recent primary auctions of domestic government bonds, the Ministry of Finance managed to increase the amount of funds raised by 5 billion hryvnia compared to the standard trend.
“Future fundraising rounds may also be larger, depending on how much funding we’ll need for social payments and those critical expenditures that arise on a daily basis,” said the first deputy minister.
According to him, while awaiting external financing—which is contingent on the Verkhovna Rada’s adoption of a number of laws—the Ministry of Finance has deferred approximately 39 billion hryvnias in unsecured capital expenditures to December.
As reported by the Interfax-Ukraine news agency, during the first primary auctions for the placement of domestic government bonds following the National Bank’s increase of the discount rate from 15.5% to 16% per annum on September 22, the Ministry of Finance was able not only to maintain yields on standard bonds at the previous level, but also to lower rates on benchmark bonds, which banks can use to partially form their required reserves. The cut-off rates for 12-month and 29-month OVDPs remained at 15.18% and 16.10%, respectively, while the rate for benchmark bonds fell to 12.18%.
In total, the Ministry of Finance raised 7.36 billion UAH across three auctions, compared to 2.01 billion UAH a week earlier, when there were two auctions and the offering at each was 1 billion UAH.
For the upcoming auctions on Tuesday, September 29, the Ministry of Finance reduced the supply of standard OVDPs to 1 billion UAH from 3 billion UAH last Tuesday, while retaining the more popular one-year bonds. At the same time, it will again offer 5 billion UAH in benchmark bonds, whereas previously these instruments were auctioned off approximately once a month.



