
According to the Serbian business media outlet Parametar, Serbia has put up for sale, through the Belgrade Stock Exchange, a 6.35% stake in Termovent SC Livnica čelika, based in Bačka Topola.
The company specializes in the production of steel castings, including those made of carbon, stainless, heat-resistant, and wear-resistant steel. The foundry has been in operation since the 1960s and has been part of Termovent SC since 2003.
The company supplies its products to both domestic and international markets. The Termovent Group also manufactures industrial valves and is a certified supplier to the Paks Nuclear Power Plant in Hungary.
According to data for 2025, the foundry’s revenue exceeded 1 billion dinars, net profit amounted to approximately 7.8 million dinars, and the number of employees was 168.
The sale of the state’s stake effectively continues the consolidation of ownership in this already privatized industrial asset.
According to preliminary data, Ukrainian steelmakers reduced their production of total rolled steel by 23% in January–September of this year compared to the same period last year, down to 3.729 million metric tons.
According to information released Friday by the “Ukrmetallurgprom” association, 137,000 metric tons of rolled steel were produced in September, 269,500 metric tons in August, 382,700 metric tons in July, 599,800 metric tons in June, in May—537,800 metric tons, in April—460,800 metric tons, in March—544,500 metric tons, in February—390,300 metric tons, and in January—406,400 metric tons.
In 2025, Ukraine’s steel companies increased their production of general-purpose rolled steel by 4.8% compared to 2024, reaching 6.521 million metric tons.
In 2024, Ukraine increased its production of general-purpose rolled steel by 15.8% compared to 2023—to 6.222 million metric tons from 5.372 million metric tons. In 2023, total rolled steel production rose by 0.4% to 5.372 million metric tons, while in 2022 it fell by 72% to 5.350 million metric tons.
In 2021, before the war, 19.079 million metric tons of rolled steel were produced, or 103.5% of the 2020 level.
METALLURGY, PRODUCTION, ROLLED STEEL, UKRAINE, UKRMETALLURGPROM
Ukrainian steelmakers reduced steel production by 19.8% in January–September of this year compared to the same period last year, down to 4.431 million metric tons.
According to information released Friday by the “Ukrmetallurgprom” association, 131,000 metric tons of steel were produced in September, 277,000 metric tons in August, 457,000 metric tons in July, 690,800 metric tons in June, in May—629,400 metric tons, in April—517,300 metric tons, in March—702,300 metric tons, in February—515,000 metric tons, and in January—511,100 metric tons.
In 2025, Ukraine’s steel mills reduced steel production by 2.2% compared to 2024, to 7.409 million metric tons.
In 2024, Ukraine increased steel production by 21.6% compared to 2023, to 7.575 million metric tons. In 2023, steel production fell by 0.6% to 6.228 million metric tons, and in 2022, it fell by 70.7% to 6.263 million metric tons.
In 2021, before the war, 21.366 million metric tons of steel were produced, or 103.6% of the 2020 level.
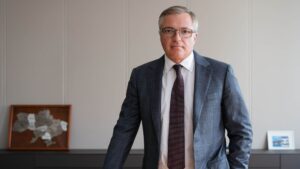
The mining and steel company Metinvest continues to hope for support from its global partners amid the war, but recently, the European Union and the European Commission have taken numerous measures that cast doubt on whether it is worth investing in the Ukrainian steel industry at all.
The company’s CEO, Yuriy Ryzhenkov, expressed this view in an interview with the Financial Times.
As an example, he cited the quotas imposed on Ukrainian steel in the EU, even though Ukraine’s agreements with the EU—in particular the Association Agreement and other agreements signed in recent years—effectively provided for free access to the European market. Despite the fact that Ukraine has exported significantly less steel to the EU over the past few years than before, the corresponding Ukrainian quotas have been reduced by more than 50%.
“In my view, this is a very strange move. If you want to support the country, it’s better to allow its industry to operate and pay taxes. These funds will strengthen the country’s defense capabilities and economy. This is more effective than grants or preferential loans. I hope our officials, together with their European colleagues, will be able to review this situation and rectify it,” said Ryzhenkov.
According to him, a much better approach would be to consider how the Ukrainian economy—particularly the metallurgical sector—can become part of the broader European market and the European economy, thereby making it stronger rather than weaker. “I also believe that it is very important right now for people in Brussels to understand the conditions under which we are working. We are forced to operate amid constant disruptions in logistics and staff shortages. Many people have left the country. More than 8,500 of our employees have been drafted into the army. We have an unstable energy supply and very high energy costs,” the CEO noted.
He emphasized that it is, to some extent, unfair and incorrect to treat the Ukrainian steel industry on par with that of other countries supplying products to the EU. The situation in Ukraine requires a special approach, greater understanding, and, perhaps, certain tools that will allow us to survive now and return to investment and growth in the future.
When asked whether the company had assessed the total amount of losses, the CEO noted that a comprehensive assessment has not yet been conducted. “As I’ve already said, we are currently clearing debris and assessing damage to infrastructure and production facilities. And this is not the first time since the Russian invasion that our facilities have come under attack, so we will be able to provide a more accurate assessment once the war is over. Only then will it be possible to discuss the cost of recovery from the damage.”
Ryzhenkov noted that all of the company’s international projects are linked to Ukrainian production and Ukrainian resources, and there is hope that this will continue to be the case. “Currently, our rolling mills in Europe and the United Kingdom are operating autonomously. At the same time, we already have plans in place and are taking steps to restore vertical integration with Ukrainian enterprises and return to our previous model. In short, we remain very active. We consider Europe, as well as the Mediterranean and Black Sea regions, to be our main markets. We want to continue to be present in these markets and remain open to new opportunities,” Ryzhenkov concluded.
Metinvest is a vertically integrated group consisting of mining and metallurgical enterprises. Its enterprises are located in Ukraine—in the Donetsk, Luhansk, Zaporizhzhia, and Dnipropetrovsk regions—as well as in European countries. The holding’s main shareholders are the SCM Group (71.24%) and Smart Holding (23.76%). Metinvest Holding LLC is the management company of the Metinvest Group.
Source: https://metinvestholding.com
In the first quarter following the EU’s introduction of quotas on metal product shipments, Ukrainian metal exporters used 100% of their quarterly guaranteed quota for duty-free shipments to the EU of cold-rolled flat products made of unalloyed and alloyed steel, hollow sections, and other seamless pipes, according to a statement on the website of the “Ukrmetallurgprom” association.
According to the statement, as of September 30, 2026, the quotas in the following categories under the global (final) quotas in which Ukraine participates have been exhausted: metal-coated sheets (MFN subgroup—“Most-Favored-Nation treatment”), metal-coated sheets (FTA subgroup—“countries with a free trade agreement with the EU”), unalloyed and other alloyed steel bars and light sections (MFN subgroup—“most-favored-nation treatment”), stainless steel bars, billets, and small-section products (MFN subgroup – “most-favored-nation treatment”) and stainless steel bars, billets, and small-section products (FTA subgroup – “countries with a free trade agreement with the EU”).
Among competing countries, the guaranteed quota as of September 30 has been exhausted for the following categories: rebar – Turkey; wire rod of non-alloy and alloy steel – Turkey; hollow sections – Turkey and Macedonia; seamless stainless steel pipes—India; cold-rolled bars and rods of unalloyed and alloyed steel—Switzerland; and unalloyed wire—Turkey.
As of September 29, 2026, the competitive quota has been exhausted for the following categories: hot-rolled flat products of unalloyed and alloyed steel, rebar, wire rod of unalloyed and alloyed steel, hollow sections, seamless stainless steel pipes, other seamless pipes, and non-alloy wire.
As previously reported, once the guaranteed and competitive quotas are exhausted, further shipments to the EU are subject to a 50% tariff. “Ukrmetallurgprom” criticized the EU’s decision to restrict shipments of Ukrainian steel products, which had been supplied to Europe duty-free for the first three years following Russia’s full-scale aggression. The association believes that Ukraine currently poses no threat to European producers, as the war initially caused the country’s steel production to plummet from 40 million metric tons to 7.5 million metric tons, and currently, nearly all steel plants are shut down due to shelling.
EU, EXPORTS, METALLURGY, QUOTA, UKRAINE
The European Business Association (EBA) calls for maintaining a zero quota on ferrous scrap exports, which would effectively ban scrap metal exports in 2027, Alternatively, should the quota be abolished, member companies propose imposing an export duty of EUR 180 per metric ton for all export destinations, taking into account Ukraine’s international obligations.
“Domestic processing of scrap metal in Ukraine allows for the creation of added value, the preservation of jobs and tax revenues, and the provision of raw materials for the production of steel and finished metal products. The use of scrap also helps reduce energy consumption and CO₂ emissions in steel production, which takes on additional significance in light of the EU’s Carbon Border Adjustment Mechanism (CBAM),” the publication states.
According to the publication, EBA member companies have appealed to the Cabinet of Ministers and the Ministry of Economy.
Recently, following the shutdown of most Ukrainian steel mills due to massive Russian shelling, scrap metal collection companies have called on the government to review restrictions on scrap exports. Previously, scrap collectors had advocated for lifting the de facto ban on scrap exports from Ukraine and introducing quotas for shipments of this raw material to EU countries in the amount of 200,000 metric tons per year.
As reported, the Cabinet of Ministers of Ukraine established a zero quota on scrap metal exports effective January 1, 2026, to ensure Ukrainian enterprises have access to this raw material.
The EBA noted that, according to 2025 figures, exports of ferrous scrap from Ukraine increased by 53% compared to 2024—reaching 448,680 metric tons. The business community believes that easing the current restrictions could lead to a rise in exports and a shortage of raw materials for Ukrainian manufacturers.
According to data from “UAVtormet,” 4.3 million metric tons of steel were produced in the first 8 months of 2026 (compared to 7.41 million metric tons in 2025), 925,400 metric tons of scrap were delivered to steel mills (1.56 million metric tons), and scrap procurement totaled 971,700 metric tons (2.11 million metric tons). According to preliminary forecasts, 6.4–6.5 million metric tons of steel will be produced in 2026, 1.2–1.25 million metric tons of scrap will be delivered to steel mills, and scrap procurement will total 1.22–1.25 million metric tons.
In January–August of this year, Ukrainian companies reduced exports of ferrous scrap by more than 20 times compared to the same period last year—to 13,86 thousand metric tons from 283,06 thousand metric tons, and in monetary terms—to $3.930 million from $85.4 million. At the same time, 9.31 thousand metric tons were exported in January due to the completion of last year’s contracts, compared to 68.52 thousand metric tons in December 2025. There were no exports in February through May of this year; 4.08 thousand metric tons were exported in June, 315 metric tons in July, and 157 metric tons in August.
On April 29, 2026, the Cabinet of Ministers, by its Resolution No. 563, amended Annex 1 to its Resolution No. 1795 of December 31, 2025, permitting the export of scrap metal on the basis of licenses issued by the Ministry of Economy to to foreign economic activity entities that were the winners of electronic auctions held in December 2025 for the sale of such goods in accordance with the Procedure for the Alienation and Lease of Property of Business Entities in which more than 50% of the shares in the authorized capital are owned by the state or by another legal entity whose sole participant is the state.



