
According to Experts.news, DLS became the largest company in Ukraine’s tobacco sector by revenue in the first half of 2026, generating 61.08 billion UAH, according to data from OpenDataBot.
The company is part of the DL Solution financial and industrial group.
Philip Morris Sales and Distribution took second place with revenue of 32.15 billion UAH, while JT International Company Ukraine came in third with 23.6 billion UAH. The company represents brands such as Winston, Camel, Sobranie, LD, Monte Carlo, and Winchester on the Ukrainian market.
In fourth place is British American Tobacco Sales and Marketing Ukraine, with revenue of 19.94 billion UAH. The company works with brands such as Kent, Dunhill, glo, Vuse, and Velo.
Rounding out the top five is the distributor Global Tobacco, which generated 11.69 billion UAH in revenue.
The top ten also includes DK “Mirana” — 10.65 billion UAH, Imperial Brands Ukraine—10 billion UAH, JT International Ukraine—4.96 billion UAH, Philip Morris Ukraine—4.41 billion UAH, and Halychyna-Tabak—4.26 billion UAH.
The combined revenue of the ten largest companies reached approximately 182.7 billion UAH, accounting for about 92% of the total revenue of the companies included in OpenDataBot’s comparative sample.
At the same time, the five largest companies alone accounted for about 148.5 billion UAH, or approximately three-quarters of the combined revenue of the analyzed companies.
In total, 41 tobacco companies that filed financial reports for both the first half of 2025 and for 2026 generated 198.18 billion UAH in revenue, which is 10% more than in the previous year.
Source: OpenDataBot.
The combined revenue of Ukrainian tobacco companies that reported for the first half of both 2025 and 2026 increased by 10% and reached UAH 198.18 billion, according to Opendatabot.
The analysis included 41 companies that presented comparable financial statements for both periods. In absolute terms, their combined revenue increased by UAH 18.16 billion. Revenues grew at 26 companies, while they declined at 14 market participants.
At the same time, the increase in turnover did not lead to higher net profit. The companies’ combined net financial result decreased by approximately 8% compared with the first half of 2025, to UAH 6.5 billion.
At the same time, the structure of the industry in terms of profitability improved. In the first half of 2026, 29 out of 41 companies, or about 71% of the companies in the sample, made a profit. A year earlier, the share of profitable enterprises stood at 63%.
The number of loss-making companies declined from 14 to 11 over the year.
In total, 50 tobacco industry companies submitted financial statements for the first half of 2026, which is 13 fewer than in the same period last year. The comparison was conducted only among enterprises that submitted reports for both periods.
As of September 2026, 1,101 active companies operating in the tobacco sector were registered in Ukraine.
Agricultural holding company IMC reported $34.28 million in net profit for the first half of 2026, down 33% from the first half of 2025, according to the company’s report filed with the Warsaw Stock Exchange on Thursday.
“The decline in normalized EBITDA and net profit … was driven by lower corn and sunflower prices compared to the same period last year—in contrast to the sharp price increases in the first half of 2025—as well as rising logistics costs and the depreciation of the hryvnia,” the document states.
According to the report, EBITDA fell by 22% to $50.23 million.
The company’s consolidated revenue in the first half of 2026 rose by 6% to $88.88 million. Corn sales accounted for the largest share—98.1% compared to 97.8% in the first half of last year.
It is noted that the company’s cost of goods sold rose from $66.4 million in January–June 2025 to $79.9 million in January–June 2026.
IMK added that over the six-month period, the Ukrainian hryvnia depreciated by 5.5% against the U.S. dollar, whereas in the first half of last year it depreciated by only 1.0%; consequently, the company recognized a net loss from foreign exchange differences of $2.11 million.
Net cash flow from operating activities decreased to $12.0 million from $15.0 million in January–June 2025, primarily due to lower prices for agricultural products and higher operating expenses.
According to the report, IMC’s net cash outflow from investing activities decreased to $8.2 million in the first half of 2026 from $10.5 million in the first half of 2025, in line with the group’s capital expenditure program.
IMK Agroholding is an integrated group of companies operating in the Sumy, Poltava, and Chernihiv regions (northern and central Ukraine) in the crop production, grain elevators, and warehousing segments. Its land bank totals 115,000 hectares, storage capacity stands at 554,000 metric tons, and grain and oilseed production in 2025 reached 838,000 metric tons.
IMK’s net profit in 2025 rose by 24% to $67.5 million, while consolidated revenue fell by 10% to $190.5 million.
Ukraine’s foreign exchange earnings from ferrous metal exports in July 2026 totaled $199.9 million, which is nearly 32% less than in June, when exports brought in $293.6 million, according to data from the State Customs Service.
Thus, July was noticeably weaker than the previous month for Ukrainian steel exports.
Overall, from January through July, companies in the sector earned $1.678 billion from ferrous metal exports, which is 7.6% less than during the same period last year.
At the same time, imports of ferrous metals in July totaled $176.4 million. The difference between exports and imports thus narrowed to approximately $23.5 million for the month.
Over the seven-month period, metal imports rose by 7.2% to $1.023 billion.
The decline in July’s export revenue comes after two years of recovery in metallurgical exports. In 2024, their value rose by 16.9%, and in 2025, by another 7.85%.
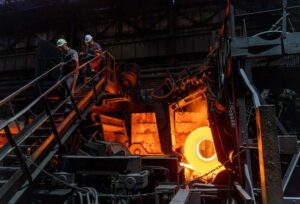
Ukrainian steelmakers reduced foreign exchange earnings from ferrous metal exports by 7.6% in January–July 2026 compared to the same period last year, down to $1.678 billion, according to data from the State Customs Service.
In January–July 2025, ferrous metal exports brought Ukraine $1.816 billion.
The share of ferrous metals in the country’s total merchandise exports also declined—to 6.95% from 7.79% a year earlier, or by 0.84 percentage points.
At the same time, imports of ferrous metals into Ukraine continued to grow. Over the seven-month period, they increased by 7.2%—to $1.023 billion.
Thus, in 2026, the Ukrainian metallurgical industry faced both a decline in export revenue and increased competition from imported products.
By comparison: at the end of 2025, Ukraine, on the contrary, increased its export revenue from ferrous metals by 7.85%—to $3.339 billion—following a 16.9% increase in 2024.
Source: State Customs Service of Ukraine, data for January–July 2026.
Revenues to Ukraine’s state budget from assets under ARMA’s management in January–July 2026 amounted to only 210 million UAH, compared to 1.3 billion UAH for the same period in 2025, said Pavlo Velykorechanyn, an expert with the Verkhovna Rada’s Anti-Corruption Committee and former deputy head of ARMA, in an exclusive interview with the “Interfax-Ukraine” news agency.
Thus, revenue has fallen by more than six times.
For comparison, according to Velykorechanyn, 7.5 billion hryvnias were transferred to the state budget in 2023, in part due to major cases involving special confiscation.
He noted that the current 210 million hryvnias is largely the result of managing assets transferred to ARMA back in 2024–2025. A significant portion of the revenue is linked to payments from Naftogaz.
According to Velykorechanyn’s assessment, there are currently virtually no new economically attractive assets in the agency’s portfolio. Furthermore, regarding certain properties, the results of tenders to select managers are being annulled, after which courts rule such decisions unlawful, forcing the state to fund property appraisals again.
He identified the length of the procedure for transferring assets to management as a separate problem. While the property remains without a manager, the state is forced to bear the costs of its security and maintenance, while the asset may physically deteriorate or lose value.



