
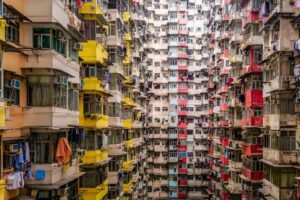
Hong Kong remains the least affordable metropolis for homebuyers among the cities surveyed by UBS: a skilled service sector worker needs about 15 years’ worth of annual income to purchase a 60-square-meter apartment near the city center.
These figures are contained in the UBS Global Real Estate Bubble Index 2026, published on September 22.
More than ten years’ income is also required to purchase a similar apartment in Tokyo, Paris, London, and Seoul.
UBS also notes a high burden on buyers’ incomes in Singapore, Lisbon, Zurich, Geneva, São Paulo, Munich, Sydney, Milan, and New York.
At the other end of the ranking are Miami and Dubai. A 60-square-meter apartment there costs roughly five times the annual income of a skilled worker.
However, a relatively lower ratio of real estate prices to wages does not necessarily mean affordable housing. In the U.S. and Canada, affordability is further limited by high mortgage rates, bank requirements, and other costs of homeownership.
According to UBS’s calculations, compared to 2021, the average skilled worker in the cities surveyed can now afford about one-third less living space on their income.
Separately, UBS compared real estate prices to rent. The highest ratio was recorded in Zurich: the cost of an apartment is equivalent to approximately 46 years of rent. In Geneva, the ratio is about 40 years, while in Munich, Frankfurt, and Hong Kong, it exceeds 30 years.
A high ratio of purchase price to rent may indicate that investors are anticipating further significant price increases. If such expectations wane, the risk of property value losses increases, notes UBS.
Kyiv was not included in this study.
Toronto and Vancouver saw the most significant declines in housing prices among the 23 largest global markets analyzed by UBS in 2026.
Over the past four quarters, real housing prices in both Canadian cities have fallen by approximately 10%, according to the UBS Global Real Estate Bubble Index 2026.
The correction was particularly severe in Toronto. From 2014 to 2022, real prices there doubled due to rapid population growth, investment demand, and cheap financing.
After 2022, the situation changed. Due to rising interest rates, restrictions on foreign buyers, and an increase in supply, real prices are now nearly 30% below their peak, according to UBS.
In Vancouver, real prices have fallen by nearly 10% since mid-2025 and are about 20% below their 2022 peak. Home sales have dropped to their lowest level in about 25 years, while the number of properties on the market remains significantly above the long-term average.
As a result, UBS now classifies both cities as only moderate risk: Toronto’s index stands at 0.63, and Vancouver’s at 0.62. Just a few years ago, the Canadian markets were considered among the most overheated in the world.
A correction is also underway in Germany, though less sharply. Real prices in Frankfurt and Munich have fallen by nearly 4% over the past year. In Frankfurt, housing prices—adjusted for inflation—are already about 25% below their 2021 peak.
At the same time, UBS notes that a structural housing shortage persists in both Germany and many other major cities, which limits the potential for further price declines.
Kyiv was not included in this study.
Zurich and Tokyo were the only two of the world’s 23 largest cities that UBS classified in 2026 as having a high risk of a housing real estate bubble.
According to the UBS Global Real Estate Bubble Index 2026, published on September 22, Zurich’s index stood at 1.69 and Tokyo’s at 1.54. UBS considers an index above 1.5 to indicate high risk.
The “elevated risk” category included Miami with an index of 1.41, Dubai at 1.16, Seoul at 1.13, Geneva at 1.12, and Lisbon at 1.04.
Moderate risk was recorded in Amsterdam at 0.95, Madrid at 0.86, Los Angeles at 0.69, Sydney (0.68), Frankfurt (0.64), Toronto (0.63), Vancouver (0.62), Munich and Hong Kong (both 0.61), Singapore (0.54), and Milan (0.50).
UBS classified Paris (0.33), London (0.32), New York (0.28), San Francisco (-0.02), and São Paulo (-0.24) as low-risk markets.
In Zurich, real housing prices have risen by nearly 140% over the past 20 years, while rental rates have increased by approximately 40% and household incomes by 30%. The ratio of purchase price to rental cost has reached 46 years—the highest figure among all cities studied by UBS.
In Tokyo, inflation-adjusted housing prices are now about 50% higher than they were seven years ago. Over the past year, they have risen by another 6% or so.
UBS notes that, on average, real housing prices in all surveyed cities rose by only 0.5% over the past year; however, a significant gap has emerged between individual markets.
The bank emphasizes that a high index reading does not predict an inevitable crash. A correction could occur due to changes in interest rates, investor sentiment, or a significant increase in housing supply.
UBS analysts expect copper prices to rise next year due to reduced supply amid ongoing mine disruptions.
In addition, the rise will be supported by high long-term demand associated with the transition to clean energy and increased investment in this area, the bank said in a statement.
UBS raised its copper price forecast for the end of the first quarter of 2026 by $750 to $11,500 per ton. Expectations for June and September were raised by $1,000 to $12,000 and $12,500 per ton, respectively. Experts also set a target level for December next year at $13,000 per ton.
Analysts now believe that the copper deficit in the global market this year will be about 230,000 tons, compared to the previously expected 53,000 tons, and in 2026 – 407,000 tons, compared to 87,000 tons. In their opinion, declining inventories and ongoing supply risks will keep the market tight.
Disruptions at mines this year, including production problems at Freeport-McMoRan’s Grasberg mine in Indonesia, slower recovery of production in Chile, and recurring protests in Peru, highlight structural supply constraints that are likely to persist until 2026, the bank said in a statement.
Freeport-McMoRan said it plans to resume production at the Grasberg copper and gold mine by July after operations were suspended two months ago due to a fatal accident.
UBS lowered its forecast for refined copper production growth to 1.2% in 2025 and 2.2% next year, citing deteriorating ore quality and operational problems. Analysts expect global demand for the metal to increase by 2.8% both this year and next due to the development of renewable energy sources, electric vehicles, investments in power grids, and data centers.
The bank’s experts believe that any price decline will be short-lived and recommend maintaining long positions in copper.
Earlier, the Experts Club information and analytical center released a video dedicated to global copper production and leading producing countries – https://youtube.com/shorts/_h8iU50z8C0?si=a-XkgGEfeUxseQNa
The global equity market is approaching the formation of a bubble, according to UBS global equity strategist Andrew Garthwaite.
Garthwaite, whose opinion is cited by MarketWatch, compares the current conditions to the dot-com boom of the late 1990s and the Japanese market bubble of the 1980s. According to him, the stock market already meets six of the seven criteria for a bubble.
First, the structural bull market, which UBS defines as a period when the dynamics of stocks over ten years outpaces the dynamics of bonds by at least 5% per year, has ended.
Secondly, corporate profits are under pressure, and their growth is slowing, especially in cyclical sectors.
Thirdly, the breadth of the market has been lost. Its dynamics are determined by the stock prices of a small number of tech giants, while smaller companies lag behind.
Fourth, 25 years have passed since the last bubble.
Fifth, investors believe that “this time it’s different,” expecting a significant increase in productivity due to generative artificial intelligence (AI).
Sixth, retail investors are actively involved in the auction, buying speculative assets ranging from “meme” stocks to cryptocurrencies.
At the same time, the seventh criterion – loose monetary policy (LMP) – has not yet been met.
We should be worried if the yield on ten-year US Treasury bonds exceeds 5%, according to Mr. Hartwright. Currently, it is about 4.65%, but UBS predicts that it will decline to 4.25% by the end of the year.
The expert also prefers “defensive” stocks of issuers with low debt burdens, such as SAP, Microsoft Corp. and BAE Systems, to securities of non-financial companies in cyclical industries.
In the UK, he sees opportunities for investors in interest rate-sensitive sectors, such as real estate and utilities, which are trading at a significant discount.



