
According to Fixygen, U.S. banks have opened a new front in their battle with the crypto industry—the Independent Community Bankers of America (ICBA) has filed a lawsuit against the U.S. Office of the Comptroller of the Currency (OCC), challenging the decision to grant crypto companies simplified national banking licenses.
The lawsuit was filed on October 2 in the U.S. District Court for the District of Columbia, the ICBA reported. The association represents American community banks—that is, small and medium-sized banks—a significant portion of whose business involves lending to individuals and companies in local markets.
The subject of the dispute is the so-called national trust bank charters. These charters allow companies to operate at the federal level with digital assets, provide custody services, and participate in payment transactions, but do not authorize traditional banking activities such as accepting deposits and issuing loans.
The ICBA believes that the OCC has effectively created a simplified path for crypto companies to enter the regulated banking system.
“Congress did not create the national trust license as a back door into the banking system for crypto companies,” said ICBA President and CEO Rebecca Romero Reyni.
Banks point to a fundamental difference in regulation.
Traditional deposit-taking banks must meet capital and liquidity requirements, be subject to consolidated supervision, and participate in the FDIC deposit insurance system. Companies with a national trust charter that do not take deposits are exempt from a significant portion of these requirements.
At the same time, the ICBA believes that a federal license may give customers the impression that a crypto company’s assets have the same government guarantees as funds held at a traditional bank.
The association is demanding that the final rule adopted by the OCC on March 2, 2026, and the related Interpretive Letter No. 1176 be declared unlawful.
Separately, the ICBA is demanding that the conditional approval of a national trust banking license for Protego Holdings be revoked. The company specializes in the custody, trading, lending, and issuance of digital assets.
The dispute extends far beyond a single license.
If the OCC maintains its current approach, crypto companies will be able to obtain federal banking status without converting into traditional commercial banks. This could simplify institutional custody of cryptocurrencies, settlements using digital assets, and the integration of crypto infrastructure into the U.S. financial system.
At the same time, traditional banks are stepping up pressure on the stablecoin market. The ICBA opposes paying interest and rewards to stablecoin holders, fearing a flight of funds from bank accounts into digital dollars. According to the association, a reduction in the deposit base could diminish small banks’ resources for lending to businesses and the agricultural sector.
According to Experts.news, the largest banks are beginning to move traditional bank money onto the blockchain, creating a potential competitor to the USDT and USDC stablecoins. In the UK, Barclays, HSBC UK, Lloyds Banking Group, Monzo, Nationwide, NatWest, and Santander are already testing tokenized deposits, while in the U.S., Citi is simultaneously building infrastructure that allows corporate clients to work with stablecoins via Coinbase.
In effect, two models for the future of digital money are taking shape. The first involves the use of independent stablecoins issued by companies such as Tether and Circle. The second transfers existing funds from bank accounts onto the blockchain.
British banks took an important step in this direction on September 24, 2026. The industry association UK Finance announced the completion of the first real-world customer transactions involving tokenized deposits in pounds sterling as part of the Great British Tokenized Deposit (GBTD) project.
Participants in the project include Barclays, HSBC UK, Lloyds Banking Group, Monzo, Nationwide, NatWest, and Santander.
The banks conducted two live mortgage refinancing transactions. The tokenized funds were automatically blocked until the terms of the agreement were met, after which the payment was processed without any additional manual steps.
Another test involved a purchase on a consumer marketplace. It demonstrated the ability to transfer tokenized bank funds between customers of different banks via a shared infrastructure.
The main difference between this model and USDT or USDC lies in the legal nature of the money.
A tokenized deposit is not a separate cryptocurrency. It is a digital representation of regular money that the customer already holds in a bank account.
If there is 1,000 GBP in a bank account, the bank can theoretically represent this amount in the digital infrastructure as a corresponding amount of tokenized pounds. In this case, the bank continues to bear the obligation to the customer, and the funds themselves retain the legal status of a bank deposit.
A stablecoin works differently.
USDT is issued by Tether, and USDC by Circle. The user effectively exchanges regular money for a digital token, the value of which the issuer commits to maintaining at the level of the corresponding fiat currency through reserve assets.
Therefore, a tokenized bank deposit and a stablecoin may look the same on the blockchain, but economically they are different instruments.
Banks have a significant advantage—their existing system of trust, regulation, and customer relationships.
UK Finance explicitly states that tokenized deposits must retain the regulatory guarantees of traditional bank deposits while acquiring the properties of digital money—programmability, faster settlements, and the ability to automatically execute payments once specified conditions are met.
It is precisely this programmability that could become one of the technology’s main advantages.
For example, when purchasing real estate, funds can be automatically transferred to the seller only after the transaction has been registered. Payment to a supplier can be made after confirmation of delivery. In financial transactions, the transfer of a security and payment for it can occur almost simultaneously.
As a result, the number of intermediate transactions is reduced, as is the risk that one party will fulfill its obligations while the other does not.
The next phase of the British project will involve using tokenized deposits to settle payments for digital assets. GBTD participants plan to link customers’ tokenized funds to digital securities.
In this way, banks are attempting to create within the regulated financial system the opportunities that blockchain and stablecoins initially offered outside of it.
However, it is still too early to write off USDT and USDC.
The scale of the existing stablecoin market is incomparable to the banks’ experiments. According to CoinGecko data as of October 3, the market capitalization of USDT alone is approximately $184 billion, while that of USDC is approximately $74 billion.
The total stablecoin market already exceeds $300 billion.
Stablecoins are particularly strong in international money transfers. They operate around the clock, can move between different blockchains and platforms, and do not require the sender and recipient to be served by the same bank.
This is where a fundamental problem arises for the traditional banking system.
If a significant portion of international payments shifts to USDT, USDC, or other stablecoins, banks will have to compete for payment flows that previously passed almost entirely through the banking infrastructure.
Furthermore, a massive shift of funds from bank deposits to stablecoins could potentially reduce banks’ deposit base, which is used to lend to the economy.
The Bank of England is explicitly taking this risk into account as it develops new regulations for digital currencies.
In June 2026, the Bank of England published draft rules for systemic stablecoins. The regulator proposed a model under which at least 40% of a systemic stablecoin’s reserves must be held directly at the Bank of England, while up to 60% may be invested in short-term UK government bonds.
Restrictions on the amount of stablecoins that individual users and companies can hold are also being considered for a transitional period.
However, the Bank of England does not propose banning stablecoins. On the contrary, its strategy envisions the coexistence of several types of digital currencies.
In the future, traditional bank deposits, their tokenized versions, regulated stablecoins, and a potential central bank digital pound could all be used simultaneously.
Therefore, real competition is developing not so much between banks and cryptocurrencies as between different models of digital money.
Citi’s strategy is illustrative in this regard.
On September 28, Citi and Coinbase announced an expansion of their partnership, which effectively combines traditional banking infrastructure with stablecoins.
Coinbase has selected Citi’s Virtual Account Wallet to power Coinbase Virtual Accounts. Incoming traditional currency can be automatically converted into stablecoins.
Conversely, Citi’s corporate clients will be able to accept payments in stablecoins via the Spring by Citi payment platform and the Coinbase Payments infrastructure.
Coinbase accepts the digital payment and facilitates its conversion, after which Citi processes the settlement in traditional currency as a bank.
This is particularly important for corporate clients: the company gains the ability to accept stablecoins without having to build its own infrastructure for storing and managing crypto assets.
According to Citi, this solution potentially gives its corporate clients access to over 150 million stablecoin holders worldwide.
Thus, major banks are adopting different strategies.
British banks such as Barclays, HSBC, Lloyds, NatWest, and others are creating tokenized versions of their own deposit funds.
Citi, meanwhile, is developing a banking blockchain infrastructure and building a bridge between traditional money and existing stablecoins.
In the long run, these models may not displace one another but rather share the market.
Tokenized deposits have a natural advantage within the banking system—for payroll, corporate payments, mortgages, lending, and securities transactions.
Stablecoins are stronger in areas where round-the-clock cross-border transfers, interoperability between different platforms, and the ability to freely move digital money between blockchains are particularly important.
But for banks, this issue is becoming strategic. If they fail to migrate deposits and payments to a programmable digital infrastructure, a significant portion of the new market could go to Tether, Circle, Coinbase, and other companies in the crypto industry.
That is why competition between USDT, USDC, and tokenized bank deposits could become one of the key drivers of the global financial system’s development in the coming years.
Sources: UK Finance, Bank of England, Citi, Coinbase, CoinGecko.
Pensioners who have switched their pension payments to mono will receive 1,000 UAH, after taxes, by the end of the year, according to Monobank co-founder Oleg Gorokhovsky.
“And as soon as they receive their first pension on a mono card, we’ll credit 1,000 UAH to their cashback account. We’ll cover the tax as well. In addition, we’re adding a ‘Medical’ category with 5% cashback for the year,” he noted.
Gorokhovsky emphasized that, according to the law, pensions can be received on a card from the bank of the pensioner’s choice.
As of July 1, 2026, there are 9.98 million pensioners in Ukraine, according to data from the Pension Fund. Eighty-three percent of pensioners—approximately 8.3 million people—receive their payments through banking institutions. The remaining 17% continue to receive their payments through Ukrposhta branches and mail carriers.
U.S. Federal Reserve has presented two draft rules that establish a new regulatory framework for the issuance of payment stablecoins by U.S. banks and other organizations under the Fed’s supervision.
The drafts were published on September 24, 2026, as part of the implementation of the previously enacted GENIUS Act. The Fed has opened them for public comment.
The first draft requires that issued payment stablecoins be fully backed by eligible reserve assets.
Such reserves may include, in particular, short-term U.S. Treasury bonds and other high-quality liquid assets.
The Fed also proposes establishing standardized capital requirements for issuers, which must cover the credit and operational risks associated with the issuance of digital money.
Separate requirements are proposed for companies that provide custody services for stablecoin reserve assets. The regulator also intends to clarify which stablecoin transactions banks under its supervision are permitted to conduct.
The second draft regulates the procedure for banks to obtain authorization to issue payment stablecoins.
A bank intending to launch its own stablecoin will be required to submit a business plan, financial information, and other documents to the regulator. The draft also outlines the procedure for reviewing applications, handling appeals, and making final decisions.
Federal Reserve Board member Michael Barr stated that the regulatory framework must ensure that a stablecoin can be reliably redeemed at face value even under conditions of financial market stress or if the issuer itself faces difficulties.
According to him, restrictions on the structure of reserves and uniform capital requirements are important elements of the new system; however, the final rules will require further refinement following public comment.
The comment period for the drafts will end 60 days after their publication in the Federal Register.
The rules are being developed amid the rapid growth of stablecoins’ role in international payments. According to a recent Chainalysis study, the volume of cross-border transfers in stablecoins in the 12 months ending in June 2026 increased by 77.5%—from $124.2 billion to $220.3 billion.
At the same time, the average transaction size was approximately $3,000, which, according to Chainalysis, indicates that stablecoins are being actively used for money transfers, payments to suppliers, and the movement of personal savings—not just for institutional trading.
The introduction of full-fledged federal regulation could be one of the key steps in integrating stablecoins into the traditional U.S. financial infrastructure.
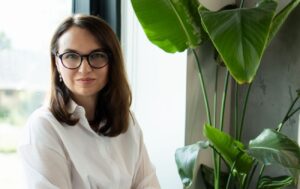
Iryna Starominska, Chairwoman of the Board of JSC “UNIVERSAL BANK,” was named the winner of the “Financier of the Year” category as part of the 30th anniversary nationwide “Person of the Year 2025” program.
Starominska has over 25 years of professional experience, the last 16 of which she has spent in leadership roles in the banking sector. She has headed Universal Bank since 2017.
One of the bank’s key projects during this period was the 2017 launch, in collaboration with the Fintech Band team, of the digital banking service monobank, which operates under Universal Bank’s banking license.
As of early June 2026, the monobank ecosystem had over 10.7 million customers, making it one of Ukraine’s largest digital financial services. The project has also been included twice in CNBC’s “Top 250 Fintech Companies in the World” ranking.
The development of monobank has become one of the most notable examples of the transformation of the Ukrainian banking market, where traditional banking infrastructure has been combined with remote services and mobile financial technologies.
Universal Bank is listed among Ukraine’s systemically important banks. According to information provided by the organizers of the “Person of the Year” program, as of the end of 2025, the bank ranked third in Ukraine in terms of retail deposits and second in terms of its retail loan portfolio, and was also among the top five most profitable Ukrainian banks.
For five years, Starominska has also been ranked among the most influential women in Ukraine’s fintech sector. In her management role, she focuses on the development of digital banking services, the automation of operations, and the implementation of technological solutions for retail customers.
Charitable and social projects remain a separate area of activity for Universal Bank and monobank. According to data provided by the award organizers, from the start of the full-scale invasion through April 2026, the total amount of charitable aid provided by the bank and its team exceeded 497 million UAH.
Of this amount, approximately 386 million UAH was allocated to support the Armed Forces of Ukraine, military units, and charitable foundations that assist the army. Another approximately 111 million UAH was allocated to cultural and social projects. The bank also participates in charitable initiatives alongside the UNITED24 fundraising platform and other foundations.
Universal Bank operates in the Ukrainian banking market as a universal financial institution serving both individuals and businesses. Since 2017, the bank has been a partner of Fintech Band in the development of monobank. The bank is part of the TAS Group and is included in the list of systemically important banks in Ukraine.
Open4Business is an information partner of the nationwide “Person of the Year 2025” program.
BANK, FINANCE, FINTECH, MONOBANK, UKRAINE, UNIVERSAL BANK, Старомінська
According to Fixygen, the line between traditional banks and the crypto industry is rapidly blurring. In March 2026, Kraken Financial received a Federal Reserve master account, becoming the first digital bank with direct access to the U.S. payment infrastructure.
Kraken already operates as a special-purpose bank in Wyoming and, at the same time, holds over 100 active regulatory licenses in more than 30 countries.
On the other hand, traditional banks are exploring the possibility of issuing their own stablecoins and tokenized deposits. JPMorgan is studying the possibility of issuing a stablecoin, and similar projects are being discussed by Bank of America, Wells Fargo, and other banks.
Even crypto companies are beginning to obtain federal banking licenses: in August, the U.S. OCC granted World Liberty Financial preliminary approval to establish a national trust bank to handle stablecoins and store assets.
As a result, in a few years, the distinction between a “bank” and a “crypto exchange” may no longer be defined by the range of services offered.
Both sides aim to provide services such as asset custody, payments, stablecoins, trading, tokenized securities, credit products, and international settlements.
The main battle will center on who can keep customers within their own financial infrastructure—JPMorgan, Coinbase, Kraken, or the new digital banks.



