
Hungary plans to meet the country’s natural gas needs without supplies from Russia by October 2027, said István Kapitány, the country’s Minister of Economy and Energy.
“If everything goes as we expect, Hungary’s gas supply will be secured from other, non-Russian sources by the deadline set by the European Union in October of next year,” the minister said in an interview with Telex published on September 18.
According to Kapitány, Hungary’s high dependence on Russian gas did not arise from a lack of technical capacity to purchase fuel from other countries. Hungary is connected by gas pipelines to several neighboring countries, and the Russian supply system was used for a long time primarily because it was considered the most cost-effective option. The minister did not specify by how much the share of Russian gas has already decreased in recent months.
The deadline is directly linked to new EU regulations. EU Regulation 2026/261 provides for the cessation of imports of Russian pipeline gas under long-term contracts after September 30, 2027. In exceptional cases, if a country is unable to ensure the required level of storage filling, the deadline may be extended to November 1, 2027.
For Hungary, the transition is particularly significant, as the state-owned MVM maintains a long-term contract with Gazprom Export for approximately 4.5 billion cubic meters of gas per year. The contract originally runs through 2036; however, MVM’s own documents note that the European ban will effectively prevent the use of Russian long-term supplies after the fall of 2027. The company is already expanding its portfolio of alternative gas sources.
LNG is becoming one of the key areas of focus. MVM ONEnergy has signed a five-year contract with the U.S.-based Chevron for approximately 2 billion cubic meters of liquefied natural gas. Deliveries under this contract are scheduled to begin on October 1, 2027, immediately after EU restrictions on Russian pipeline gas take effect.
In addition, MVM has reached an agreement with Azerbaijan’s SOCAR for the supply of 800 million cubic meters of gas over a two-year period starting in 2026.
Romania is emerging as another potential source. The development of the Neptun Deep field in Romania’s sector of the Black Sea is expected to begin production in 2027. Once it reaches full capacity, it is projected to supply approximately 8 billion cubic meters of gas per year, which will create additional opportunities for deliveries to Central Europe, including Hungary.
Thus, Captain’s statement signals a significant shift in Hungarian energy policy: Budapest, which in previous years had opposed an accelerated phase-out of Russian fuel, is now preparing its gas supply balance to meet EU requirements by the fall of 2027. At the same time, the minister emphasized that the country has sufficient gas supplies for the current heating season and that the authorities do not anticipate any problems with the physical availability of fuel.
Global demand for coal will rise this year and reach a new all-time high amid a surge in natural gas prices and a summer heat wave that has increased electricity consumption from air conditioners, according to forecasts by the International Energy Agency (IEA).
According to the agency’s estimates, global coal demand will rise by 1.2% in 2026 to 8.94 billion metric tons.
“Coal is virtually not shipped through the Strait of Hormuz, as the Middle East is neither a major producer nor a significant consumer of coal, but the closure of the strait still affected the coal market due to rising natural gas prices,” the IEA said in a statement. “This has stimulated an increase in electricity generation at coal-fired power plants in countries where there is a choice between gas and coal.”
If shipping through the Strait of Hormuz resumes and liquefied natural gas (LNG) supplies return to the levels seen before the start of hostilities in the Middle East, global demand for coal will decline next year. Otherwise, 2027 will once again set a record for coal consumption, IEA analysts noted.
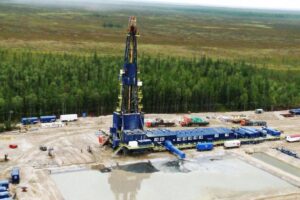
JSC ‘Ukrnafta’ transferred 656.2 million UAH to the state budget based on the 2025 performance of PJSC “Ukrnaftoburinnya,” the company reported.
The funds were received under an asset management agreement signed between “Ukrnafta” and the Agency for the Search and Management of Assets (ARMA).
“In total, since 2023, thanks to the company’s work, over 2.5 billion hryvnias have been transferred to the state budget (…) I thank the team for their responsibility and daily work, and ARMA for its effective cooperation,” said Bohdan Kukura, chairman of the board of Ukrnafta.
For its part, ARMA states that the management of “Ukrnaftoburinnya” is one of the prime examples of the agency’s effective collaboration with the operator.
“Ukrnafta is duly fulfilling the terms of the agreement, and the result of this work is tangible—over 2.5 billion hryvnia directed to the state budget starting in 2023,” noted Yaroslava Maksymenko, acting chair of ARMA.
In July 2023, the Cabinet of Ministers of Ukraine transferred the corporate rights of PJSC “VK “Ukrnaftoburinnya” to the management of PJSC “Ukrnafta.” In December 2023, a court suspended gas production at the Sakhalin field, located in the Bohodukhiv District of Kharkiv Oblast; however, the company resumed operations in August 2024.
“Ukrnaftoburinnya” is one of the largest private gas production companies in Ukraine. Since 2010, it has been developing the Sakhalin oil, gas, and condensate field, which has reserves of 15 billion cubic meters of gas.
Transgaz, the Romanian gas transmission system operator, has signed a memorandum of understanding with the U.S. company Argent LNG, which provides for the possibility of investing in the construction of a large LNG terminal in Louisiana.
The project will have a capacity of 25 million metric tons of LNG per year, or approximately 35 billion cubic meters of gas. The first deliveries are expected in 2030.
One of the main goals is to establish a long-term supply route for American gas through Romania to Moldova and Ukraine, and further on to Hungary, Austria, the Czech Republic, Slovakia, and Germany.
The project is intended to strengthen the so-called Vertical Gas Corridor, which is gradually becoming one of the key routes for supplying non-Russian gas to Central and Eastern Europe.
The corridor connects the gas transmission systems of Greece, Bulgaria, Romania, Hungary, Slovakia, Ukraine, and Moldova. It can be used to transport both Azerbaijani gas and LNG from the U.S., which arrives via the Revithoussa and Alexandroupolis terminals in Greece.
For the Balkans, the project is significant because it provides the region with another major source of gas and fosters additional competition among supply routes. The more American and other non-Russian LNG that flows through Greece and Romania, the more the gas infrastructure of all of Southeast Europe will change.
Moldova has already tested this route: U.S. LNG was delivered via Greece and then injected into Ukrainian underground storage facilities.
Transgaz also controls 75% of the Moldovan gas transmission system operator Westmoldtransgaz.
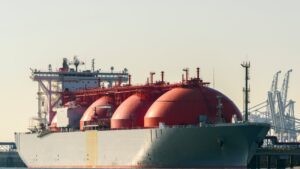
Due to reduced availability of liquefied natural gas (LNG) on the European market, Belgium switched entirely to importing this fuel from Russia in July, a move driven by supply disruptions and high gas prices, according to Bloomberg.
Total LNG shipments to Belgium in July fell by more than 40% compared to the same period last year. At the same time, the country purchased about 0.4 million metric tons of this fuel from Russia, although the volume of Russian imports was lower than in early 2026.
One reason for the increased role of Russian LNG was disruptions in fuel supplies from the Middle East due to shipping problems in the Strait of Hormuz. At the same time, most European buyers were postponing LNG purchases for winter stockpiles due to high gas prices.
“Europe received 16% more Russian LNG in the first half of 2026 compared to the same period the previous year, paying a total of 5.96 billion euros ($6.9 billion). The largest buyers were France, Belgium, and Spain,” the publication reports, citing data from the German nongovernmental organization Urgewald.
Low gas storage levels ahead of the winter season posed an additional challenge for Europe—they are the lowest for this period since records began in 2009.
According to Bloomberg, the last time Russia was the sole supplier of LNG to Belgium was in early 2021—before Russia’s full-scale invasion of Ukraine and after European economies had begun to recover from the COVID-19 pandemic.
According to Interfax-Ukraine, the relative level of gas reserves in European storage facilities has reached its lowest value on this date in recorded history.
Previously, the all-time low for storage levels at this time of year was recorded in 2021 (the pandemic impacted the industry’s capacity). However, since the start of the injection season, the 2026 trend has steadily been closing the gap with the previous record low.
The average level of gas reserves in Europe’s underground storage facilities reached 57.11% at the end of the gas day on August 1, according to data from Gas Infrastructure Europe (GIE), the association of European gas infrastructure operators. The reserve level on the same date in 2021 was slightly higher—57.28%. A day earlier, the figures were different: as of July 31, 2026, the level stood at 56.88% (higher), while as of July 31, 2021, it was 56.83% (lower).
Natural gas storage levels in Europe are a key indicator for the global gas market. The total capacity of the EU’s storage system is 109 billion cubic meters of active gas. Collectively, Europe has become the largest importer in the global LNG market. Gas Infrastructure Europe brings together operators active in the transportation and storage of natural gas, as well as LNG. The statistical database covers the operation of underground natural gas storage infrastructure since 2011, and the receipt and regasification of LNG since 2012. Gas days in the European gas industry are counted starting at 6:00 a.m. Central European Time (CET).
Renewable sources are expected to contribute to the EU’s energy balance. Since the beginning of August 2026, wind power in Europe has been meeting an average of 10% of electricity demand, according to the WindEurope association. A year ago, in August 2025, the contribution of wind power plants stood at 14%.
Europe is also actively importing liquefied natural gas (LNG). However, in August 2026, gas imports from abroad are down 7% compared to last year’s level. LNG imports in August 2026 may drop to 6.9 million metric tons.
The spot price for “next-day” delivery at the benchmark European TTF hub closed at $696 per 1,000 cubic meters on Friday, up from an average of $626 in July.



