
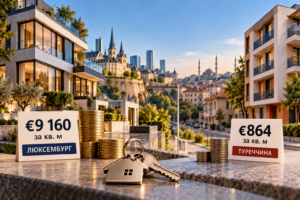
The most expensive newly built homes among the European markets surveyed are located in Luxembourg, the Czech Republic and Germany, while the cheapest are in Turkey, Serbia and Albania. At the same time, in a number of cities in Central and Southeastern Europe, purchasing housing requires more than 15 average annual salaries, according to the findings of the Deloitte Property Index 2026 study.
As the international consulting company Deloitte reported on October 13, 2026, its 15th annual study covered 25 countries and 71 cities. The indicators are based on data for 2025 and include prices of newly built residential properties, apartment purchase affordability, rental rates, residential construction and mortgage lending.
According to Deloitte, the average price per square meter of new housing in Luxembourg reached €9,160, compared with €5,412 in the Czech Republic, €5,200 in Germany, €5,199 in Austria and €5,186 in the Netherlands.
By contrast, the average price of new housing in Turkey was €864 per sq. m, compared with €1,706 in Serbia, €1,720 in Albania, €1,917 in Romania and €1,931 in Greece.
Thus, the difference between the most expensive and cheapest national markets among the countries surveyed exceeded tenfold.
Ranking of countries with the highest average prices for new housing in 2025:
Luxembourg — €9,160 per sq. m.
Czech Republic — €5,412.
Germany — €5,200.
Austria — €5,199.
Netherlands — €5,186.
Five countries with the lowest prices:
Turkey — €864 per sq. m.
Serbia — €1,706.
Albania — €1,720.
Romania — €1,917.
Greece — €1,931.
At the same time, a low absolute price per square meter does not always mean high housing affordability for the local population, since the determining factor is the ratio between property prices and household incomes.
The least affordable among the cities surveyed was the Albanian city of Vlorë, where purchasing a standard new apartment measuring 70 sq. m requires 21.3 average gross annual salaries. In Prague, this figure was 16.9 annual salaries, in Athens — 16, and in Slovakia’s Košice and the Czech city of Brno — 15 each.
Cities with low housing affordability also included Bratislava, where purchasing a standard apartment requires 13.7 annual salaries, and Banská Bystrica, with a figure of 13.4.
At the opposite end was the Italian city of Turin, where purchasing a new 70 sq. m home requires 4.7 average annual salaries. In Norway’s Bergen and Denmark’s Odense, the figure was 4.9 salaries each.
Overall, the number of European cities surveyed where purchasing a standard apartment requires more than ten annual salaries increased from 11 to 19.
Separately, Deloitte analyzed the largest urban markets in terms of the absolute cost of new housing. Munich was the most expensive, with an average price of €11,200 per sq. m. It was followed by Luxembourg City at €10,567, Amsterdam at €8,650 and Barcelona at €8,037.
The cheapest new homes among the major cities surveyed were offered in Turkey: the average price was €870 per sq. m in Ankara, €1,155 in Izmir and €1,339 in Istanbul.
In 2025, increases in average new housing prices were recorded in 19 of the 22 countries for which Deloitte had comparable nationwide data. The highest rates of price growth were observed in Romania (+14.4%), Croatia (+14.3%), Slovakia (+12.5%) and Hungary (+10.9%).
By contrast, according to the study, average prices in euros decreased by 9% in Turkey and 2.5% in Serbia. At the same time, individual urban markets showed the opposite trend. In particular, new housing prices rose by 20% in Belgrade and by approximately 24% in the Albanian city of Durrës.
Luxembourg became the most expensive rental housing market, with an average monthly rate of €45.4 per sq. m. In Paris, rent amounted to €31.2 per sq. m, in Barcelona — €30.9, Dublin — €30.8 and Oslo — €28.9.
Significant differences in the cost of mortgage lending also persist across European countries. Deloitte recorded the highest average rates in Hungary at 9.08%, Poland at 6.91%, Romania at 5.86% and Norway at 5.44%. The lowest figures were in Bulgaria and Finland at 2.77% each, Turkey at 2.84%, Croatia at 2.90% and Spain at 2.94%.
The average mortgage rate in the countries surveyed fell by 0.38 percentage points to 4.09%.
Turkey led in the number of completed residential units, with nearly 674,000 housing units put into operation in 2025. The corresponding figure was 379,000 in France, 209,000 in Poland and 207,000 in Germany.
Ukraine is not represented in the Deloitte Property Index 2026 ranking, so its average price per square meter cannot be directly compared with the figures for other countries within the framework of this study.
At the same time, according to the State Statistics Service of Ukraine, the housing price index in the primary market increased by 13% in 2025, while in the secondary market it rose by 13.4%. These indicators reflect changes in prices in Ukrainian hryvnias rather than the average price per square meter in euros, and therefore are not part of the Deloitte ranking.
Additionally, in May 2026, the State Statistics Service updated its methodology for calculating housing price indices in accordance with European statistical standards.
Deloitte analysts note that the main problem facing the European market remains the mismatch between rising housing prices and household incomes. The situation is aggravated by the limited supply of new homes, high construction costs, lengthy permit procedures and the cost of mortgage financing.
The Deloitte Property Index is an annual international study of residential real estate markets that the company has conducted for 15 years. It is used to compare housing prices and affordability, residential construction, rental markets and mortgage lending across European countries.
Sources: Deloitte Property Index 2026 — official study, Deloitte, press release dated October 12, 2026, State Statistics Service of Ukraine — housing price statistics.
Kyiv ranked first among 33 European capitals for the lowest electricity costs for households in September 2026, reports the Experts Club information and analytical center. The cost of one kilowatt-hour, including taxes, in the Ukrainian capital was 8.4 euro cents, according to data from the international Household Energy Price Index (HEPI) study, published by Euronews Business on October 14.
Budapest ranked second at 10.3 euro cents per kWh, while Podgorica came third, where electricity cost 11.3 euro cents. The five cheapest capitals also included Belgrade (11.6 euro cents) and Valletta (12.3 euro cents).
The average cost of electricity in the capitals of European Union countries was 27.2 euro cents per kWh. Thus, electricity in Kyiv was approximately 69.1% cheaper than the EU average, in Budapest 62.1% cheaper, in Podgorica 58.5% cheaper, and in Belgrade 57.4% cheaper.
The most expensive electricity for households was recorded in Brussels, where the price reached 41.3 euro cents per kWh. It was followed by Berlin (39.6), Dublin (38.7), Bern (38.6) and London (38.3).
Among other European capitals, high tariffs were recorded in Rome (36.6 euro cents), Vienna (34.4) and Prague (34.3). In Madrid, electricity cost 28.3 euro cents per kWh, and in Paris, 28.1 euro cents.
The difference between the most expensive and the cheapest capitals was almost fivefold: 41.3 euro cents in Brussels compared with 8.4 euro cents in Kyiv.
According to HEPI, from the beginning of February to the beginning of September 2026, the average cost of electricity for households in EU capitals increased by 4.2%. Meanwhile, natural gas prices rose by 12% over the same period.
The differences between European capitals are explained by the structure of their energy mix, dependence on imported energy resources, tariff policies, taxes and government mechanisms for supporting households.
At the same time, researchers emphasize that comparing nominal tariffs does not fully reflect the affordability of electricity for the population. When purchasing power is taken into account, the ranking changes significantly, as household incomes and overall price levels differ considerably across European countries.
The Household Energy Price Index study has been conducted monthly since 2009 with the participation of the Austrian energy regulator Energie-Control, the Hungarian regulator MEKH and the international consulting company VaasaETT. It covers 33 European capitals and takes into account supplier tariffs, network charges, taxes and government subsidies.
According to calculations by the Experts Club analytical center based on data from Opendatabot, the combined revenue of the ten largest companies in the first half of 2026 amounted to approximately UAH 1.83 billion. A year earlier, their total revenue stood at approximately UAH 1.28 billion. Thus, the revenue of the top 10 increased by approximately 43%.
| Rank | Company | Revenue 2026, UAH million | Year-on-year change |
|---|---|---|---|
| 1 | Asters | 476.8 | +18.7% |
| 2 | Aequo | 234.9 | +132.5% |
| 3 | Avellum Partners | 192.4 | +113.9% |
| 4 | Sayenko Kharenko | 176.4 | +18.6% |
| 5 | CMS Cameron McKenna LLC | 172.5 | +56.6% |
| 6 | Sayenko Kharenko Ukraine | 134.4 | +105.9% |
| 7 | Ader Haber | 125.6 | +32.9% |
| 8 | Vasil Kisil & Partners | 112.5 | +15.3% |
| 9 | Kinstellar Ukraine | 101.6 | -1.3% |
| 10 | Integrites | 100.1 | +56.1% |
At the same time, nine of the ten largest law firms increased their revenue. The only exception was Kinstellar Ukraine, whose revenue declined by 1.3%, from UAH 102.9 million to UAH 101.6 million.
Aequo demonstrated the highest growth rate among the top 10 participants, at +132.5%. Avellum Partners increased its revenue by 113.9%, while Sayenko Kharenko Ukraine recorded growth of 105.9%.
Two other companies increased their revenue by more than half: CMS Cameron McKenna LLC by 56.6% and Integrites by 56.1%.
According to Experts Club, these trends indicate a recovery in demand for professional legal services and the strengthening of the positions of the largest market players. Revenue growth may be associated with increased activity in corporate transactions, business restructuring, international projects, sanctions and compliance support, litigation, and companies’ preparations for Ukraine’s future reconstruction.
At the same time, the market structure remains fairly concentrated. Asters alone accounted for approximately one-quarter of the combined revenue of the ten largest law firms.
Overall, as of early October 2026, Ukraine had 21,388 registered companies and 23,363 individual entrepreneurs operating under KVED 69.10, “Legal activities.” The total number of legal businesses and entrepreneurs in this segment reached 44,751.
Source: Opendatabot
The combined revenue of the ten largest companies that changed their region of legal address in 2026 totaled approximately 44.1 billion UAH over two quarters, according to Experts Club’s calculations based on data from OpenDataBot.
The largest among them was Parallel-M Ltd., which imports and sells fuel and operates the Parallel gas station chain. Its revenue for the first two quarters of 2026 totaled 9.18 billion UAH. The company changed its registered address from Zaporizhzhia Oblast to Poltava Oblast.
Second place went to the Pokrovske Mining Administration, with revenue of 6.31 billion hryvnias, which re-registered from the Donetsk region to the Zaporizhzhia region.
In third place is “Podorozhnik Kyiv” with revenue of 5.22 billion UAH. The company, affiliated with the “Podorozhnik” pharmacy chain, changed its region of registration from Lviv Oblast to Kharkiv Oblast.
The combined revenue of the three largest companies totaled 20.71 billion UAH, or about 47% of the total revenue of the top ten.
The top 10 also included “Galychyna-Tabak” with revenue of 4.26 billion UAH, “STV Center” with 4.12 billion UAH, “Interbusiness” with 3.92 billion UAH, “Arion Trade” with 3.83 billion UAH, “Mars Ukraine” with 2.84 billion UAH, “Sovtrading-L” with 2.28 billion UAH, and “SK Energy Group” with 2.13 billion UAH.
The latter company was the most active in terms of the number of changes to its legal address among large businesses: over the course of three quarters, it re-registered four times between Kyiv and the Kharkiv region.
Experts Club notes that the presence of companies with revenues in the billions in the statistics shows that changing one’s legal location remains relevant not only for small and medium-sized businesses but also for large enterprises in the fuel, mining, pharmaceutical, retail, and other sectors.
However, a change of region in the Unified State Register does not necessarily mean an actual relocation of the company’s main assets or production facilities.
Source: OpenDataBot
BUSINESS, COMPANY, EXPERTS CLUB, RANKING, RELOCATION, REVENUE, UKRAINE
Zurich and Tokyo were the only two of the world’s 23 largest cities that UBS classified in 2026 as having a high risk of a housing real estate bubble.
According to the UBS Global Real Estate Bubble Index 2026, published on September 22, Zurich’s index stood at 1.69 and Tokyo’s at 1.54. UBS considers an index above 1.5 to indicate high risk.
The “elevated risk” category included Miami with an index of 1.41, Dubai at 1.16, Seoul at 1.13, Geneva at 1.12, and Lisbon at 1.04.
Moderate risk was recorded in Amsterdam at 0.95, Madrid at 0.86, Los Angeles at 0.69, Sydney (0.68), Frankfurt (0.64), Toronto (0.63), Vancouver (0.62), Munich and Hong Kong (both 0.61), Singapore (0.54), and Milan (0.50).
UBS classified Paris (0.33), London (0.32), New York (0.28), San Francisco (-0.02), and São Paulo (-0.24) as low-risk markets.
In Zurich, real housing prices have risen by nearly 140% over the past 20 years, while rental rates have increased by approximately 40% and household incomes by 30%. The ratio of purchase price to rental cost has reached 46 years—the highest figure among all cities studied by UBS.
In Tokyo, inflation-adjusted housing prices are now about 50% higher than they were seven years ago. Over the past year, they have risen by another 6% or so.
UBS notes that, on average, real housing prices in all surveyed cities rose by only 0.5% over the past year; however, a significant gap has emerged between individual markets.
The bank emphasizes that a high index reading does not predict an inevitable crash. A correction could occur due to changes in interest rates, investor sentiment, or a significant increase in housing supply.
According to Experts.news, Turkish Airlines took first place among European airlines in the regional ranking of the 2026 World Airline Awards by the international organization Skytrax, published on September 18.
Air France took second place among European carriers, and Lufthansa took third. They were followed by Iberia, Virgin Atlantic, Swiss International Air Lines, British Airways, KLM Royal Dutch Airlines, Austrian Airlines, and Finnair.
Thus, the ranking of the top ten European airlines is as follows: Turkish Airlines, Air France, Lufthansa, Iberia, Virgin Atlantic, Swiss, British Airways, KLM, Austrian Airlines, and Finnair.
Skytrax also published separate rankings by European region.
In Western Europe, Air France took first place, Lufthansa second, and Virgin Atlantic third. In Northern Europe, Finnair took the lead, followed by SAS Scandinavian and Icelandair.
In Southern Europe, Turkish Airlines also took first place, Iberia second, and Vueling Airlines third.
In Central Europe, LOT Polish Airlines topped the rankings. Wizz Air took second place, and Croatia Airlines came in third. These carriers are of particular practical importance to Ukrainian passengers, as a significant portion of international flights now operate through airports in neighboring European countries following the closure of Ukraine’s civil airspace.
In Eastern Europe, Latvia’s airBaltic topped the 2026 ranking. Air Serbia came in second, and Georgian Airways took third. Bulgaria Air and Romania’s TAROM also made it into the top five.
The World Airline Awards are based on an international passenger survey. The 2025/2026 survey was conducted from September 2025 through August 2026 and covered more than 300 airlines. Respondents represented over 100 nationalities.



