According to Experts.news, the lack of an effective out-of-court mechanism for settling consumer loan debts contributes to a significant number of court cases between financial companies and borrowers. At the same time, it is precisely the judicial process that allows for verifying the validity of the interest charged and protecting consumers from excessive financial demands, according to Vasyl Krat, a judge of the Supreme Court of Ukraine.
As noted in a study by the analytical service “OpenDataBot,” published on October 28, 2026, all ten of the country’s largest corporate plaintiffs operate in the financial sector.
“Ukr Credit Finance” topped the ranking, with 80,421 court cases filed based on its claims during the incomplete year of 2026. In second place is “Consumer Center” with 68,076 cases.
Overall, among the hundred legal entities that most frequently filed lawsuits in 2026, 39 operate in the lending and other financial services sectors.
Commenting on the study’s findings, Krat noted that current regulations governing the collection of consumer loan debts limit the use of notarial enforcement orders and arbitration proceedings.
As a result, creditors are forced to turn to state courts.
According to the judge, the problem is exacerbated by the financial consequences of a full-scale war. The loss of jobs, income, and property is forcing a portion of the population to resort to accessible forms of short-term lending, particularly microloans.
At the same time, the ability to obtain a loan quickly does not always correspond to the borrower’s ability to fulfill their obligations on time.
Excessive interest rates remain a separate problem.
Krat reported that in one court case, the effective annual interest rate on a loan was 1,139,966%.
This figure, cited by the judge as an example of judicial practice, is not the current permitted rate for new consumer loans.
In Ukraine, a cap on the maximum daily interest rate for consumer loans at 1% has been in effect since August 20, 2024.
This provision was established by Law No. 3498-IX of November 22, 2023, with a phased reduction of the permitted rate during the transition period.
As clarified by the Supreme Court on September 14, 2026, for agreements entered into after the end of the transition period, any provision regarding a daily rate that exceeds the maximum established by law is not applicable to the extent of the excess.
However, the new restrictions do not automatically apply to agreements entered into before the relevant amendments took effect.
In particular, when considering disputes regarding old loan agreements, it is necessary to take into account the date of their conclusion, any possible extension of the loan term, and the provisions of the legislation in effect during the relevant period.
These issues were addressed by the Joint Chamber of the Civil Cassation Court within the Supreme Court, specifically in its ruling of September 7, 2026, in Case No. 552/672/23.
The court noted that, under certain circumstances, excessive or ambiguously worded terms of a loan agreement may be subject to judicial review under consumer protection laws.
At the same time, certain remedies require the borrower to file specific claims, whereas the court may interpret ambiguous provisions of the agreement in favor of the consumer directly during the resolution of the dispute.
This issue has significant economic implications.
According to OpenDataBot, based on statistics from the National Bank of Ukraine, as of July 1, 2026, the total debt of the population to microfinance organizations reached 32.32 billion UAH.
Since the beginning of the year, this figure has increased by 17%, or 4.7 billion UAH.
In the first half of the year, Ukrainians entered into nearly 4.2 million contracts with microfinance organizations totaling 37.5 billion UAH.
The growth in loan debt, combined with restrictions on extrajudicial collection, places an additional burden on the judicial system. At the same time, the available data does not allow for determining what proportion of new court cases is directly related to delinquent microloans and how many of them concern challenges to accrued interest.
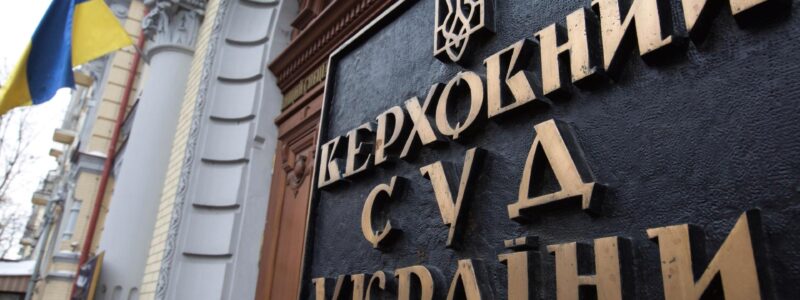
The Supreme Court of Ukraine is the highest court in the country’s judicial system. It includes the Civil Court of Cassation, which hears, among other things, disputes related to the fulfillment of credit obligations and the protection of the rights of consumers of financial services.
Sources: “OpenDataBot,” study dated October 28, 2026; Supreme Court of Ukraine, clarification by Vasyl Krat dated September 14, 2026; Supreme Court, materials from the National Judicial Forum dated October 20, 2026; “OpenDataBot,” microloan debt.
DEBT, INTEREST, LOAN, SUPREME COURT, UKRAINE
Related: