
The Czech oil and gas company MND is considering investing at least $60 million in hydrocarbon production projects in Ukraine as part of a partnership with the Naftogaz Group.
Naftogaz and MND signed a memorandum of understanding on potential cooperation regarding three existing production-sharing agreements between Ukrgazvydobuvannya and the Ukrainian government. The document was signed during the Carpathian Eight Summit, the group reported.
If the agreements are implemented, MND will be able to participate in the development of Ukrainian fields and contribute its own capital, technology, and operational expertise to the projects.
The initial investment under the three agreements could total $60 million. However, the Czech company’s participation has not yet been finalized—it will depend on the results of the relevant competitive selection process.
Naftogaz views attracting international oil and gas companies as one of the tools for increasing its own gas production amid regular Russian attacks on Ukraine’s energy infrastructure.
Serhiy Fedorenko, acting head of Naftogaz, noted that the group is interested in international partners capable of bringing investment, modern technologies, and practical experience.
In turn, Yana Gamrshmidova, CEO of the energy division at MND Group, stated that the company is already contributing to Ukraine’s energy resilience and intends to introduce new technologies and create jobs.
MND is of particular interest as a strategic investor because it is not a financial institution but an active European energy company with its own expertise in hydrocarbon exploration and production.
For Ukraine, attracting such a partner could mean not only an inflow of foreign capital but also access to field development technologies and management expertise from the European oil and gas industry.
The memorandum is not yet a final investment agreement. The parties must still agree on the terms of cooperation, and MND’s potential participation in production-sharing agreements must go through the procedures required by law.
However, the announced initial investment of $60 million makes the initiative one of the most significant new projects involving private European capital in Ukraine’s extractive industry.
Ferrexpo, a mining company with its main assets in Ukraine, reduced its capital expenditures (additions to property, plant, and equipment) by a factor of 2.1 in January–June of this year compared to the same period last year—to $13.892 million from $29.457 million.
According to Ferrexpo’s semi-annual report, additions to property, plant, and equipment totaled $63,755 million as of the end of 2025.
It is also noted that during the six-month period ended June 30, 2026, the net book value of disposals of property, plant, and equipment was $5,509 million (as of December 31, 2025 – $181,000; as of June 30, 2025 – $1,218 million). The total amount of depreciation accrued for this period was $12.951 million (as of December 31, 2025—$65.802 million; as of June 30, 2025—$34.418 million).
Assets under construction include capital projects in progress totaling $196.039 million (December 31, 2025 – $197.838 million; June 30, 2025 – $188.150 million) and capitalized costs for surface development work performed prior to the start of production, amounting to $29,280 million (December 31, 2025 – $31,223 million; June 30, 2025 – $31,712 million), relating to portions of ore bodies expected to be brought into operation only in future periods.
In addition, it is clarified that once ore production begins, capitalized stripping costs are reclassified as mining assets, and depreciation begins to accrue.
The carrying value of property, plant, and equipment includes capitalized borrowing costs related to qualifying assets totaling $18.349 million (as of December 31, 2025 – $21.4 million; as of June 30, 2025 – $23.826 million). During the period ended June 30, 2026, or the comparative periods, no borrowing costs were capitalized.
The report explains that the Group’s impairment testing of assets is based on cash flow projections for the remaining estimated useful lives of the Horishneplavnynske-Lavrykivske and Yeristivske fields, which, according to current approved mining plans, are scheduled to end in 2058 and 2048, respectively.
According to the report, the group’s long-term financial model is continuously updated. This process takes into account current operating conditions, which depend to a significant extent on the stability of the power supply, energy prices, the availability of logistics networks, as well as other potential negative factors caused by the war. Due to current restrictions, the production capacity used to forecast cash flows under the base-case scenario is expected to amount to approximately 32% of the pre-war level in fiscal year 2026, rising to about 63% in 2027 and returning to pre-war levels in the second half of 2028.
Regarding key assumptions, the cash flow forecast for the next five years is based on an average index price for iron ore (65% iron content) of $115 per metric ton on a CFR (Northern China) basis. In assessing the expected long-term sales price, the Group takes into account the results of external and internal analyses of supply and demand dynamics in the international market for iron ore pellets and concentrate in the short and long term, as well as specific local supply and demand indicators affecting the Group’s major customers. Due to growing demand for high-quality concentrate and the expected margin calculated based on projected market conditions, the share of concentrate production in the current long-term model has increased significantly.
At the same time, the Group is expected to adjust the mix of iron ore products in its production plan in accordance with future market conditions and taking into account the operational situation in Ukraine at that time. The Group’s main cost items, in particular production and transportation costs, are determined taking into account local inflationary pressures, the dynamics of the hryvnia-to-U.S. dollar exchange rate, short- and long-term trends in energy supply and demand, as well as expected changes in the prices of raw materials related to steel production, which could significantly affect the cost of certain production materials. Regarding the logistics route through Ukraine’s
Black Sea ports, which is currently inaccessible, given the importance of this route both for the parties to the conflict and for global grain shipments, management believes that the situation will improve in 2027, and therefore expects that Ukraine’s Black Sea ports will once again become accessible to the Group for the purpose of selling to certain markets.
Given the increase in the share of concentrate production in the current long-term model, management analyzed whether this might indicate that the assets used to produce pellets and concentrate constitute two separate cash-generating units (CGUs). After a thorough analysis, management concluded that it remains appropriate to test the
Group’s non-current operating assets as a single CGU, given the high level of vertical integration of production at the Group’s main subsidiary—Poltava Mining and Processing Plant—and the absence of largely independent cash flows.
It is also reported that the Group conducts transactions on market terms with entities under the common control of Kostyantyn Zhevago and his related parties. Such transactions are considered part of the Group’s ordinary course of business. During 2025, the group posted a bond in the amount of 5 million UAH (or approximately $120,000) on behalf of a senior executive of one of the group’s subsidiaries in Ukraine. The bail payment was related to court and other legal proceedings initiated by certain government agencies against the Group’s subsidiaries and senior management representatives in Ukraine. In March 2026, the court overturned the bail order, after which the funds were returned to the subsidiary. No such payments were made during the first six months of 2026.
The Group has virtually no debt obligations: as of June 30, 2026, it had a net cash position of $21 million (compared to $47 million as of December 31, 2025). Excluding lease obligations totaling $10 million (December 31, 2025: $11 million), the Group had no outstanding interest-bearing loans or credits as of June 30, 2026, and December 31, 2025.
As of June 30, 2026, Ferrexpo’s long-term corporate credit rating and debt rating, as assigned by Moody’s, was Caa3 with a “negative” outlook. At the Group’s request, Fitch and S&P no longer provide ratings.
As previously reported, Ferrexpo ended the first half of 2026 with a net loss of $14.9 million, which is 13.2 times less than the figure for the first half of 2025; revenue fell 2.3 times to $196 million. The company reduced capital expenditures (CapEx) to $10 million from $28 million in January–June 2025, allocating 88% of these expenditures to projects necessary to maintain operations and only 12% to development projects.
Ferrexpo owns a 100% stake in Yeristivskyi Mining and Processing Plant LLC, 99.9% of Bilanivskyi Mining and Processing Plant LLC, and 100% of the shares in Poltava Mining and Processing Plant PJSC.
FERREXPO, INVESTMENT, IRON ORE, MINING AND PROCESSING PLANT, UKRAINE
It makes more sense for Ukraine to invest in creating its own network of underground fuel storage facilities than to invest in the construction of facilities for storing strategic reserves in other countries. This opinion was expressed by Serhiy Kuyun, director of the A-95 Consulting Group, according to Enkorr.
Ukrainian legislation allows for up to 50% of the minimum reserves of oil and petroleum products to be stored in countries neighboring Ukraine and up to an additional 25% in countries bordering those neighbors. This practice is common in Europe; however, finding available storage capacity in neighboring countries is complicated by the fact that EU member states themselves are required to maintain significant strategic reserves.
According to Kuyun, as a result, Ukraine may be offered the option to invest not in leasing existing facilities, but in the construction of new storage tanks abroad. Such projects will require lengthy construction periods, local permits and licenses, as well as the outflow of significant foreign currency investments from Ukraine. If a foreign partner finances the project, it may also be necessary to guarantee that the storage facilities remain filled for many years.
The expert cites another problem: the physical ability to quickly deliver strategic reserves to Ukraine in the event of a large-scale fuel crisis.
“Even if we build up reserves abroad, how would we then transport them in an emergency? The border is already strained even under normal conditions—where would we possibly fit in tens or even hundreds of thousands of additional metric tons?” Kuyun noted.
The relevance of this discussion has intensified following agreements between Naftogaz and the Hungarian company MOL. On September 20, the companies signed a memorandum to explore the possibility of storing petroleum products in Hungary near the Ukrainian border to meet the needs of the Ukrainian market. The project is still in its initial stages, and the parties must assess its technical, financial, environmental, and regulatory parameters.
According to Kuyun, a more reliable solution would be to build secure underground storage facilities directly in Ukraine. This would allow for simultaneous investment in Ukrainian infrastructure, increase the security of reserves against Russian attacks, and ensure the ability to bring fuel to market more quickly in a crisis situation.
The first government incentives for such investments have already been established. In September, the government expanded its financial support program for the fuel sector. Loan funds can be used, in particular, to bury or install underground storage tanks, pumping stations, process pipelines, and other fuel infrastructure equipment.
The maximum amount of state-backed lending is 1 billion UAH per company, including affiliated counterparties; the minimum is 100 million UAH; and for projects in combat zones, it is 30 million UAH. The state will subsidize 5.5 percentage points per annum off the bank’s base rate.
According to Kuyun, the next step should be to streamline the approval process for project documentation related to underground fuel storage facilities, as this process can currently take over a year. He noted that several private companies have already begun implementing such projects while simultaneously completing the necessary approval procedures.
“Build our own, invest in Ukraine’s infrastructure! But we need to build underground storage facilities—with a neighbor like this, we’ll always need them,” emphasized the director of “A-95.”
FUEL, INVESTMENT, petroleum product, storage facility, UKRAINE
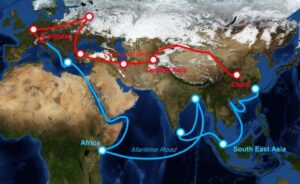
Direct non-financial investments by Chinese companies in countries participating in the “Belt and Road” initiative reached $39.67 billion in 2025, a 17.6% increase from the previous year, according to Ma Shengkun, China’s ambassador to Ukraine.
“Through direct investment, project contracting, and development financing, China has contributed to improving local infrastructure, modernizing industry, and raising the standard of living,” the diplomat wrote in a column on the Interfax-Ukraine website.
According to the data he cited, Chinese investment in Africa grew by 41% in 2025.
Chinese companies have established overseas trade and economic cooperation zones in 46 countries, with total investment in these zones approaching $80 billion.
As an example of industrial cooperation, Ma Shenkun cited a project by the Chinese battery manufacturer CATL in Indonesia. It involves establishing a complete production cycle for traction batteries—from the extraction and processing of nickel and the production of battery materials to the manufacturing and assembly of finished batteries.
According to data cited by the ambassador, the total volume of China’s direct non-financial foreign investment in 2025 reached $145.66 billion.
Ma Shengkun also cited World Bank estimates, according to which the full implementation of transportation projects under the “Belt and Road” initiative has the potential to reduce transit times along the relevant corridors by up to 12% and increase trade among countries located along them by 2.8–9.7%.
As previously reported, China is Ukraine’s largest trading partner. According to calculations by the Experts Club information and analytical center, trade between the two countries in the first half of 2026 totaled $14.68 billion. At the same time, Ukraine imported $13.9 billion worth of Chinese goods and exported $778.4 million worth of goods to China, resulting in a trade deficit of $13.12 billion.
China accounted for 21.9% of Ukraine’s trade with its 50 largest partners and 29.4% of imports from this group of countries. Trade with China accounted for approximately 47.3% of Ukraine’s total trade deficit with its top 50 partners.
According to the State Customs Service, from January through August 2026, imports of goods from China to Ukraine had already exceeded $19.6 billion, maintaining China’s position as the top supplier to the Ukrainian market.
China’s role in Ukraine’s foreign trade is analyzed in more detail in a study by Experts Club and Active Group, published on September 18, 2026.
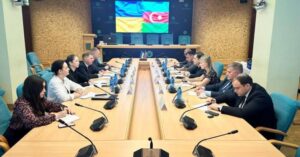
UkraineInvest, Ukraine’s agency for attracting and supporting investment, and Azerbaijan’s Agency for the Promotion of Exports and Investments (AZPROMO) have signed a memorandum of understanding aimed at expanding investment cooperation between the two countries, according to the Ukrainian Embassy in Azerbaijan.
The document was signed in Baku during the 2nd Azerbaijan International Investment Forum by AZPROMO Executive Director Yusif Abdullayev and UkraineInvest Executive Director Marina Khlistun, according to the Ukrainian Embassy in Azerbaijan.
The parties intend to foster direct contacts between businesses in both countries and create conditions for the implementation of joint investment projects.
Ukraine, in particular, is interested in attracting Azerbaijani capital to the country’s reconstruction projects. Potential areas of cooperation include infrastructure, energy, transportation and logistics, the agricultural sector, industry, and technology.
Yuriy Gusev, Ukraine’s ambassador to Azerbaijan, praised the efforts of the leadership and teams at AZPROMO and UkraineInvest in translating the two countries’ strategic partnership into concrete joint investment projects.
AZPROMO also confirmed the signing of the memorandum. According to the Azerbaijani agency, the document between AZPROMO and UkraineInvest was part of a package of 11 agreements signed during the international investment forum.
In total, the agreements concluded during the forum cover construction and development, the digital economy, renewable energy, industry, agriculture, pharmaceuticals, finance, water management, sports, and investment promotion.
The II Azerbaijan International Investment Forum took place in Baku on September 25–26, 2026, under the patronage of Azerbaijani President Ilham Aliyev. The event was organized by the Ministry of Economy of Azerbaijan and AZPROMO in strategic partnership with The European House – Ambrosetti.
UkraineInvest is the state agency responsible for attracting and supporting investment. The organization assists foreign and Ukrainian investors, provides consulting, analytical, and informational support, and participates in promoting Ukraine’s investment projects in international markets.
Around $680 billion in financing annually is needed to transform global agrifood systems by 2030, but the effectiveness of international programs will depend not only on the amount of funding, but also on farmers’ and agribusinesses’ access to finance, markets and economic incentives.
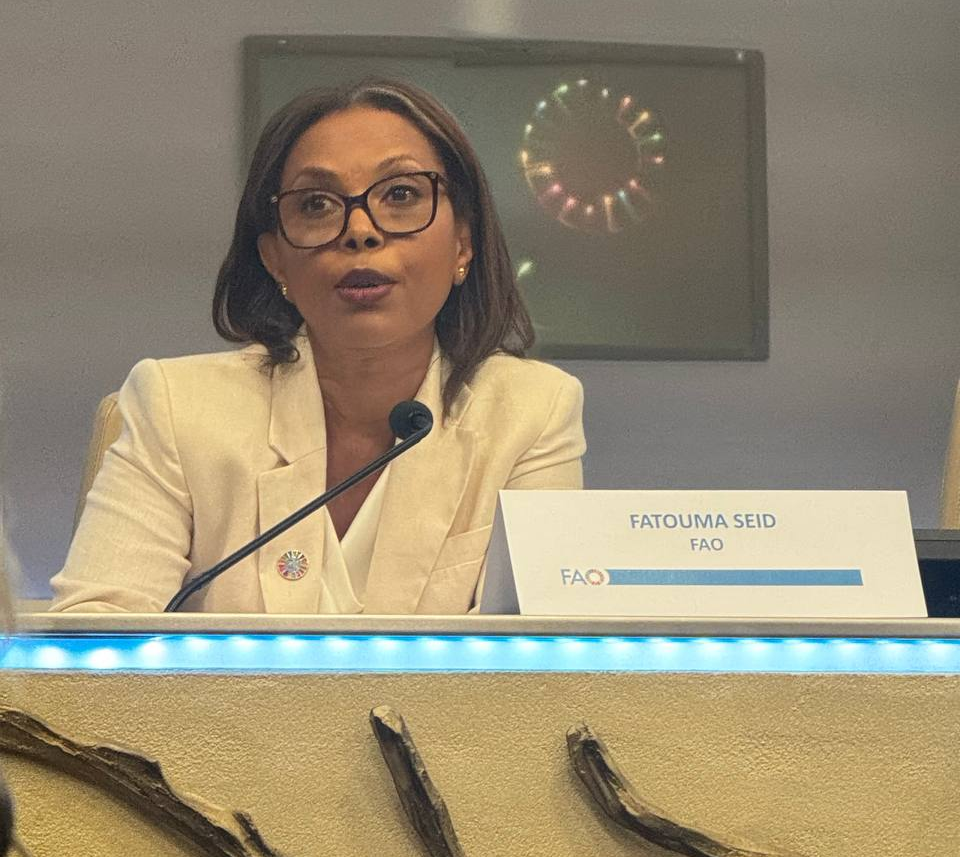
According to SEEDS, financing issues were discussed in Rome during the FAO Global Conference “Actions in One Health in Agrifood Systems,” which took place on September 21–23 and was dedicated to implementing the One Health approach in agrifood systems.
According to FAO estimates, the annual financing requirement for the transformation of agrifood systems in low- and middle-income countries amounts to around $680 billion. Of this amount, approximately $425–426 billion should go directly to investments, with another approximately $255 billion allocated to social protection systems.
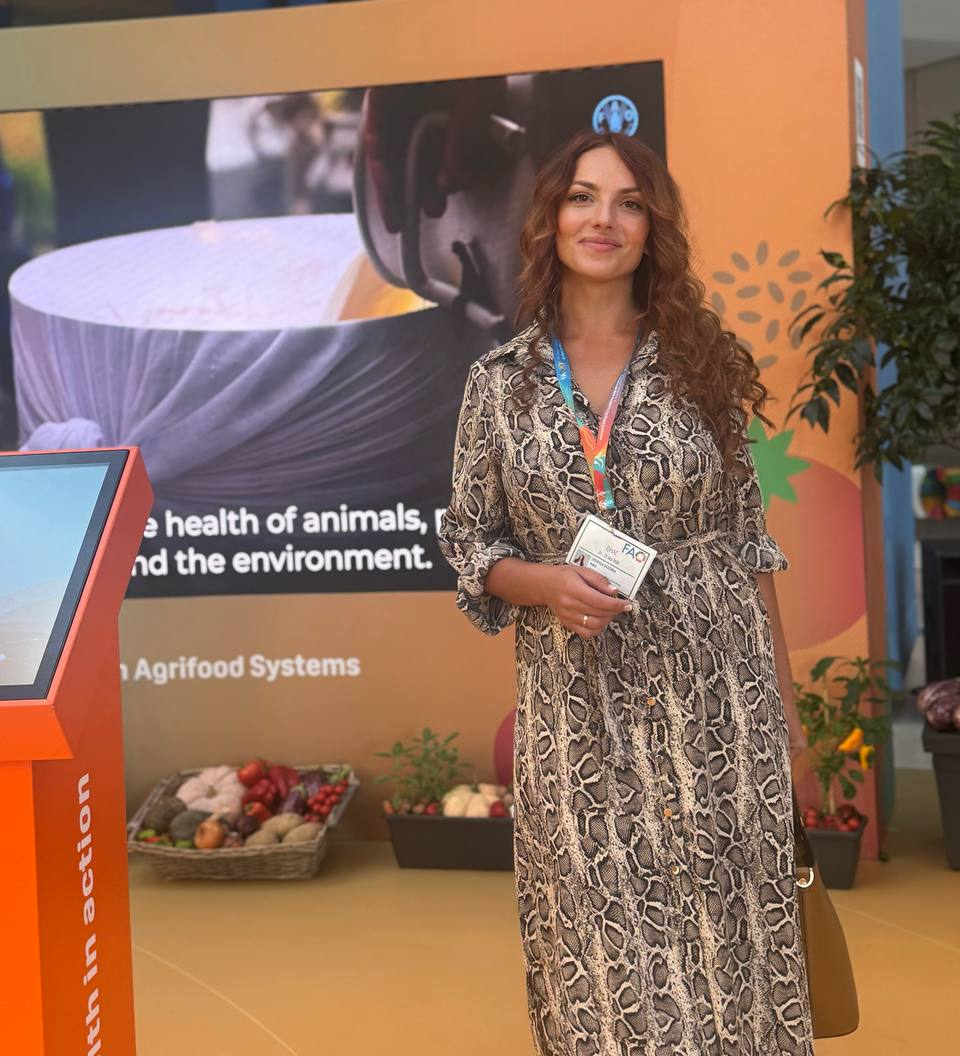
International expert on sustainable agriculture and agrifood systems and founder of Sapienza.media Kateryna Zvierieva, who participated in the conference, stressed that the volume of international financing alone does not guarantee results if resources do not reach direct producers.
“We can develop effective environmental and veterinary solutions, but they will not become widespread practice if the farmer does not have access to financing, sales markets and economic incentives for their implementation,” she said in a comment to SEEDS.
Rwanda became one example of effective fundraising. About $25 million in financing from the Pandemic Fund was accompanied by the mobilization of approximately another $160 million in additional resources and related investments. The program is aimed at strengthening epidemiological surveillance, early warning systems and coordination between human and animal health services. FAO, WHO and UNICEF are involved in its implementation.
During the conference, programs in Zimbabwe and Afghanistan were also discussed, where the One Health approach is used to combine veterinary safety, healthcare, food security and support for agricultural production. Participants stressed that animal diseases, climate risks and water-related problems often extend beyond individual states and require regional investment programs.
The reduction of international assistance remains a separate problem. Representatives of the European Commission drew attention to the need to involve the World Bank, IFC, the International Fund for Agricultural Development and private capital more broadly in financing, since grant resources are insufficient for a large-scale transformation of the agricultural sector.
For Ukraine, these approaches are particularly important due to the need to simultaneously restore agricultural production, infrastructure, the veterinary system and water resources, as well as adapt the sector to EU standards.
According to Zvierieva, international programs should be accessible not only to large institutions, but also directly to agricultural enterprises, cooperatives and small producers. Farmers, in her opinion, should be involved in the development of such programs already at the planning stage, since it is they who can assess the real cost of introducing new technologies and the economic risks for farms.
FAO also emphasizes that without the involvement of the private sector, financial institutions and direct producers, it will be impossible to overcome the global financing gap in agrifood systems.
Source: SEEDS — “$680 billion for the transformation of agrifood systems”



