
According to Experts.news, the lack of an effective out-of-court mechanism for settling consumer loan debts contributes to a significant number of court cases between financial companies and borrowers. At the same time, it is precisely the judicial process that allows for verifying the validity of the interest charged and protecting consumers from excessive financial demands, according to Vasyl Krat, a judge of the Supreme Court of Ukraine.
As noted in a study by the analytical service “OpenDataBot,” published on October 28, 2026, all ten of the country’s largest corporate plaintiffs operate in the financial sector.
“Ukr Credit Finance” topped the ranking, with 80,421 court cases filed based on its claims during the incomplete year of 2026. In second place is “Consumer Center” with 68,076 cases.
Overall, among the hundred legal entities that most frequently filed lawsuits in 2026, 39 operate in the lending and other financial services sectors.
Commenting on the study’s findings, Krat noted that current regulations governing the collection of consumer loan debts limit the use of notarial enforcement orders and arbitration proceedings.
As a result, creditors are forced to turn to state courts.
According to the judge, the problem is exacerbated by the financial consequences of a full-scale war. The loss of jobs, income, and property is forcing a portion of the population to resort to accessible forms of short-term lending, particularly microloans.
At the same time, the ability to obtain a loan quickly does not always correspond to the borrower’s ability to fulfill their obligations on time.
Excessive interest rates remain a separate problem.
Krat reported that in one court case, the effective annual interest rate on a loan was 1,139,966%.
This figure, cited by the judge as an example of judicial practice, is not the current permitted rate for new consumer loans.
In Ukraine, a cap on the maximum daily interest rate for consumer loans at 1% has been in effect since August 20, 2024.
This provision was established by Law No. 3498-IX of November 22, 2023, with a phased reduction of the permitted rate during the transition period.
As clarified by the Supreme Court on September 14, 2026, for agreements entered into after the end of the transition period, any provision regarding a daily rate that exceeds the maximum established by law is not applicable to the extent of the excess.
However, the new restrictions do not automatically apply to agreements entered into before the relevant amendments took effect.
In particular, when considering disputes regarding old loan agreements, it is necessary to take into account the date of their conclusion, any possible extension of the loan term, and the provisions of the legislation in effect during the relevant period.
These issues were addressed by the Joint Chamber of the Civil Cassation Court within the Supreme Court, specifically in its ruling of September 7, 2026, in Case No. 552/672/23.
The court noted that, under certain circumstances, excessive or ambiguously worded terms of a loan agreement may be subject to judicial review under consumer protection laws.
At the same time, certain remedies require the borrower to file specific claims, whereas the court may interpret ambiguous provisions of the agreement in favor of the consumer directly during the resolution of the dispute.
This issue has significant economic implications.
According to OpenDataBot, based on statistics from the National Bank of Ukraine, as of July 1, 2026, the total debt of the population to microfinance organizations reached 32.32 billion UAH.
Since the beginning of the year, this figure has increased by 17%, or 4.7 billion UAH.
In the first half of the year, Ukrainians entered into nearly 4.2 million contracts with microfinance organizations totaling 37.5 billion UAH.
The growth in loan debt, combined with restrictions on extrajudicial collection, places an additional burden on the judicial system. At the same time, the available data does not allow for determining what proportion of new court cases is directly related to delinquent microloans and how many of them concern challenges to accrued interest.
The Supreme Court of Ukraine is the highest court in the country’s judicial system. It includes the Civil Court of Cassation, which hears, among other things, disputes related to the fulfillment of credit obligations and the protection of the rights of consumers of financial services.
Sources: “OpenDataBot,” study dated October 28, 2026; Supreme Court of Ukraine, clarification by Vasyl Krat dated September 14, 2026; Supreme Court, materials from the National Judicial Forum dated October 20, 2026; “OpenDataBot,” microloan debt.
According to Experts.news, all ten of Ukraine’s largest corporate plaintiffs—based on the number of new court cases in 2026—operate in the financial sector. Furthermore, among the 100 most active legal entities that filed lawsuits, 39 are engaged in lending and providing other financial services, according to data from the “OpenDataBot” study published on October 28, 2026.
According to data from the court registry, the largest number of cases filed in the incomplete year of 2026 were initiated by the financial company “Ukr Credit Finance”—80,421.
Second place goes to “Consumer Center” with 68,076 cases, third to “Universal Bank” with 25,544, fourth to “Accent Bank” with 22,002, and fifth to “Factoring Partners” with 19,688.
In sixth place is “Unit Capital” with 19,050 cases. Next are “Digi Finance” with 17,050 cases, “Collect Center” with 16,699, “Credit Capital” with 15,613, and the “European Debt Recovery Agency” with 14,993.
Thus, according to calculations based on the published ranking, the ten largest corporate plaintiffs account for a total of over 299,000 new court cases for the incomplete year of 2026.
At the same time, just two leaders—“Ukr Credit Finance” and “Consumer Center”—appear in 148,497 cases, accounting for nearly half of the top ten’s combined total.
Compared to 2025, the structure of the ranking has changed significantly.
“Ukr Credit Finance” rose from eighth place to first, and “Factoring Partners” rose from 17th to fifth.
“Universal Bank” improved its position from fifth to third, and “Accent Bank” from sixth to fourth. “Unit Capital” rose from ninth to sixth place, “Digi Finance” from 15th to seventh, and “Collect Center” from 13th to eighth.
At the same time, the “European Debt Recovery Agency,” which ranked first in 2025, fell to tenth place.
The ranking indicates a high concentration of legal actions among credit market participants; however, it does not allow for determining what proportion of these lawsuits was successful or what amounts were actually recovered from debtors.
Utilities and energy companies also play a significant role among the top 100 corporate plaintiffs.
According to “OpenDataBot,” 24 entities in the ranking operate in the electricity, gas, heating, and water supply sectors.
Another 14 organizations belong to the public administration sector.
Thus, the most active corporate plaintiffs are predominantly organizations whose activities are related to consumers’ financial obligations, the provision of financial or utility services, and the performance of government functions.
Vasyl Krat, a judge on the Supreme Court of Ukraine, attributes the high level of litigation activity by creditors to the limited options for out-of-court debt collection on consumer loans.
According to him, for banks and financial companies, going to court in many cases remains the primary means of enforcing debt collection.
At the same time, court proceedings allow for verification of the validity of the creditor’s claims, including the legality of the interest charged.
The “OpenDataBot” study covers court cases from 2025–2026 in which legal entities served as plaintiffs. The published results for 2026 are preliminary and are compared with the full previous calendar year.
Source: “OpenDataBot,” a study of Ukraine’s largest corporate plaintiffs dated October 28, 2026.
In August 2026, Ukrainian banks issued 722 mortgage loans totaling 1.54 billion hryvnia, which is 6.7% more than in July, when 710 loans totaling 1.44 billion hryvnia were issued, according to the results of a monthly survey by the National Bank of Ukraine (NBU).
“The quality of the mortgage portfolio is good: the share of non-performing loans is only 11%,” the regulator commented on the situation.
According to the central bank’s data, the volume of loans issued increased by 5.5% compared to August 2025.
As the National Bank specifies, among the 38 surveyed banks—which collectively account for over 95% of the gross mortgage portfolio—11 banks issued new loans in September.
In the primary housing market, 393 transactions totaling 839.2 million UAH were concluded in August, compared to 367 transactions totaling 730.4 million UAH in July. In the secondary market, there were 329 transactions totaling 702.4 million UAH, compared to 343 transactions totaling 714.0 million UAH, respectively.
The weighted average effective interest rate in the primary market rose to 7.7% per annum in August 2026 (7.64% in July), while in the secondary market it fell to 10.0% (10.06%).
Survey data show that the largest number of mortgage loans in August was issued in Kyiv and the Kyiv region—348 loans totaling 793 million UAH, or 51.5% of the total volume. Next came Lviv Oblast—61 loans totaling 141 million UAH, Ivano-Frankivsk Oblast—35 million UAH out of 67 million UAH, and Rivne Oblast—25 million UAH out of 56 million UAH.
In September 2026, Ukrainian banks increased their net loan portfolio by 1.9%, or 25.1 billion UAH, compared to August—to 1 trillion 329.4 billion UAH, while the deposit base increased by 0.7%, or 23.1 billion UAH, to 3 trillion 254.7 billion UAH, according to operational data from the National Bank of Ukraine (NBU).
The main growth came from the corporate segment: the business loan portfolio increased by 15.3 billion UAH, or 1.6%, over the month—to 946.3 billion UAH.
The volume of loans to households at the end of the month stood at 383.1 billion UAH, which is 9.8 billion UAH, or 2.6%, more than a month earlier.
Within the corporate portfolio, hryvnia-denominated loans increased by nearly 0.7%, or 4.3 billion UAH, to 654.9 billion UAH, while foreign-currency loans (in hryvnia equivalent) rose by 3.9%, or 11.1 billion UAH, to 291.4 billion UAH.
On a year-over-year basis, hryvnia-denominated loans to legal entities rose by 32.3%, foreign-currency loans (in hryvnia equivalent) by 29.7%, and the retail loan portfolio by 38.4%.
In the deposit market, the trend was the opposite of that in the loan market: the largest increase came from household deposits, which rose by 21.4 billion UAH, or 1.4%, to 1 trillion 556.0 billion UAH, while corporate deposits increased by 1.8 billion UAH, or 0.1%, to 1 trillion 698.7 billion UAH.
On a year-over-year basis, household deposits increased by nearly 17.0%, and corporate deposits by 14.9%.
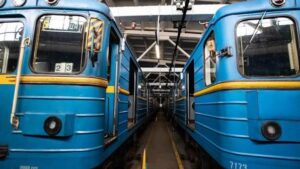
The European Bank for Reconstruction and Development (EBRD) is providing the city of Kyiv with a loan of 150 million euros to purchase new energy-efficient subway cars, spare parts, and maintenance and diagnostic equipment for the Kyiv Metro municipal enterprise, the bank’s press office announced on Wednesday.
The loan is backed by a partial guarantee from Spain and supplemented by grant funding from the bank’s internal resources.
“The new subway cars are expected to be up to 25% more energy-efficient than the outdated cars they will replace, ensuring a more environmentally friendly, safer, and more reliable subway service,” the statement said.
In addition to the purchase of rolling stock, the EBRD will fund an audit of the metro’s accessibility to develop an action plan for inclusive transportation throughout Kyiv, tailored to the needs of people with disabilities, veterans, elderly passengers, and parents with children. The bank will also support a three-year training program for female electric train drivers in partnership with UN Women’s “She Drives” initiative to address the labor shortage.
In total, since the start of Russia’s full-scale invasion in February 2022, the EBRD has allocated nearly 11 billion euros to support Ukraine’s real economy.
EBRD, KYIV, LOAN, METRO, TRANSPORTATION
Ferrexpo, a mining company with its main assets in Ukraine, has secured a $15 million credit line from Fevamotinico SaRL, a company owned by Minco Trust, whose ultimate beneficiary is businessman Konstantin Zhevago.
According to a stock exchange announcement, Ferrexpo plc has entered into a loan agreement with its largest shareholder, Fevamotinico, which will provide an unsecured credit line in the principal amount of $15 million.
The purpose of the loan is to provide the company with immediate access to liquidity until the completion of the capital raising process totaling approximately $100 million, as announced on September 4, 2026, as well as to support working capital needs and production operations, which resumed on September 7. The loan effectively serves as an advance payment of a portion (approximately $40 million) of the funds that Fevamotinico has committed to contribute as part of the capital raising.
It is specified that interest on the loan is accrued at a rate of 9.75% per annum; the maturity date is 12 months after the date the funds are disbursed. Repayment of the loan, together with accrued interest, will be made by offsetting the amounts that Fevamotinico is required to pay to Ferrexpo under the share subscription agreement following the company’s listing. This loan is subordinated; therefore, claims under it will be satisfied after the claims of the company’s existing unsecured creditors.
If the general meeting to be held on September 21, 2026, does not approve the capital raise or if the placement agreement is terminated, the company may decide to repay the loan by issuing new common shares at the placement price (or, if the fair market value is lower than the placement price, at such lower price as agreed upon by the company and Fevamotinico), subject to compliance with all legal or regulatory requirements regarding such issuance of shares, including obtaining prior approval from independent shareholders.
In addition, as long as the loan remains outstanding, the loan agreement restricts the group members’ ability to raise debt or provide collateral for obligations, except for those falling within specified permitted categories (in particular, a potential credit line to finance trade transactions, as well as certain agreements entered into in the ordinary course of business or between group companies) .
The terms of the loan provide for certain standard events of default that entitle Fevamotinico to demand early repayment of the loan. However, Fevamotinico has agreed not to take any action to collect the loan debt in cash prior to its maturity date. The loan agreement also contains a standstill provision, under which Fevamotinico undertakes not to make any claims against Ferrexpo or to initiate proceedings for its liquidation, external administration, or any other insolvency-related proceedings, nor to facilitate such actions by other parties.
If the fundraising does not take place and the placement agreement is terminated, the principal amount of the loan, together with accrued but unpaid interest, will be due for repayment in cash on the maturity date, unless the alternative repayment mechanism described above—involving the transfer of shares—is successfully implemented. If Ferrexpo is unable to repay the loan in cash by the specified deadline, and the alternative repayment mechanism involving shares is not implemented, the company will have to raise additional financing or negotiate other terms for settling the debt with Fevamotinico.
Fevamotinico is a related party of Ferrexpo under the UK Listing Rules, as it is a significant shareholder of the company and has the right to vote (or control the exercise of voting rights) with respect to 49.27% of the votes at the general meeting of shareholders. Accordingly, the granting of the loan is considered a related-party transaction.
The company’s directors consider the terms of the loan to be fair and reasonable in the interests of the shareholders. The Board of Directors received appropriate advice from BDO LLP, which acts as the company’s sponsor. In providing this advice to the directors, BDO LLP took into account the commercial assessment of the loan conducted by the directors themselves.
Ferrexpo owns a 100% stake in Yeristovsky GOK LLC, a 99.9% stake in Bilanivsky GOK LLC, and 100% of the shares in Poltava GOK PJSC.



