
The expansion of its product portfolio allowed IDS Ukraine to offset the loss of profitability following the termination of its contract with Borjomi, which had previously accounted for about a quarter of the group’s profit, said IDS Ukraine CEO Marko Tkachuk.
One of the key factors was the aseptic production line installed even before the full-scale invasion, which allowed the company to expand its production of flavored water and enter new beverage categories.
IDS Ukraine is currently developing “Volya” energy drinks, the “Lemonade” line, flavored waters, and Morshynska Tea.
The company’s sales of non-carbonated flavored water grew by 68%, and its market share approached half of the corresponding segment of the Ukrainian market.
Morshynska Tea, launched in the spring of 2026, has proven particularly successful. Initially, the company viewed it as a test product; however, in some retail chains, it already accounts for over 10% of the iced tea segment. IDS Ukraine intends to expand this line of business. The company officially announced its entry into the
RTD teas on April 1, 2026.
Another new product in 2026 was packaged edible ice made from “Morshynska” water. Sales were temporarily suspended after warehouses with refrigeration equipment were destroyed and logistics became complicated. The company expects to bring the product back to the market in the summer of 2027. The edible ice product was launched in late June 2026.
According to Fixygen, U.S. spot Bitcoin exchange-traded funds (ETFs) saw $986.9 million in net inflows for the week ending September 4, extending their streak of positive weeks to three in a row.
According to SoSoValue data cited by The Block, inflows increased compared to $924.5 million the previous week. BlackRock’s iShares Bitcoin Trust (IBIT) led the way, attracting $691.5 million over the week.
Meanwhile, on September 3, net inflows into all U.S. Bitcoin ETFs reached $730.9 million, marking the highest daily figure since mid-January. The following day, the funds received an additional $174.6 million.
Bitcoin ETF trading volume for the week totaled $14.5 billion, compared to nearly $19 billion the week before. Meanwhile, U.S. spot Ethereum ETFs attracted $218.4 million, also marking their third consecutive week of positive inflows. Their trading volume totaled $4.1 billion.
Overall, August was one of the strongest months for institutional crypto products in the past year. Net inflows into Bitcoin ETFs reached $3.52 billion—the highest since September 2025—while Ethereum ETFs received $1.85 billion, marking their best monthly performance since August of last year.
The shift in sentiment was even more pronounced in the third week of August, when Bitcoin ETFs attracted $1.9 billion, Ethereum ETFs—$697.2 million, and the combined turnover of both categories more than tripled—to $29 billion.
However, inflows remain uneven. Following a strong previous week, approximately $46.6 million was withdrawn from Bitcoin ETFs on September 8. Thus, institutional demand has resumed, but investors remain sensitive to macroeconomic data and expectations regarding U.S. interest rates.
Bitcoin itself corrected after rising above $81,000. According to CoinGecko, on September 9, it was trading at around $78,300, and the cryptocurrency’s market capitalization stood at approximately $1.58 trillion.
Spot Bitcoin ETFs allow investors to gain exchange-traded exposure to Bitcoin without having to store the cryptocurrency themselves. The largest players in the U.S. market are BlackRock, Fidelity, Grayscale, ARK/21Shares, and Bitwise.
Data source — SoSoValue/The Block: Bitcoin ETF flow data
According to the results of the first half of 2026, the IDS Ukraine group of companies increased its share of the Ukrainian bottled water market by 0.9 percentage points in volume terms—to 40.7%, said the group’s CEO, Marko Tkachuk, in an interview with the Interfax-Ukraine news agency.
In monetary terms, the company’s share grew by 1.3 percentage points to 39.9%. In the still water segment, IDS Ukraine holds about 60% of the market in monetary terms and approximately half in volume terms. The market share of its flagship brand, “Morshynska,” stands at 30.3% in liters.
In the first half of the year, IDS Ukraine generated nearly 3.95 billion UAH in revenue. Net profit totaled approximately 188 million UAH, and EBITDA was 440.5 million UAH. The company paid 534.9 million UAH in taxes and fees, an increase of 8.6% compared to the previous year. These figures were also published by IDS Ukraine on August 28, 2026.
However, actual sales in the first half of the year were 7% lower than the initial plan. Compared to the same period in 2025, bottled water sales rose by 2%, and net revenue increased by 11%. By August, the company had already exceeded its monthly sales target by 15%.
IDS Ukraine is one of the largest bottled water producers in Ukraine. The group’s portfolio includes the brands “Morshynska,” “Myrhorodska,” “Alaska,” and others. The group’s history in its current form dates back to the merger of a number of producers and distribution companies in 2004.
According to Fixygen, the cryptocurrency market is ending the first week of September on an uptrend after significant volatility at the start of the week: Bitcoin has returned above the $81,000 mark, Ethereum has approached $2,500, and the total market capitalization has risen to approximately $2.81 trillion. The main driver of this movement was a shift in expectations regarding the U.S. Federal Reserve’s future monetary policy.
According to CoinGecko, as of midday on September 4, Bitcoin was trading at around $81,000, Ethereum at around $2,500, XRP at $1.44–1.45, and Solana at around $104. The total market capitalization of the cryptocurrency market stood at approximately $2.81 trillion, having increased by about 4.5% over the past 24 hours. Bitcoin accounted for about 58% of the market capitalization, while Ethereum accounted for about 11%.
The week started off much weaker. On August 31, Bitcoin was trading at around $78,600; on September 1–2, it fell to $77,000, but then rebounded sharply. On the night of September 4, the price rose to approximately $82,200—a high not seen in more than three months. Thus, compared to the start of the week, BTC has risen in price by about 3%, although the change over the past seven days remains significantly more modest—about 1%. (CoinGecko)
The main reason for the new surge was statements by Federal Reserve Board member Christopher Waller. Speaking on September 3, he said he was prepared to support keeping the interest rate at its current level if incoming data confirmed a further slowdown in inflation. At the same time, Waller did not rule out a rate hike if August inflation accelerates again. Following his remarks, pressure on the dollar and U.S. Treasury yields eased, which supported risk assets, particularly cryptocurrencies.
Ethereum showed more subdued price action throughout the week. After reaching a level of around $2,470 on August 31, ETH fell below $2,400, then recovered to approximately $2,500. XRP, after falling to $1.35, rose again to about $1.45, while Solana climbed above $100. On a seven-day basis, Ethereum and XRP are roughly flat, while Solana is down about 3%.
U.S. spot ETFs remain a key support factor for Bitcoin. Following a net outflow of about $236.5 million on September 1, the funds received about $101 million on September 2, and preliminary data for September 3 already indicates approximately $277 million in inflows.
In August, the total inflow into spot Bitcoin ETFs was estimated at approximately $3.52 billion. However, capital flows remain volatile and do not yet indicate a return to a sustained series of daily purchases.
The situation in the Ethereum market is less clear-cut. On September 2, U.S. spot Ethereum ETFs recorded a net outflow of about $48 million, breaking a streak of 12 trading sessions with inflows, during which the funds attracted about $1.62 billion. This partly explains ETH’s weaker performance compared to Bitcoin in early September.
Among large and mid-cap cryptocurrencies, Zcash stood out as the most notable exception this week: according to CoinDesk, as of September 4, the coin had risen by approximately 20% over seven days and about 15% over the past 24 hours. Hyperliquid also significantly outperformed most major crypto assets.
In the coming days, the market will remain primarily dependent on U.S. macroeconomic data. On September 4, the U.S. Department of Labor is set to release the August employment report, and the Consumer Price Index (CPI) will be released on September 11. These figures will be particularly important ahead of the Fed meeting on September 15–16. The official BLS calendar confirms the release of August labor market data on September 4 and the Consumer Price Index (CPI) on September 11.
The base case scenario for Bitcoin in the near term is that it will remain within a range of approximately $76,000–$83,000. The $76,000–$77,000 zone acted as support several times earlier this week, while the $82,000 level has already become the nearest resistance. A sustained move above $82,000–$83,000, coupled with continued capital inflows into Bitcoin ETFs, could pave the way toward the $85,000–$88,000 level. In the event of strong U.S. inflation or labor market data that once again increases the likelihood of a Fed rate hike, a return to the $76,000–78,000 range becomes the most likely scenario. A break below this support level would significantly worsen the short-term technical picture.
For Ethereum, the $2,400–$2,550 range remains key. A confident break above $2,550 could allow the market to test $2,700–$2,800; however, this would require not only a rise in Bitcoin but also a resumption of a steady inflow of capital into the Ethereum ETF. If sentiment deteriorates, a pullback below $2,400 will once again bring the $2,250–2,300 zone into focus.
Thus, the first week of September has not yet become a full-fledged continuation of August’s strong rally. Rather, the market has entered a phase of testing the levels reached: Bitcoin appears stronger than most major altcoins, institutional demand remains steady, but capital flows through ETFs are volatile. The main drivers for the crypto market over the next two weeks will be U.S. inflation, the Fed’s decision, and Bitcoin’s ability to hold above $82,000.
The Experts Club analytical center analyzed data from the international consulting firm Savills on real estate market trends in the world’s leading countries. Global real estate investment in the second quarter of 2026 reached approximately $250 billion, up 13% compared to the same period last year, according to data from the international consulting firm Savills.
The data was published on August 25 in the report “Savills Takes Stock: Global Capital Markets Research Q2 2026.” According to the company’s assessment, the active portfolio of deals nearing completion suggests that the market will continue to recover in the second half of the year.
Savills estimates that by the end of 2026, global real estate investment volume could increase by approximately 16%.
However, the market recovery is uneven. Investors have become more selective and are concentrating their capital on properties with predictable cash flow, clear value, and long-term demand.
According to a study cited by Experts Club, the U.S. remains the largest market. In the second quarter, investment in U.S. real estate reached approximately $131 billion, a 20% increase from the previous year.
Separately, Savills notes a sharp increase in large portfolio transactions in North America. Their volume reached $35 billion, up 60% year-over-year. By comparison, transactions involving individual properties grew by approximately 10%.
The growth in portfolio investments is linked to the return of large institutional capital and investors’ desire to immediately secure a large-scale presence in promising segments. Data centers, self-storage facilities, and real estate for the elderly are of particular interest.
The European market also continued its recovery. The volume of transactions in the second quarter totaled 54 billion euros, up 7.7% compared to the second quarter of 2025.
In the Asia-Pacific region, investment grew even faster—by 18%, to $46 billion. For the first half of the year, investment volume in the region grew by 25%.
Particularly notable growth in the Asia-Pacific region is being observed in the industrial and logistics real estate sectors. In the second quarter, investment in this segment rose by 17%, and for the first half of the year as a whole—by 28%.
At the same time, interest in student housing and other types of residential real estate is growing. Savills attributes this, in particular, to increased international student mobility and the desire of institutional investors to build large portfolios of income-generating properties.
However, Savills cautions that the market’s recovery cannot yet be considered a widespread new investment boom. Geopolitical tensions, the situation in the Middle East, borrowing costs, and uncertain economic prospects are forcing investors to be much more selective when choosing properties.
In early 2026, deteriorating investment sentiment amid the conflict surrounding Iran even led to negative seasonally adjusted quarterly investment trends. However, the impact of this factor turned out to be less severe than market participants had feared.
According to Savills, the current stage of the cycle is characterized by the return of primarily experienced and well-capitalized players. Therefore, the main factor driving investment decisions is no longer the expectation of general growth in real estate prices, but rather the quality of a specific asset and its ability to generate stable income.
CAPITAL, EXPERTS CLUB, INVESTMENTS, MARKET, REAL ESTATE, Savills
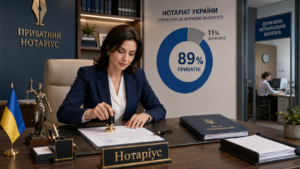
Ukraine continues to see a structural shift of notarial services toward the private sector: as of the end of August 2026, 5,484 out of 6,156 notaries included in the Unified Register of Notaries were working privately.
Thus, the share of private notaries reached about 89%, or almost nine out of ten professionals, according to an Experts Club analysis based on Opendatabot data.
There were 652 notaries working in state notary offices, accounting for about 10.6% of the total number, while another 20 professionals worked in state notarial archives.
Over the past year, the number of private notaries increased by 345 people. At the same time, the number of notaries in state institutions decreased by 34.
As a result, the entire net increase in the register was provided by the private sector. The total number of notaries increased by 311 people over the year, or by approximately 5%, to 6,156.
According to Experts Club, this dynamic indicates a further shift of the Ukrainian notarial services market toward the private model. The state segment is gradually shrinking both in absolute terms and as a share of the total number of professionals.
At the same time, the increase in the register does not mean a similar influx of new personnel. Of the total increase, only 40 notaries were new, while the majority were professionals who renewed their certificates. Another 104 notaries stopped working during the year.
A notable feature of the profession remains the significant predominance of women: they account for 82% of all notaries in Ukraine. Over the year, the number of women in the register increased by 250, while the number of men increased by 61.
Source: Opendatabot, data from the Unified Register of Notaries as of the end of August 2026.



