
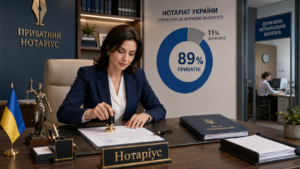
Ukraine continues to see a structural shift of notarial services toward the private sector: as of the end of August 2026, 5,484 out of 6,156 notaries included in the Unified Register of Notaries were working privately.
Thus, the share of private notaries reached about 89%, or almost nine out of ten professionals, according to an Experts Club analysis based on Opendatabot data.
There were 652 notaries working in state notary offices, accounting for about 10.6% of the total number, while another 20 professionals worked in state notarial archives.
Over the past year, the number of private notaries increased by 345 people. At the same time, the number of notaries in state institutions decreased by 34.
As a result, the entire net increase in the register was provided by the private sector. The total number of notaries increased by 311 people over the year, or by approximately 5%, to 6,156.
According to Experts Club, this dynamic indicates a further shift of the Ukrainian notarial services market toward the private model. The state segment is gradually shrinking both in absolute terms and as a share of the total number of professionals.
At the same time, the increase in the register does not mean a similar influx of new personnel. Of the total increase, only 40 notaries were new, while the majority were professionals who renewed their certificates. Another 104 notaries stopped working during the year.
A notable feature of the profession remains the significant predominance of women: they account for 82% of all notaries in Ukraine. Over the year, the number of women in the register increased by 250, while the number of men increased by 61.
Source: Opendatabot, data from the Unified Register of Notaries as of the end of August 2026.
According to Fixygen, buybacks—a strategy long used by public companies to support their stock prices—are becoming one of the main tools of the cryptocurrency market.
In 2026, crypto projects have already allocated approximately $640 million to buy back their own tokens—a historic high, according to the Financial Times.
By comparison, this figure stood at about $545 million for all of 2025, and in 2024, it was just $366,000.
Nearly 90% of current buybacks are accounted for by Hyperliquid and pump.fun.
Hyperliquid allocates virtually all of the platform’s revenue toward purchasing HYPE. Against the backdrop of this policy, the token’s value has risen by approximately 70%.
The economic logic is similar to a stock buyback: a company or protocol uses its cash flow to reduce the number of tokens in free circulation and increase the economic value of the remaining ones.
However, there is a fundamental difference between a token and a stock. A stock represents an ownership stake in a company, whereas a token holder’s rights may be significantly weaker or may not confer any legal right to profits at all.
Therefore, a buyback alone does not guarantee growth. Some projects continued to lose value even after launching buyback programs.
Nevertheless, the emergence of a $640 million buyback market indicates that the cryptocurrency industry is gradually adopting tools from traditional corporate finance.
Companies that built their investment strategies around accumulating Bitcoin have lost over $80 billion in market capitalization since this model peaked in popularity in the summer of 2025.
According to Financial Times calculations, the combined market capitalization of the 50 largest Bitcoin treasury companies fell from approximately $150 billion in July 2025 to $67 billion in August 2026.
The model gained popularity thanks to Michael Saylor’s Strategy. Companies issued stocks or debt securities, used the raised funds to buy Bitcoin, and expected the market to value them higher than the cost of the cryptocurrency on their balance sheets.
As long as Bitcoin was rising, this scheme allowed companies to raise new capital in a virtually endless cycle. But BTC’s drop of about 30% from its October 2025 high disrupted the mechanism.
According to the FT, the shares of 35 companies in the group studied lost more than half their value. Some market participants have already begun selling part of their crypto reserves to service their debts.
In effect, the market has stopped automatically paying a premium simply for having Bitcoin on a company’s balance sheet. Investors are now much more closely scrutinizing a company’s debt, the cost of raising capital, and the business’s ability to fund payments without selling cryptocurrency.
According to Fixygen, Bitcoin returned above the $80,000 mark in late August, posting one of its strongest weekly rallies in recent months, however, the current movement differs from typical cryptocurrency rallies—a significant portion of the demand is coming through regulated exchange-traded funds, and the U.S. government bond market has become one of the key macroeconomic factors.
On Tuesday, August 25, Bitcoin rose above $80,000 and reached a three-month high. According to Reuters, the leading cryptocurrency has gained about 28% since the beginning of August, which could be its best monthly performance since November 2024.
One of the triggers for the rally was action taken by the U.S. Department of the Treasury. On August 19, the Treasury announced that, starting September 9, it would increase the volume of buyback operations for long-term Treasury bonds to support market liquidity. The decline in yields on long-term securities and the simultaneous weakening of the dollar boosted demand for alternative assets, primarily gold and Bitcoin.
But unlike previous cryptocurrency cycles, this demand is now clearly visible within the traditional financial system.
U.S. spot Bitcoin ETFs have shifted from a series of outflows to a steady inflow of capital. According to Farside Investors, the funds saw net inflows of $297.5 million on August 17, $189.3 million on August 18, $517.2 million on August 19, $606.3 million on August 20, and $307.5 million on August 21.
After the weekend, the trend continued: on August 24, the funds attracted another $337.6 million, and on August 25, $314.3 million. Thus, over seven consecutive trading days, net inflows totaled approximately $2.57 billion.
The BlackRock iShares Bitcoin Trust remains the primary recipient of these funds. On August 20 alone, the IBIT received approximately $503 million; on August 24, $208.9 million; and on August 25, another $284.4 million. According to Farside data, the fund’s cumulative net inflow since its launch has already exceeded $62.9 billion.
This strong momentum was further amplified by the closing of short positions. The market was approaching an August reversal after a prolonged decline from the 2025 all-time highs, so a significant portion of traders were bracing for a further drop. The sharp rally forced participants to close out short positions, which added mechanical demand for Bitcoin.
As a result, Bitcoin rose by approximately 23% over the week, while Ethereum gained nearly 29%. After reaching the $80,000 mark, Bitcoin pulled back to the $78,000–$79,000 range, indicating profit-taking following the rapid rally.
In our view, the most interesting development is not the $80,000 mark itself, but the nature of the current demand.
In previous cycles, Bitcoin rose primarily on expectations within the cryptocurrency market itself. Now, it is increasingly becoming part of the same macroeconomic narrative as gold: investors are buying assets whose supply cannot be increased by a decision from a central bank or government.
The difference lies in volatility. While gold remains a conservative safe-haven asset, Bitcoin is effectively becoming a high-risk, highly volatile bet on the weakening of the dollar’s purchasing power.
At the same time, ETFs have made this strategy much more accessible to institutional investors. To increase their exposure to Bitcoin, a fund or asset management firm no longer needs to deal with crypto exchanges or store digital assets on its own—it’s enough to purchase an exchange-traded instrument from BlackRock, Fidelity, or another major asset manager.
That is why capital flows into ETFs are becoming one of the most important indicators of the market’s future direction. If the inflow of several hundred million dollars per day continues, it could provide Bitcoin with fundamental demand even after the short squeeze ends.
If, however, ETFs return to outflows, the current movement risks turning out to be primarily a rapid recovery rally following a sharp decline.
Thus, the near future will show whether Bitcoin has established itself in a new role—not merely as a speculative cryptocurrency, but as an institutional instrument for betting on the dollar, liquidity, and U.S. monetary policy.
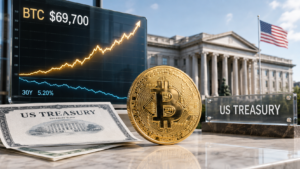
Bitcoin (BTC) saw its price surge sharply on Wednesday evening, rising to $69,700, gaining around $4,000 in a short space of time and reaching its highest level in roughly two months, according to the Fixygen website.
After reaching its intraday high, the leading cryptocurrency corrected to around $68,500–$68,700 but remained up about 6% over 24 hours. The intraday low was around $64,100.
The sharp move began after the US Department of the Treasury announced that it would at least double the volume of buyback operations involving long-term US government bonds, to $4 billion or more per transaction.
Following the news, the yield on 30-year US Treasuries fell by around 8 basis points to 5.20%, with a similar decline observed in 10-year securities. At the same time, the US dollar began to weaken, while demand for risk and safe-haven assets increased.
Initially, following the Treasury’s announcement, bitcoin rose to around $64,900, then broke above $65,000, after which the rally sharply accelerated. At its peak, the price reached $69,700.
The surge triggered large-scale liquidations of short positions in the cryptocurrency market. According to CoinGlass data cited by CoinDesk, approximately $1.3 billion worth of cryptocurrency derivatives positions were liquidated in just one hour, between 14:50 and 15:50 UTC, with more than half of the total involving bitcoin trading pairs. Ethereum liquidations amounted to around $430 million.
The gains spread across virtually the entire major cryptocurrency market. Ethereum rose by around 9%, XRP by more than 6%, and Solana by around 6%.
BTC’s technical movement provided an additional factor. Before the current surge, analysts had noted the formation of an “inverse head and shoulders” pattern on the daily chart. According to technical analyst Aksel Kibar, a sustained breakout above the area around $66,600 could open the way for a move toward $76,000.
At the same time, the rapid pace of the current rally increases the likelihood of short-term volatility: a significant part of the move was amplified by the forced closure of short positions, and after reaching $69,700, bitcoin had already retreated by more than $1,000.
Bitcoin is the world’s largest cryptocurrency by market capitalization. Its supply is algorithmically limited to 21 million coins, with around 20 million BTC currently in circulation. Cryptocurrency prices are characterized by heightened volatility and can change significantly within a short period.
Sales of new passenger cars in July of this year fell by 10.5% compared to the same month in 2025—to 5,754 thousand units, according to a report by “Ukravtoprom” on its Telegram channel.
According to the association, the most popular brand remains Japan’s Toyota, which increased its sales by 20% to 985 units.
Skoda took second place with 693 units (+24%), while VW came in third with 444 units (-10%).
The top ten most popular brands also included Renault with 345 units (-47%); BMW with 308 units (+17%); Hyundai with 298 units (=); Mazda—259 units (+66%); BYD—229 units (-69%); Suzuki—194 units (+39%); and Audi—156 units (-38%).
The Toyota RAV-4 crossover was the month’s best-seller.
According to Ukravtoprom, a total of about 38,800 new passenger cars were sold in the country from January through July, which is 1% less than a year ago.
According to Ukravtoprom, the new passenger car market in 2025 grew by 17% compared to 2024, reaching 81,300 units.



