
Heavy rains in Brazil have degraded the quality of the new coffee crop and could lead to a shortage of high-quality Arabica beans on the global market, while futures for this variety have risen by approximately 35% since June, according to Bloomberg.
Brazil is the world’s largest producer of Arabica and accounts for about 45% of global production, so problems with harvest quality could affect the supply of premium coffee far beyond the country’s borders.
The main problem was extremely heavy rainfall during the harvest. In June, rains knocked a large number of ripe coffee cherries off the trees, after which they lay on waterlogged ground for several days, increasing the risk of fermentation, mold, and undesirable flavors.
According to Simao de Lima, president of the Expocacer cooperative—which unites more than 800 producers in the Cerrado Mineiro region in southeastern Brazil—the rains knocked down an average of about 20% of the coffee cherries, compared to the usual 5–7%.
Thus, this does not represent a 20% loss of Brazil’s entire harvest, but rather significant damage to the crop in one of the most important regions for the production of high-quality Arabica.
The situation was exacerbated by a second wave of rainfall in July. The rains fell on beans that had already been harvested and laid out to dry, forcing some producers to start the drying process all over again.
According to data from the meteorological company Vaisala, rainfall in certain areas of Brazil’s coffee belt in June and July reached 250–500% of the climate norm, and in some places, up to eight times more rain fell than usual.
Quality issues are already affecting the market. Arabica futures have risen by about 35% since June, offsetting a significant portion of the price decline since the beginning of the year.
In the physical market, high-quality Brazilian coffee is selling at a premium of up to 15 cents per pound compared to futures in New York.
The reduction in the volume of coffee meeting the delivery standards for Intercontinental Exchange (ICE) certified warehouses in the U.S. and Europe could prove particularly significant.
In a typical year, approximately 30–35% of the Cerrado Mineiro region’s production meets ICE requirements. Following this year’s rains, de Lima estimates that this share could drop to 10–15%. Meanwhile, coffee stocks in ICE-certified warehouses are already approaching their lowest levels of this century.
This could intensify competition among international roasters for high-quality beans. Bloomberg notes that Brazilian Arabica is used, in particular, by companies such as Starbucks, Lavazza, and Illy.
However, it is still too early to speak of a general coffee shortage. The U.S. Department of Agriculture expects that in the season beginning in October, global coffee supply will exceed consumption by approximately 10 million bags, which would be the largest surplus in six years. One of the main factors is expected to be record production in Brazil itself.
Therefore, the market’s main problem lies not so much in the total volume of coffee as in the availability of high-quality Arabica. Major producers can partially offset the shortage by adjusting the composition of their coffee blends and sourcing beans from other regions; however, for the premium segment, the situation could lead to further increases in purchasing and retail prices.
Weather remains an additional risk for the market. Reuters notes the intensification of the El Niño phenomenon, which in the 2026–2027 season could further increase volatility in the markets for coffee, cocoa, and other tropical agricultural commodities.
Agricultural holding company Kernel has signed a €100 million loan agreement with the Danish Export and Investment Fund (EIFO) to finance the construction of its first wind energy project—a 94.5 MW wind farm with energy storage systems in central Ukraine.
“For Kernel, this is a logical continuation of our long-term strategy to develop renewable energy and strengthen the business’s energy resilience. A stable energy supply for our assets allows us to fulfill international contracts,” said Yevgen Osipov, CEO of the Ukrainian company, as quoted in a press release published on Tuesday.
It is noted that the financing is being provided under a special EIFO program to support investments in Ukraine, and the agreement was signed with the participation of Denmark’s Minister of Business and Competitiveness, Martin Lidegaard.
According to the press release, the wind farm will consist of 21 state-of-the-art wind turbines to be supplied and installed by the Danish company Vestas—one of the world’s leaders in the wind energy sector. The project also includes the installation of industrial energy storage systems, which will help balance electricity production during peak load hours.
“EIFO’s financing sends an important signal to the international investment market. This agreement confirms that even amid a full-scale war, Ukraine remains a country where large-scale private investment projects can be implemented,” Osipov added.
It is noted that the development of renewable energy is one of Kernel’s strategic priorities alongside its core agricultural business; in particular, the agricultural holding is installing solar panels at its grain elevators and building a 106-MW solar power plant in southern Ukraine. In late April of this year, the European Bank for Reconstruction and Development (EBRD) provided the agricultural holding with $45 million in financing for this solar power plant, the total cost of which is estimated at $86 million.
EIFO (Export and Investment Fund of Denmark) is Denmark’s national export and investment agency. Since the start of the war, EIFO has financed more than 30 projects in Ukraine. The Kernel project is the second wind energy project in Ukraine financed by EIFO and is part of broader support for the Ukrainian energy sector.
Vestas is one of the world’s leading companies in the wind energy sector, with over 203 GW of installed capacity worldwide. In Ukraine, Vestas has 888 MW of wind capacity that is either already installed or currently under construction.
Kernel Agricultural Holding is the world’s largest producer and exporter of sunflower oil, Ukraine’s largest grain exporter, the operator of an extensive network of logistics assets, and a leading producer of grains and oilseeds in Ukraine. It is one of the largest producers and sellers of bottled oil in Ukraine. It is engaged in the cultivation and sale of agricultural products.
For the first nine months of fiscal year 2026 (beginning July 1, 2025), Kernel saw its net profit decline by 5% to $208 million, revenue increase by 0.4% to $3.092 billion, and EBITDA rise by 1% to $403 million.
Wheat trade in Ukraine remains sluggish, while the corn market continues to see some activity, primarily along the western border, consulting firm Barva Invest reported on its Telegram channel.
According to the firm, prices for Ukrainian wheat with an 11.5% protein content on a DAP-Danube basis stand at $166–168 per metric ton.
“An imbalance between supply and demand persists in the Ukrainian wheat market. A shortage of EU quotas, logistics at the western border booked months in advance, and the absence of panic among importers are holding back trading activity and putting downward pressure on prices,” the report states.
Quotes for Ukrainian corn on a DAP Izov basis stand at $173 per metric ton.
“The Ukrainian corn market is in the off-season and awaiting the resumption of deep-water exports. Some activity continues along the western border for both the old crop and forward contracts,” analysts note.
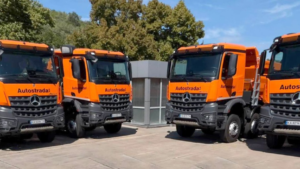
The “Autostrada” Group of Companies purchased 100 new Mercedes-Benz Arocs dump trucks with a total value of 1 billion UAH, according to the group’s founder, Maksym Shkil.
“Autostrada continues to systematically invest in expanding its fleet and its own production capabilities. The company has purchased 100 new Mercedes-Benz Arocs 5 4142 K (8×4) dump trucks. This is one of Autostrada’s largest investments in fleet modernization since the start of the full-scale war—it totals 1 billion hryvnia,” Shkil wrote on Facebook on Tuesday.
According to him, the group has invested over 10 billion hryvnia in vehicles, specialized equipment, and production facilities since the start of the war.
Shkil emphasized that a key component of this particular deal was comprehensive protection for the vehicles against military risks: all vehicles have full insurance coverage, including comprehensive coverage (CASCO), civil liability, and additional insurance against military risks.
The new dump trucks have already been dispatched to Autostrada’s construction sites throughout Ukraine.
Mercedes-Benz Arocs trucks are designed for intensive use and heavy loads. The 421-ks OM 471 engines, 8×4 wheel configuration, and MEILLER Halfpipe bodies provide the necessary performance for operating in challenging road and working conditions.
“Even amid the war, we continue to develop our own technical infrastructure, implement modern technologies, and invest in our team. This approach allows us to control key production processes, reduce dependence on external resources, and ensure on-time delivery, quality, and results at every stage of project implementation,” Shkil emphasized.
The purchase was financed in partnership with OTP Leasing Ukraine, with which Autostrada has been collaborating for 10 years.
The Autostrada Group of Companies is a leader in infrastructure construction in Ukraine. Its areas of activity include road construction, bridge construction, industrial construction, underground construction, and design.
According to data from YouControl, in January–June of this year, Autostrada Group LLC reported 2.4 million UAH in net profit (compared to 91.1 million UAH for the same period in 2025) and 1.92 billion UAH in net revenue (5.13 billion UAH).
As previously reported, a missile strike on “Autostrada’s” production facility in Kyiv in early August destroyed and damaged more than 20 pieces of equipment, a concrete plant, a service center for equipment repairs, production facilities, and a laboratory complex.
Autostrada, dump truck, EQUIPMENT, INVESTMENT, MERCEDES-BENZ, ШКІЛЬ
According to Fixygen, the Central Bank of Uzbekistan is exploring the possibility of introducing a wholesale central bank digital currency (CBDC), while also testing stablecoins and intending to continue reducing the state’s share in the banking sector.
Representatives of the regulator made these statements at the Silk Road Finance & Technology Forum 2026, which is taking place in Tashkent from August 24–26. The forum was organized by the Central Bank of Uzbekistan and the Global Finance & Technology Network (GFTN). More than 6,000 representatives from 74 countries are participating.
Nodirbek Achilov, Deputy Chairman and Member of the Board of the Central Bank, stated that the regulator is analyzing international experience with wholesale CBDCs, including both successful and unsuccessful projects.
Unlike a retail digital currency, which could potentially be used by the general public for everyday payments, a wholesale CBDC is intended primarily for settlements between banks and other financial institutions. Among the potential benefits of such an instrument, Achilov cited increased security and efficiency in interbank settlements.
The central bank is also testing a stablecoin system in a special regulatory regime in collaboration with Uzbekistan’s National Agency for Prospective Projects. A decision on further scaling up the project is planned to be made after the completion of research and an assessment of the financial market’s reaction. The topic of stablecoins, central bank digital currencies, and the tokenization of real assets is one of the distinct themes of the forum’s program.
At the same time, the Central Bank plans to continue privatization and reduce the state’s presence in the banking system. Central Bank Governor Timur Ishmetov stated that over the past few years, the state’s share in the sector has decreased from approximately 85% to 60%. “We will continue this trend,” Ishmetov said.
Official Central Bank statistics show that as of June 1, 2026, banks with state participation accounted for about 63% of the banking system’s assets, 66% of the loan portfolio, and 59% of capital. Total assets of commercial banks amounted to 984.4 trillion sum.
The regulator is also preparing to publish a strategy for foreign exchange interventions. According to Ishmetov, the Central Bank’s operations in the foreign exchange market are not aimed at keeping the sum exchange rate at a specific fixed level. Interventions, in particular, are related to gold purchases and the regulation of the money supply.
The Central Bank intends to continue maintaining a flexible, market-oriented exchange rate and to present plans for further liberalization of capital account transactions. “We are ready to be more open and transparent,” Ishmetov noted.
In addition, the Central Bank has prepared a three-year roadmap for reforming banking regulation following the Financial Sector Assessment Program (FSAP) conducted by the IMF and the World Bank. The regulator plans to align requirements with the international Basel III standards and transition banks to reporting under International Financial Reporting Standards (IFRS). The Silk Road Finance & Technology Forum is being held in Uzbekistan for the first time. The organizers cite positioning the country as a regional hub for financial technology in Central Asia as one of the forum’s goals. Specific sessions of the forum are dedicated to digital assets, payment infrastructure, artificial intelligence, cross-border payments, tokenization, and CBDCs.
China retained its status as the world’s largest zinc producer at the end of 2025, while Peru and Russia posted the most notable growth among the leading producing countries. Global zinc production returned to growth after several years of sluggish performance, according to the Experts Club information and analytical center.
This is evidenced by data from the U.S. Geological Survey’s (USGS) Mineral Commodity Summaries 2026, published on February 6, 2026, and subsequently updated in May. The USGS describes this report as the earliest comprehensive source of data on global mineral production for 2025.
Largest zinc-producing countries in 2025
According to USGS estimates, the ranking of the leading producers is as follows:
| Rank | Country | Mine production in 2025 | Mine production in 2024 |
|---|---|---|---|
| 1 | China | 4.10 million tonnes | 4.00 million tonnes |
| 2 | Peru | 1.50 million tonnes | 1.27 million tonnes |
| 3 | Australia | 1.10 million tonnes | 1.10 million tonnes |
| 4 | India | 870,000 tonnes | 870,000 tonnes |
| 5 | Mexico | 780,000 tonnes | 773,000 tonnes |
| 6 | United States | 670,000 tonnes | 759,000 tonnes |
| 7 | Bolivia | 500,000 tonnes | 512,000 tonnes |
| 8 | Russia | 430,000 tonnes | 310,000 tonnes |
| 9 | Kazakhstan | 360,000 tonnes | 380,000 tonnes |
| 10 | Sweden | 230,000 tonnes | 239,000 tonnes |
Thus, the ten largest producers accounted for approximately 10.54 million tonnes, or 81% of global mine production, based on the USGS estimate of 13 million tonnes.
China increased production by approximately 2.5% to 4.1 million tonnes and accounted for almost one-third of global mine production. The gap between China and its closest competitors remains enormous: Chinese enterprises mined almost as much zinc as Peru, Australia and India combined.
One of the main changes in 2025 was the increase in mine production in Peru by approximately 18%, to 1.5 million tonnes. The country strengthened its second-place position in the global ranking. The International Lead and Zinc Study Group (ILZSG) linked the growth, in particular, to increased production at the large Antamina polymetallic mine and the recovery of other capacities.
The position of Russia changed significantly. According to USGS estimates, mine production increased from 310,000 tonnes in 2024 to 430,000 tonnes in 2025, allowing the country to move ahead of Kazakhstan and approach Bolivia. One of the key factors was increased production at the new Ozernoye deposit in Buryatia, where concentrate output began in September 2024. The ILZSG also cited the commissioning of Ozernoye as one of the factors behind the growth of European zinc production in 2025.
The United States moved in the opposite direction. U.S. mine production declined by approximately 12%, from 759,000 to 670,000 tonnes. The USGS attributes the decline mainly to lower zinc grades in the ore at the Red Dog mine in Alaska. The mine’s operator, Teck Resources, reported that Red Dog itself reduced zinc production from 555,600 tonnes in 2024 to 462,700 tonnes in 2025.
Why the 2025 ranking does not include separate positions from 11th to 20th
Unlike some previous statistical compilations, the USGS Mineral Commodity Summaries 2026 does not disclose separate country figures beyond tenth place. Their production is combined under the Other countries category, which accounted for approximately 2 million tonnes of zinc in 2025. Therefore, compiling an accurate top 20 exclusively from publicly available USGS statistics would be incorrect. A detailed ILZSG country database exists, but the complete dataset is available by subscription.
At the same time, notable changes occurred among second-tier producers. Mine production grew particularly rapidly in the Democratic Republic of the Congo following the commissioning of the Kipushi mine. Ivanhoe Mines reported that this mine alone produced 203,200 tonnes of zinc in concentrate in 2025, compared with approximately 50,000 tonnes during its start-up period in 2024. Thus, the DR Congo has already approached the production volumes of the group of countries immediately following the top ten.
The ILZSG also noted growth in mine production in 2025 in South Africa, Ireland, Bosnia and Herzegovina and other European countries. Irish mine production recovered following the return of the Tara mine to operation, while additional supply came from new and expanding projects in the DR Congo, Russia and Iran.
Global zinc mine production returned to growth
The USGS estimates global zinc mine production in 2025 at approximately 13 million tonnes, compared with a revised 11.9 million tonnes a year earlier. At the same time, later ILZSG statistics provide a somewhat more conservative market estimate. According to data published by the group on April 23, 2026, global zinc mine production increased by 4.8% in 2025, reaching approximately 12.5 million tonnes. The difference is explained by the timing of the estimates, methodological differences and subsequent data revisions.
The main sources of additional supply were increased mine production in Peru and China, the commissioning and ramp-up to design capacity of new large mines, including Kipushi in the DR Congo and Ozernoye in Russia, as well as the recovery of several European enterprises.
At the same time, the USGS estimates global zinc reserves that are economically recoverable at approximately 240 million tonnes. The largest reserves are concentrated in Australia, with approximately 64 million tonnes, China with 60 million tonnes and Russia with 29 million tonnes. They are followed by Peru with 18 million tonnes and Mexico with 14 million tonnes.
Zinc remains one of the key industrial non-ferrous metals. Its main use is the galvanization of steel to protect it against corrosion, primarily in construction, infrastructure and the automotive industry. Zinc is also used to produce brass, alloys, chemical products and several new energy-storage systems.
CHINA, MINING, PERU, zinc, ZINC MINING



