
Ferrexpo plc, a mining and ore processing company with its main assets in Ukraine, produced 2,041,789 metric tons of pellets in January–September of this year, which is 27% lower than in January–September of last year (2,808,594 metric tons), and in the third quarter, it reduced production of this product by 24% compared to the second quarter—to 656,650 thousand metric tons from 860,213 thousand metric tons.
According to the company’s press release on Wednesday, total production of marketable products (pellet and iron ore concentrate) for the first nine months of 2026 fell by 54% compared to the first nine months of 2025—to 2,336,135 metric tons. In particular, production of premium-grade Fe67% concentrate totaled 294,346 thousand metric tons, compared to 2,259,294 thousand metric tons (a decline of 87%). The company also produced 1,737,398 thousand metric tons of premium-grade pellets (a 36% decrease) and 304,391 thousand metric tons of DR pellets (compared to 81,787 thousand metric tons produced in the first nine months of 2025).
The press release notes that Ferrexpo remains committed to ensuring the safety and well-being of its personnel and continues to take extensive measures to protect employees, their families, and local communities.
At the end of August 2026, the Group recorded an increase in the Lost-Time Injury Frequency Rate (LTIFR)—calculated as a 12-month rolling average—to 0.28 (compared to 0.18 at the end of June); however, this rate remains below the five-year average (0.44). August 2026 marked the sixth consecutive year without a single fatality at the
Group’s production facilities; however, as reported in July 2026, an incident occurred involving a chartered vessel carrying Ferrexpo cargo: it was struck and damaged by Russian drones, resulting, unfortunately, in the death of a crew member.
A liquidity shortage, limited logistics capacity, and a temporary halt in production led to a decline in output during the reporting quarter: total production in the third quarter amounted to 780,000 metric tons, down from 963,000 metric tons in the second quarter.
The share of high-quality DR (direct reduction) pellets in the overall product mix remained stable throughout the quarter, and in quantitative terms, their production volume from the beginning of the year through the end of September increased by 272% compared to the same period last year.
On September 4, 2026, the Group announced that it had successfully raised approximately $100 million in capital; this decision received overwhelming support from shareholders on September 21, 2026. The funds raised strengthened the company’s balance sheet and enabled it to resume production.
The Group continues to actively manage its cash expenditures. These measures include reducing staff working hours, steadily cutting back on purchases of goods and services, and suspending all non-critical capital expenditures (CapEx), overhead costs, and expenditures on corporate social responsibility programs. The Group remains in the final stages of negotiations with a reputable trade finance provider regarding a secured credit line (as previously reported); however, the timing of the finalization of the definitive documents has been affected, in particular, by prolonged logistical disruptions on the Group’s Black Sea export route and, as a result, the Group’s ability to deliver products to the trade finance provider under the relevant purchase and sale agreement. Since the potential financing agreement has not yet been concluded, there is no certainty that it will be signed on the terms described or concluded at all.
Commenting on the Group’s performance, Acting Chairman of the Board of Directors Lucio Genovese noted: “In September, we were pleased to note that Ferrexpo’s shareholders approved, by an overwhelming majority, a $100 million capital raise. This process took place under challenging conditions. Over the summer months, the economic situation in Ukraine deteriorated, which, combined with various legal proceedings against the group, posed a serious test of investors’ willingness to invest in Ukraine. Despite this, we managed to successfully complete the capital raise, receiving subscriptions that exceeded the planned amount.”
According to him, raising funds was necessary because the decision by Ukrainian tax authorities to delay VAT refunds significantly weakened our cash position. Limited liquidity forced us to cut production volumes and implement even stricter cost-cutting measures. “We took extensive measures to address this situation, including making difficult decisions to place employees on mandatory leave or switch them to a reduced workweek. We recognize that this has been a source of immense stress for our employees amid already difficult circumstances, and that the resulting reductions in wages, procurement volumes, and tax payments have had a broader socioeconomic impact on the community,” the press release states.
It also notes that, despite our significant efforts, it eventually became clear that additional funds were needed to maintain production, as well as to preserve jobs and livelihoods.
“Raising funds has allowed us to resume production, albeit at significantly lower volumes compared to the period before the full-scale invasion. Due to significant restrictions on access to Ukrainian ports, opportunities to increase exports—and thus production capacity—are currently limited. Due to the temporary suspension of production in
August and the launch of a single pellet production line in September, total production for the quarter amounted to just under 800,000 metric tons,” the press release states.
As previously reported, Ferrexpo produced 3,221,461 metric tons of pellets in 2025, which is 47% lower than in the previous year (6,070,541 metric tons). At the same time, total production of marketable products (pellets and iron ore concentrate) for 2025 decreased by 9%—to 6,141,759 metric tons. Specifically, production of marketable concentrate amounted to 2,920,298 metric tons, compared to 709,803 metric tons, respectively. The company also produced 81,787 thousand metric tons of DR pellets (489,720 thousand metric tons in 2024) and 3,139,674 thousand metric tons of premium-grade pellets (a 44% decrease).
In 2024, Ferrexpo increased pellet production by 58% compared to 2023—to 6,070,541 metric tons from 3,845,325 metric tons. In 2023, the company produced 3.845 million metric tons of pellets, which is 36.5% less than in 2022.
Ferrexpo owns a 100% stake in Yeristivsky GZK LLC, a 99.9% stake in Bilanivsky GZK LLC, and 100% of the shares in Poltavsky GZK PJSC.
In January–September of this year, Ukraine’s mining companies reduced exports of iron ore raw materials (IORM) by 29.8% in volume terms compared to the same period last year—down to 16,948,958 metric tons from 24,145,038 metric tons.
According to statistics released by the State Customs Service (SCS), 1,174,008 thousand metric tons of iron ore were exported in September, 1,865,697 thousand metric tons in August, 1,875,428 thousand metric tons in July, in June—2,021,299 metric tons; in May—2,239,167 metric tons of raw materials; in April—2,163,837 metric tons; in March—2,300,467 metric tons; in February – 1,254,516 thousand metric tons, in January – 2,054,539 thousand metric tons.
Over the first nine months of 2026, foreign exchange earnings from mineral ore exports decreased by 29% to $1,286,304 million.
In addition, Ukraine imported 246 metric tons of raw materials worth $74,000 in January–September 2026, whereas in January–September 2025, it imported 107,000 metric tons worth $80,000.
As previously reported, Ukraine’s mining companies reduced ore exports in physical terms by 8% in 2025 compared to the previous year—to 30,995,363 metric tons from 33,699,722 metric tons, and foreign exchange earnings decreased by 16.6%—to $2 billion 337.765 million from $2 billion 803.223 million. Exports were primarily shipped to China (44.98% of shipments in monetary terms), Slovakia (17.15%), and Poland (16.09%).
In addition, in 2025, Ukraine imported $95,000 worth of raw materials totaling 130 metric tons from the Netherlands (46.32%), Italy (36.84%), and Norway (13.68%), whereas in the previous year it imported 2,042 metric tons worth $414,000
EXPORTS, IRON ORE, METALLURGY, mining and metallurgical complex, UKRAINE
Ferrexpo, a mining company with its main assets in Ukraine, reduced its capital expenditures (additions to property, plant, and equipment) by a factor of 2.1 in January–June of this year compared to the same period last year—to $13.892 million from $29.457 million.
According to Ferrexpo’s semi-annual report, additions to property, plant, and equipment totaled $63,755 million as of the end of 2025.
It is also noted that during the six-month period ended June 30, 2026, the net book value of disposals of property, plant, and equipment was $5,509 million (as of December 31, 2025 – $181,000; as of June 30, 2025 – $1,218 million). The total amount of depreciation accrued for this period was $12.951 million (as of December 31, 2025—$65.802 million; as of June 30, 2025—$34.418 million).
Assets under construction include capital projects in progress totaling $196.039 million (December 31, 2025 – $197.838 million; June 30, 2025 – $188.150 million) and capitalized costs for surface development work performed prior to the start of production, amounting to $29,280 million (December 31, 2025 – $31,223 million; June 30, 2025 – $31,712 million), relating to portions of ore bodies expected to be brought into operation only in future periods.
In addition, it is clarified that once ore production begins, capitalized stripping costs are reclassified as mining assets, and depreciation begins to accrue.
The carrying value of property, plant, and equipment includes capitalized borrowing costs related to qualifying assets totaling $18.349 million (as of December 31, 2025 – $21.4 million; as of June 30, 2025 – $23.826 million). During the period ended June 30, 2026, or the comparative periods, no borrowing costs were capitalized.
The report explains that the Group’s impairment testing of assets is based on cash flow projections for the remaining estimated useful lives of the Horishneplavnynske-Lavrykivske and Yeristivske fields, which, according to current approved mining plans, are scheduled to end in 2058 and 2048, respectively.
According to the report, the group’s long-term financial model is continuously updated. This process takes into account current operating conditions, which depend to a significant extent on the stability of the power supply, energy prices, the availability of logistics networks, as well as other potential negative factors caused by the war. Due to current restrictions, the production capacity used to forecast cash flows under the base-case scenario is expected to amount to approximately 32% of the pre-war level in fiscal year 2026, rising to about 63% in 2027 and returning to pre-war levels in the second half of 2028.
Regarding key assumptions, the cash flow forecast for the next five years is based on an average index price for iron ore (65% iron content) of $115 per metric ton on a CFR (Northern China) basis. In assessing the expected long-term sales price, the Group takes into account the results of external and internal analyses of supply and demand dynamics in the international market for iron ore pellets and concentrate in the short and long term, as well as specific local supply and demand indicators affecting the Group’s major customers. Due to growing demand for high-quality concentrate and the expected margin calculated based on projected market conditions, the share of concentrate production in the current long-term model has increased significantly.
At the same time, the Group is expected to adjust the mix of iron ore products in its production plan in accordance with future market conditions and taking into account the operational situation in Ukraine at that time. The Group’s main cost items, in particular production and transportation costs, are determined taking into account local inflationary pressures, the dynamics of the hryvnia-to-U.S. dollar exchange rate, short- and long-term trends in energy supply and demand, as well as expected changes in the prices of raw materials related to steel production, which could significantly affect the cost of certain production materials. Regarding the logistics route through Ukraine’s
Black Sea ports, which is currently inaccessible, given the importance of this route both for the parties to the conflict and for global grain shipments, management believes that the situation will improve in 2027, and therefore expects that Ukraine’s Black Sea ports will once again become accessible to the Group for the purpose of selling to certain markets.
Given the increase in the share of concentrate production in the current long-term model, management analyzed whether this might indicate that the assets used to produce pellets and concentrate constitute two separate cash-generating units (CGUs). After a thorough analysis, management concluded that it remains appropriate to test the
Group’s non-current operating assets as a single CGU, given the high level of vertical integration of production at the Group’s main subsidiary—Poltava Mining and Processing Plant—and the absence of largely independent cash flows.
It is also reported that the Group conducts transactions on market terms with entities under the common control of Kostyantyn Zhevago and his related parties. Such transactions are considered part of the Group’s ordinary course of business. During 2025, the group posted a bond in the amount of 5 million UAH (or approximately $120,000) on behalf of a senior executive of one of the group’s subsidiaries in Ukraine. The bail payment was related to court and other legal proceedings initiated by certain government agencies against the Group’s subsidiaries and senior management representatives in Ukraine. In March 2026, the court overturned the bail order, after which the funds were returned to the subsidiary. No such payments were made during the first six months of 2026.
The Group has virtually no debt obligations: as of June 30, 2026, it had a net cash position of $21 million (compared to $47 million as of December 31, 2025). Excluding lease obligations totaling $10 million (December 31, 2025: $11 million), the Group had no outstanding interest-bearing loans or credits as of June 30, 2026, and December 31, 2025.
As of June 30, 2026, Ferrexpo’s long-term corporate credit rating and debt rating, as assigned by Moody’s, was Caa3 with a “negative” outlook. At the Group’s request, Fitch and S&P no longer provide ratings.
As previously reported, Ferrexpo ended the first half of 2026 with a net loss of $14.9 million, which is 13.2 times less than the figure for the first half of 2025; revenue fell 2.3 times to $196 million. The company reduced capital expenditures (CapEx) to $10 million from $28 million in January–June 2025, allocating 88% of these expenditures to projects necessary to maintain operations and only 12% to development projects.
Ferrexpo owns a 100% stake in Yeristivskyi Mining and Processing Plant LLC, 99.9% of Bilanivskyi Mining and Processing Plant LLC, and 100% of the shares in Poltava Mining and Processing Plant PJSC.
FERREXPO, INVESTMENT, IRON ORE, MINING AND PROCESSING PLANT, UKRAINE
Ferrexpo, a mining company with assets in Ukraine, ended the first half of 2026 with a net loss of $14.9 million, which is 13.2 times less than in the first half of 2025, according to the company’s report released on Friday.
According to the report, revenue fell 2.3-fold to $196 million due to a decline in sales volume, while EBITDA was negative at $4 million, compared to a positive $4 million in the first half of 2025, reflecting the combined impact of lower sales volumes and selling prices, as well as rising production costs.
Following the morning release of the financial results, the stock rose from 28.9 pence to 32.88 pence and closed at 32.48 pence, representing a 13.33% increase over the previous day’s closing price. The last time the stock traded at such a high price was more than five months ago.
Ferrexpo noted that it deliberately reduced capital expenditures (CapEx) to $10 million from $28 million in January–June 2025, allocating 88% of these expenditures to projects necessary to sustain operations and only 12% to development projects.
Due to prolonged delays in VAT refunds and the resulting decline in financial liquidity, the group was forced to reduce production to a single pellet production line, according to the report.
Total commercial output for the first half of the year amounted to 1.556 million metric tons, which is 40% less than in the previous half-year (ending December 31, 2025) and 54% less than in the first half of 2025.
The production mix in the first half of 2026 consisted of 89% pellets and 11% marketable concentrate, compared to 61% and 39%, respectively, in the first half of 2025, when the higher share of concentrate production provided additional market opportunities during a period of reduced demand for pellets and lower market premiums, Ferrexpo noted.
Interim Chairman of the Board Lucio Genovese recalled that in early September, the company was able to raise $100 million through an additional share issuance, which significantly strengthened its liquidity position and provided additional financial stability and greater flexibility to manage the ongoing operational and financial pressures facing the business.
“However, the additional capital does not resolve the underlying issues arising from the prolonged withholding of VAT refunds, the war in Ukraine, constraints on logistics and energy infrastructure, as well as the need to maintain disciplined cash and working capital management,” he noted.
On Friday Ferrexpo clarified that C1 production costs rose to $81.3 per metric ton from $77.1 in the first half of 2025 due to increased mining and maintenance activities, the impact of higher electricity and fuel prices, and rising personnel costs.
It is noted that the group has made significant efforts to reduce costs in order to maintain financial stability. These measures include reducing employees’ working hours, cutting back on the procurement of goods and services, and suspending all non-critical capital expenditures, overhead costs, and corporate social responsibility expenditures.
In addition, there were no impairment losses in the first half of 2026, whereas in the first half of 2025, they amounted to $154 million.
In the report, Genovese emphasized that the continued suspension of VAT refunds by Ukrainian tax authorities remains a significant financial challenge: as of June 30, the net balance of VAT pending refund stood at $82.7 million, and as of September 24, the State Tax Service had suspended VAT refunds totaling 3.885 billion UAH, or $86.9 million.
The report also notes that during the first six months of 2026, Ferrexpo received news of the deaths of 11 more colleagues who served in the Armed Forces of Ukraine, bringing the total number of fatalities since the start of Russia’s full-scale invasion to 67, whereas in 2024 and 2025, the number of fatalities was 11 each year.
According to the report, as of the end of June 2026, 804 Ferrexpo employees were serving in the Armed Forces of Ukraine, and 218 had been demobilized, whereas at the end of 2025, those figures were 771 and 194, respectively, and a year earlier—706 and 160.
Ferrexpo owns 100% of Yeristovsky GOK LLC, 99.9% of Bilanivsky GOK LLC, and 100% of the shares of Poltava GOK PJSC.
The London Stock Exchange (LSE) suspended trading in Ferrexpo shares in early May due to the company’s inability to publish its annual financial statements on time, but resumed trading on September 7.
In 2025, the company’s revenue fell by 16% to $787 million, its EBITDA dropped 2.5 times to $28 million, and its net loss rose nearly 4.5 times to $223.9 million.
In January–August of this year, Ukraine’s mining companies reduced exports of iron ore raw materials (IORM) by 27.2% in volume terms compared to the same period last year—down to 15,774,950 metric tons from 21,679,221 metric tons.
According to statistics released by the State Customs Service (SCS), 1,865,697 thousand metric tons of iron ore were exported in August, 1,875,428 thousand metric tons in July, 2,021,299 thousand metric tons in June, in May—2,239,167 thousand metric tons of raw materials, in April—2,163,837 thousand metric tons, in March—2,300,467 thousand metric tons, in February – 1,254,516 thousand metric tons, in January – 2,054,539 thousand metric tons.
Over the first eight months of 2026, foreign exchange earnings from mineral ore exports decreased by 26.1% to $1,206,589 million.
In addition, Ukraine imported 235 metric tons of raw materials worth $68,000 in January–August 2026, whereas in January–August 2025, it imported 86,000 metric tons worth $58,000.
As previously reported, Ukraine’s mining companies reduced ore exports in physical terms by 8% in 2025 compared to the previous year—to 30,995,363 metric tons from 33,699,722 metric tons, and foreign exchange earnings decreased by 16.6%—to $2,337,765 million from $2,803,223 million. Exports were primarily destined for China (44.98% of shipments in monetary terms), Slovakia (17.15%), and Poland (16.09%).
In addition, in 2025, Ukraine imported $95,000 worth of raw materials totaling 130 metric tons from the Netherlands (46.32%), Italy (36.84%), and Norway (13.68%), whereas in the previous year it imported 2,042 thousand metric tons worth $414 thousand.
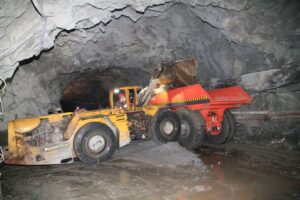
Based on its performance in January–June of this year, the Kryvyi Rih Iron Ore Plant (KZRK) saw its net loss increase by 9.4% compared to the same period last year—to 1 billion 407.383 million UAH.
According to KZRK’s interim report, available to the agency “Interfax-Ukraine,” revenue from ordinary operations during this period fell to 336.132 million UAH from 1 billion 250.939 million UAH.
The uncovered loss as of the end of June 2026 amounted to 876.156 million UAH.
As previously reported, KZRK’s net loss in the first quarter increased 4.4-fold compared to the same period last year—to 378.948 million UAH from 85.925 million UAH. During this period, revenue from ordinary activities decreased to 135.457 million UAH from 705.526 million UAH.
From January through September 2025, KZRK increased its net loss by 3.2 times compared to the same period in 2024—to 1,487.217 million UAH; net income for this period decreased by 41.6%—to 1,601.822 million UAH.
The annual report for 2025 has not yet been published.
KZRK ended 2024 with a net loss of 2 billion 14.015 million UAH, whereas in 2023 it amounted to 63.411 million UAH. Net revenue in 2024 amounted to 3 billion 443.081 million UAH, compared to 5 billion 577.923 million UAH in 2023.
It was previously reported that on May 23, 2025, “Your Energy Supplier” LLC (Kyiv) filed a petition with the Commercial Court of Dnipropetrovsk Oblast to initiate bankruptcy proceedings against KZRK due to outstanding payments for electricity consumed. The Commercial Court of Dnipropetrovsk Oblast ruled to open bankruptcy proceedings against KZRK on June 9 of this year.
KZRK specializes in underground iron ore mining. It comprises four mines: “Pokrovska” (formerly “Zhovtneva”), the “Kryvyi Rih” mine (“Batkivshchyna”), “Kozatska” (formerly “Hvardiyiska”), and “Ternivska” (formerly the Ordzhonikidze Ore Administration, later the Lenin Ore Administration).
According to data from the National Securities and Stock Market Commission for the first quarter of 2026, the main shareholder of KZRK is Starmill Limited (Cyprus), which owns 99.8812% of its shares. Operational control of the combine was exercised by the “Privat” Group prior to the initiation of bankruptcy proceedings.
In May 2023, Ukraine imposed sanctions against dozens of foreign companies linked to Russian individuals that own significant assets in Ukraine, including KZRK. Some of these assets had already been seized, but the sanctions paved the way for their confiscation. The corresponding Presidential Decree No. 279 of May 12 was published on the President’s website. In particular, the list of legal entities includes Starmill Limited, which owns 99.89% of KZRK under the operational control of the Privat Group.
The company’s authorized capital is 1 billion 991.233 million UAH.



