
In September 2026, Ukrainian citizens purchased 158 residential properties in Turkey, a 7.5% increase from August; however, they dropped from second to fifth place among foreign buyers. Russians retained their lead, increasing the number of purchases over the year by 45.3% to 388 properties, according to data from the Turkish Statistical Institute (TÜİK) published on October 16.
In September, Russian citizens purchased 388 apartments and houses, compared to 343 in August and 267 in September of last year. Thus, the number of transactions rose by 13.1% over the month and by 45.3% year-over-year. Russian buyers accounted for approximately 17.9% of all residential property sales to foreigners.
Iraqi citizens ranked second among foreign buyers with 166 properties purchased, followed by Germany in third place with 162. Next came Iran with 159 properties and Ukraine with 158. China ranked sixth, with its citizens purchasing 124 properties.
Despite dropping in the rankings, Ukrainian buyers have increased the number of transactions for the third consecutive month. In July, they purchased 145 properties; in August, 147; and in September, 158. The share of Ukrainians among all foreign homebuyers in Turkey in September was 7.3%, down from 7.6% in August.
A total of 2,167 residential properties were sold to foreign citizens in September, which is 9.9% more than during the same period last year. Compared to August, when foreigners purchased 1,938 properties, this represents an 11.8% increase.
However, over the first nine months of 2026, the number of apartments and houses purchased by foreigners decreased by 4.3% compared to the same period in 2025, totaling 15,308 properties. Foreign buyers accounted for 1.5% of the total number of transactions in September.
The domestic Turkish real estate market continues to decline. In September, 142,390 residential properties were sold in the country, which is 9.3% less than a year earlier. Sales of new homes rose by 3.9% to 51,519 units, while the number of transactions in the resale market fell by 15.3% to 90,871.
From January through September, total housing sales in Turkey amounted to 1.093 million units, a 7.2% decrease compared to last year.
Ukrainians remain one of the largest groups of foreign buyers of Turkish real estate. By the end of 2025, Ukrainian citizens had purchased 1,541 residential properties, ranking third behind Russians, who bought 3,649 properties, and Iranians, with 1,878 purchases. In 2024, Ukrainians purchased 1,631 properties.
As previously reported by Open4Business, in August 2026, approximately 78% of all residential property purchases by Ukrainian citizens in Turkey took place in the province of Antalya. There, Ukrainians purchased 114 out of 147 properties, while Russians purchased 226. Overall, Istanbul, Antalya, and Mersin remained the largest hubs for foreign purchases in August.
According to the international real estate agency Homium, the average budget for a Ukrainian buyer of real estate in Turkey in 2025–2026 is $100,000–$200,000. The main interest is focused on Antalya, Alanya, Istanbul, and other cities along the Mediterranean coast.
Thus, the September statistics indicate a revival in foreign demand for Turkish real estate against the backdrop of an overall contraction in the domestic market.
South Korea has decided to recall some of the staff at its embassy in Ukraine amid a diplomatic conflict over the handover of two North Korean prisoners of war to Seoul. The reasons for this decision, according to the South Korean side, were Kyiv’s failure to provide a constructive response to Seoul’s demands, as well as the intensification of Russian airstrikes on Ukrainian territory, said Park Doo-soon, a spokesperson for the Ministry of Foreign Affairs of the Republic of Korea, on October 20, 2026.
According to the South Korean news agency Yonhap, the decision was made several weeks after Seoul recalled its ambassador to Ukraine, Park Ki-chan, in protest against the public disclosure of information regarding the transfer of the two DPRK servicemen.
“We have communicated our position to Ukraine through various channels. However, despite these efforts, Ukraine has not taken any positive steps,” stated the South Korean Foreign Ministry spokesperson.
According to him, the decision to reduce diplomatic staff is aimed at facilitating the resolution of differences and restoring trust between the two countries.
At the same time, South Korea does not intend to close its embassy in Kyiv or sever diplomatic relations with Ukraine. The chargé d’affaires and all consular staff will remain in the country to continue maintaining contact with Ukrainian authorities and ensuring the protection of South Korean citizens.
The exact number of diplomats being recalled has not been officially disclosed. However, according to Yonhap, citing South Korean officials, about half of the diplomatic mission’s staff may leave Ukraine.
The dangerous situation in Ukraine has been cited as an additional reason for this decision. The South Korean Ministry of Foreign Affairs noted that ongoing Russian missile and drone attacks are making it difficult to ensure the safety of embassy staff.
Currently, there are about 85 citizens of the Republic of Korea in Ukraine. Diplomatic staff are to assist those who wish to evacuate to neighboring countries. South Korean authorities maintain the highest, fourth-level travel warning for the entire territory of Ukraine.
A diplomatic conflict between Kyiv and Seoul arose following Ukrainian President Volodymyr Zelenskyy’s address to the UN General Assembly on September 23, 2026, when he publicly announced the handover to South Korea of two North Korean soldiers who had been taken prisoner by Ukraine.
Both North Korean soldiers were captured by Ukrainian forces in January 2025 during combat operations against Russian forces in the Kursk region. According to South Korean authorities, they arrived in the Republic of Korea in mid-September 2026.
Seoul asserts that there was an agreement between the two countries regarding the confidentiality of the prisoners’ transfer, which was necessary to ensure the safety of the soldiers themselves and their relatives who remain in North Korea.
Following the Ukrainian president’s public statement, the South Korean government demanded official explanations, an apology, and guarantees that such situations would not occur in the future.
At the same time, the Ukrainian side disputes Seoul’s interpretation of the agreements reached. Ukrainian Foreign Minister Andriy Sibiga previously stated that Kyiv had fulfilled all its obligations, and that the disagreements stem from differing interpretations of the confidentiality terms.
According to Reuters, the Ukrainian minister said last week that he considers the matter closed. Meanwhile, the South Korean Foreign Ministry stated that the explanations received from Kyiv did not satisfy Seoul.
South Korean Foreign Minister Cho Hyun previously confirmed receiving a personal message from Sibiga containing an apology, but noted that it did not meet the South Korean side’s expectations.
Despite the differences, both countries maintain diplomatic ties. Seoul emphasizes that it hopes to resolve the conflict through further consultations.
South Korea is one of Ukraine’s Asian partners and provides it with humanitarian aid, participates in international support programs, and discusses post-war reconstruction projects. In June 2026, the foreign ministers of both countries agreed to seek a solution to the issue of North Korean prisoners of war, taking into account their voluntary choice, international law, and humanitarian principles.
Sources: Yonhap, South Korean Foreign Ministry statement dated October 20, 2026
DIPLOMACY, North Korea, prisoner of war, SOUTH KOREA, UKRAINE
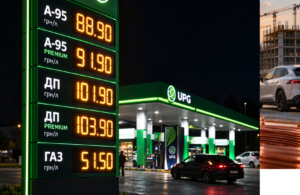
Prices for both types of diesel fuel, as well as autogas, continue to rise, according to monitoring of a number of filling station chains conducted since February 2026 by the Energoreforma internet portal.
According to the monitoring data, as of October 20, compared with October 16, the price of diesel fuel and diesel fuel+ increased by UAH 1–3 per liter, while autogas rose in price by UAH 1.6–3.5 per liter. At the same time, the price of regular diesel at state-owned UKRNAFTA reached UAH 99.9 per liter.
Gasoline prices have remained largely stable for several weeks.
Fuel prices (average) as of 10:00 a.m. on October 20 compared with October 16 (based on Energoreforma’s monitoring of filling station chains’ websites and applications)
| Chain | 95 (UAH/l) | Premium 95 (UAH/l) | Diesel fuel (UAH/l) | Premium diesel fuel (UAH/l) | Gas (UAH/l) |
|---|---|---|---|---|---|
| UKRNAFTA | 88.90 (88.90) | 91.90 (91.90) | 99.90 (98.90) | 101.90 (100.90) | 49.90 (47.90) |
| UPG | 88.90 (88.90) | 91.90 (91.90) | 101.90 (99.90) | 103.90 (101.90) | 51.50 (49.90) |
| OKKO | 92.90 (92.90) | 95.90 (95.90) | 104.90 (101.90) | 107.90 (104.90) | 51.90 (49.90) |
| WOG | 92.90 (92.90) | 95.90 (95.90) | 104.50 (102.50) | 107.50 (105.50) | 52.50 (50.50) |
| SOCAR | 94.90 (94.90) | 97.90 (97.90) | 105.00 (105.00) | 108.00 (106.00) | 54.40 (50.90) |
As reported, on September 21, SOCAR was the first filling station chain to “release” the price of diesel fuel, raising it to UAH 103 per liter and UAH 104 per liter for regular diesel and diesel+, respectively.
On September 25, WOG and OKKO raised the price of premium diesel above UAH 100 per liter, from UAH 99.9 per liter to UAH 102.9 per liter, while the price of regular diesel fuel remained at UAH 99.9 per liter.
Dmytro Leushkin, founder and CEO of Prime Group, explained at the time that diesel fuel prices should already have exceeded UAH 100 per liter several days earlier, but there was an unofficial request from the government to restrain them.
On October 15, a number of filling station chains exceeded the UAH 100 per liter mark for regular diesel fuel, whose price had long been kept at UAH 99.9 per liter. A distinctive feature of that day was that the state-owned UKRNAFTA chain, which serves as a kind of “price restraint mechanism,” set the price of diesel fuel+ at UAH 100.9 per liter.
At the same time, autogas became more expensive again at almost all the chains monitored, increasing by between UAH 0.6 and UAH 2 per liter.
Several days earlier, Serhiy Kuyun, director of the A-95 consulting group, had forecast that autogas prices would rise by approximately 10% over the following 7–10 days due to an increase in global prices.
At that time, he also drew attention to the rise in diesel fuel quotations on London’s ICE exchange to $1,483 per tonne (an increase of more than $100 per tonne), noting that such a jump had dashed hopes of stabilizing prices for this type of fuel.
Kuyun also emphasized that retail prices for regular diesel at filling station chains were lower than wholesale prices, which, in particular, stood at UAH 101 per liter in the central part of the country. According to him, at such wholesale prices, the price at the pump should be at least UAH 105–106 per liter. At the same time, he pointed out that there was no fuel shortage in Ukraine.
autogas, DIESEL FUEL, FILLING STATIONS, FUEL, FUEL PRICES, UKRAINE
On October 20, Hungary blocked the next stage of the negotiation process regarding Ukraine and Moldova’s accession to the European Union by refusing to approve the results of the preliminary review of legislation for the last two outstanding negotiation clusters. Budapest’s position was not supported by the remaining 26 EU countries, according to “European Truth,” citing European diplomats.
The decision was discussed at a meeting of the EU Council’s Working Group on Enlargement (COELA) in Brussels. The participants had planned to approve the results of the screening of Ukrainian and Moldovan legislation regarding negotiation clusters No. 4 and No. 5, which is a necessary procedural step before their official opening.
However, the Hungarian representative refused to support the approval of the documents, despite the position of the other EU member states.
As three European diplomats told The Kyiv Independent, representatives from other countries asked the Hungarian delegation to explain the reasons for the refusal. According to one of the publication’s sources, Budapest did not provide any new arguments, stating only that its position remains unchanged.
At the time of publication, Hungary’s official mission to the EU had not provided the publication with a comment.
The fourth negotiation cluster, “Green Agenda and Sustainable Interconnectivity,” covers transportation policy, energy, trans-European networks, environmental legislation, and the fight against climate change.
The fifth cluster, “Resources, Agriculture, and Cohesion Policy,” involves harmonizing regulations in the areas of agricultural policy, food security, veterinary and phytosanitary controls, fisheries, regional development, as well as financial and budgetary provisions.
Both clusters are of significant importance for Ukraine’s economic integration into the EU, as they concern access for agricultural products to the European market, transportation, energy infrastructure, and future mechanisms for the distribution of European budget funds.
This new impasse occurred one week after the previous progress in the negotiation process.
On October 13, the Council of the EU officially opened two negotiation clusters for Ukraine and Moldova: No. 2, “Internal Market,” and No. 3, “Competitiveness and Inclusive Growth.” These clusters encompass 17 negotiation chapters, including issues related to competition, entrepreneurship, and economic regulation.
As reported by the Council of the EU, at that time, four of the six clusters provided for in the accession procedure had been opened for both countries.
The previous decision became possible after Hungary withdrew its objections to the opening of the second and third clusters following the Verkhovna Rada’s adoption on October 12 of amendments to education legislation concerning the rights of national minorities.
Previously, Budapest had linked the progress of negotiations to ensuring the linguistic and educational rights of the Hungarian community in Zakarpattia.
According to The Kyiv Independent, the current delay may prove to be temporary. European diplomats expect that the remaining two negotiation clusters will be officially opened in December 2026.
Ireland, which will hold the EU Council presidency in the second half of 2026, intends to continue discussing this issue at upcoming meetings of the Enlargement Working Group.
However, Hungary’s October decision does not cancel the negotiation clusters that have already been opened and does not mean the end of accession negotiations for Ukraine and Moldova. It does, however, delay the necessary harmonization of documents required for both countries to move forward.
Ukraine and Moldova were granted EU candidate status in June 2022. In December 2023, the European Council decided to open negotiations, and the first intergovernmental conference took place in June 2024.
The accession process involves aligning national legislation with EU law, implementing institutional reforms, and negotiating 35 chapters, most of which are grouped into six thematic clusters. The opening of all clusters marks a stage in the negotiations but does not in itself signify the completion of the accession process.
EUROPEAN INTEGRATION, EUROPEAN UNION, HUNGARY, MOLDOVA, UKRAINE
Net inflows from non-residents for real estate purchases in Egypt for the 2025/2026 fiscal year, which ended on June 30, increased by 47.4% compared to the previous fiscal year—rising from $1.9 billion to $2.8 billion. This is according to data from the Central Bank of Egypt (CBE) published on October 12, 2026.
Thus, revenues increased by approximately $900 million over the course of the year. This positive trend is driven by growing international demand for Egyptian real estate, the development of major construction projects, and government initiatives aimed at attracting foreign capital.
However, the Central Bank’s statistics include real estate purchases by all non-residents, including foreign nationals and Egyptians permanently residing abroad. Therefore, the $2.8 billion figure cannot be attributed entirely to foreign nationals.
The growth in real estate investment has become part of an overall increase in the inflow of foreign capital into Egypt’s economy. According to Central Bank data, the net inflow of foreign direct investment in the 2025/2026 fiscal year reached approximately $18 billion, compared to $12.2 billion a year earlier.
In particular, investments in the establishment of new enterprises and capital increases for existing companies rose to $8.8 billion from $5.5 billion. Reinvested earnings increased from $4.2 billion to $6.2 billion, while net proceeds from the sale of companies and production assets to non-residents totaled $433.2 million, compared to $399.8 million a year earlier.
Large-scale real estate development projects along the Mediterranean coast, in New Cairo, and in Egypt’s new administrative capital play a significant role in attracting investment.
In May 2026, Egypt’s Ministry of Justice finalized a draft law regulating the purchase of completed real estate and undeveloped land plots by foreign nationals. Its goal is to simplify property registration procedures and make the market more accessible to foreign investors.
The government is also developing digital mechanisms for real estate purchases by foreigners, which involve processing transactions and transferring funds through Egypt’s banking system.
Against the backdrop of growing foreign demand, the authorities are paying increasing attention to the transparency of development projects, property registration, and the protection of buyers’ interests.
Unlike Turkey, where the statistics agency publishes monthly data on the number of transactions with foreigners broken down by citizenship, Egypt does not provide a comparable nationwide ranking of real estate buyers that is publicly available.
Therefore, the structure of foreign demand must be assessed based on studies by consulting firms, reports from Egyptian developers, and regional real estate agencies.
One of the largest groups of buyers consists of citizens of Gulf states, primarily Saudi Arabia, Qatar, the UAE, and Kuwait.
According to an assessment by Basem Kalila, CEO of Kalila—the company that organizes the international Nile Property Expo—published by the Egyptian publication Osoul Misr on October 1, 2026, the most active foreign buyers of Egyptian real estate are citizens of Saudi Arabia and Qatar.
Saudi buyers are showing particular interest in real estate in Egypt’s new administrative capital. Qatari citizens are primarily considering projects on the northern coast of the Mediterranean Sea, while investors from other Gulf states are actively interested in the western districts of Cairo.
It should be noted that this is a market participant’s assessment, not an official statistical ranking based on the number of registered transactions.
The second largest category of buyers consists of Europeans and citizens of former Soviet Union countries, who traditionally purchase real estate in Red Sea resorts.
According to a September 19, 2025, article in the Egyptian newspaper Al-Masry Al-Youm, representatives of the local real estate development industry cited citizens of Russia, Germany, the United Kingdom, and Italy as among the most active foreign buyers in Hurghada.
Buyers from Poland, the Netherlands, the Czech Republic, and other European countries are also showing significant interest in resort housing.
Unlike investors from the Persian Gulf, who tend to focus on large residential complexes and high-end real estate in the capital region and along the Mediterranean coast, European buyers primarily consider apartments for vacation use, long-term residence, and subsequent rental.
The main centers of this demand remain Hurghada, El Gouna, Sahl Hasheesh, and other Red Sea resort areas. Sharm el-Sheikh holds a special place, as it has specific rules governing the registration of property rights for foreigners.
Ukrainian citizens are also among the foreign buyers of Egyptian real estate, primarily in the Red Sea resorts. According to a study by Experts Club and the Relocation.com.ua project, published on September 14, 2025, Ukrainians are among the most prominent groups of buyers of resort properties in Egypt, especially in Hurghada.
According to market participants, Ukrainian citizens began actively purchasing real estate in Egyptian resorts as early as the 2010s, and after the outbreak of full-scale war in 2022, some buyers began to view Egypt not only as a tourist destination but also as a place for long-term residence.
Ukrainians are most interested in relatively affordable apartments ranging from 40 to 70 square meters, which are purchased for personal use, seasonal vacations, or rental purposes.
A study by Experts Club noted that Ukrainian buyers are primarily concentrated in the affordable price segment, while wealthier investors are looking at properties priced at $300,000 and above, particularly due to the opportunity to participate in Egypt’s investment migration programs.
However, the country’s Central Bank has not published official data on the number of properties purchased by Ukrainian citizens in Egypt during the 2025/2026 fiscal year. Consequently, it is not yet possible to determine the exact share of Ukrainians in the total volume of non-resident investments or their current standing among foreign buyers.
The program for obtaining Egyptian citizenship through investment provides, in particular, for the purchase of real estate valued at no less than $300,000, subject to compliance with the conditions set by the state. This program is designed for a specific category of investors and does not reflect the typical budget of buyers of resort apartments.
Egyptian authorities view international real estate sales as one of the tools for attracting foreign currency, increasing investment, and developing the construction sector. One of the largest markets remains the northern coast of the Mediterranean Sea, where large-scale projects involving Arab capital are being implemented.
Denmark continues to rank among the countries with the highest level of positive perception among Ukrainians: in August 2026, 66.9% of respondents viewed it positively, while only 1.8% viewed it negatively. Compared to March, the share of positive assessments has decreased slightly, but the overall attitude remains distinctly favorable, according to the Experts Club Information and Analytical Center.
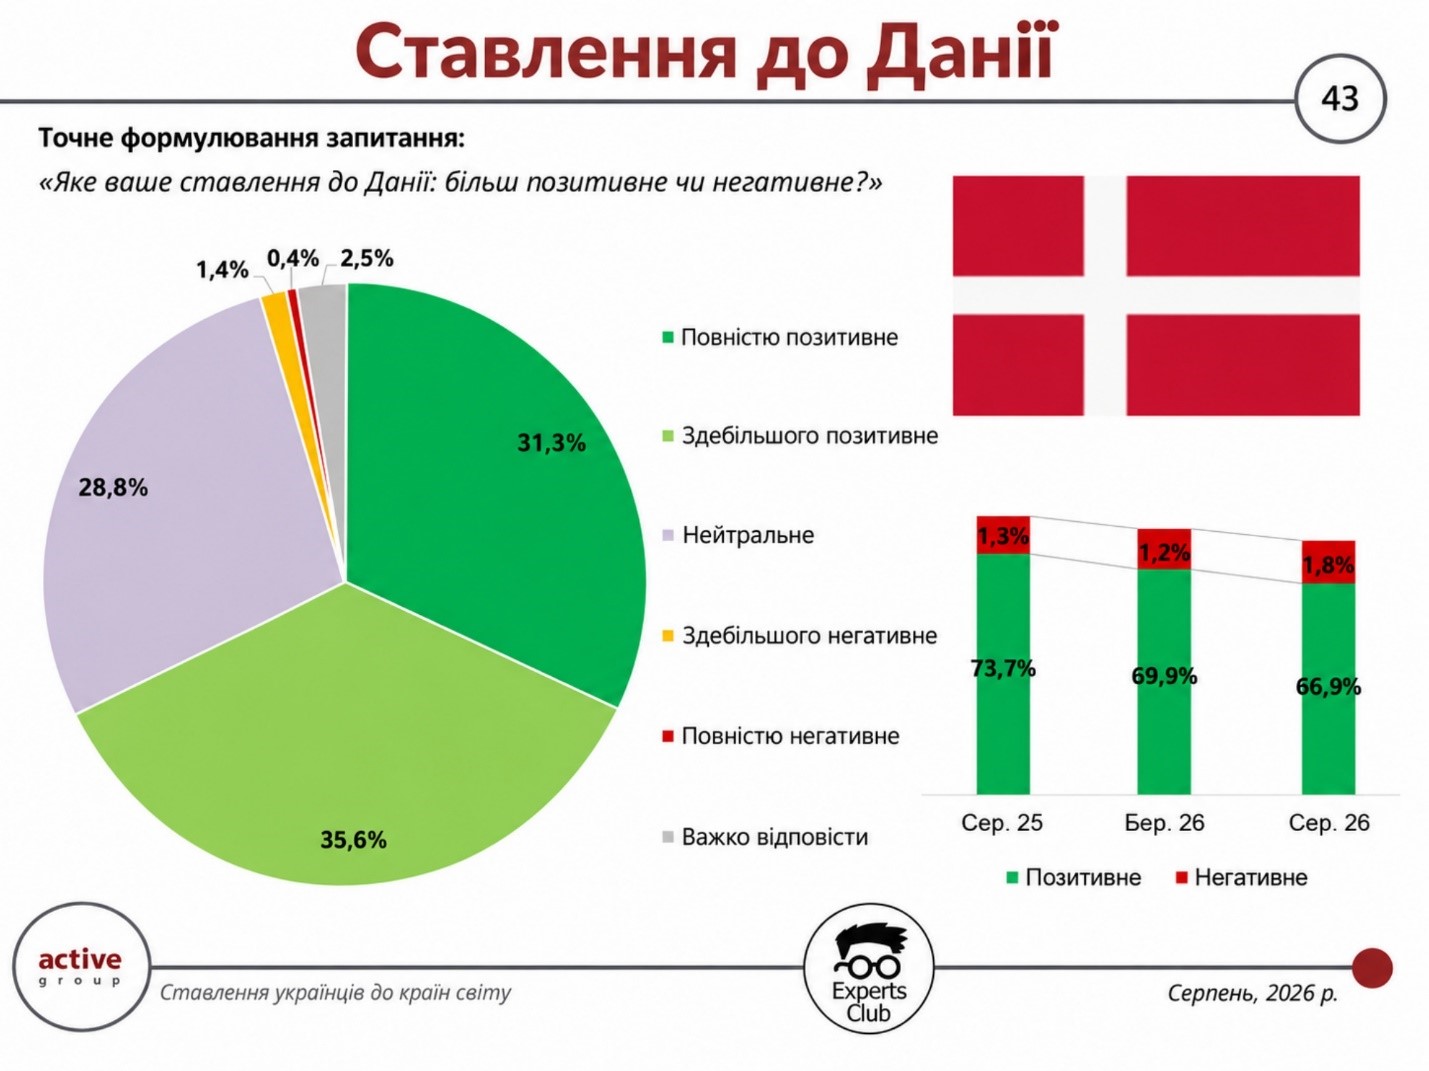
According to the results of the August survey, 31.3% of Ukrainians have a completely positive attitude toward Denmark, and 35.6% have a mostly positive attitude. A neutral stance is held by 28.8% of respondents. Only 1.4% expressed a mostly negative attitude, 0.4% a completely negative one, and another 2.5% were undecided.
The balance of positive and negative assessments stands at plus 65.1 percentage points. Thus, positive responses outnumber negative ones by more than 37 times. Denmark remains among the group of Northern European countries that enjoy very high public favor among Ukrainians.
In March 2026, 69.9% of respondents viewed Denmark positively: 33.3% viewed it entirely positively and 36.6% viewed it mostly positively. A neutral attitude was expressed by 26.8% of respondents, a negative one by only 1.2%, and another 2.1% were undecided.
Thus, over the course of five months, the share of positive assessments decreased by 3 percentage points—from 69.9% to 66.9%. The neutral segment increased by 2 percentage points—to 28.8%—while negative attitudes rose by only 0.6 percentage points. The balance of positive and negative assessments decreased from +68.7 to +65.1 percentage points, respectively.
There has also been a noticeable and definite decline in the intensity of positive attitudes: the share of fully positive responses fell from 33.3% to 31.3%, and that of mostly positive responses—from 36.6% to 35.6%. At the same time, the increase in the negative segment remains minimal, so the current trend suggests that some respondents are shifting to a neutral position rather than developing a critical attitude toward Denmark.
Oleksandr Pozniy, director of the research firm Active Group, commenting on Denmark’s high ratings in previous waves of the survey, noted: “Ukrainians perceive Denmark as a sincere partner and a reliable ally under the current circumstances. The high level of trust reflects both the humanitarian aid and Copenhagen’s consistent political support for Ukraine.” In the broader context of the survey, he also emphasized: “Ukrainians clearly associate the support received primarily from European Union countries and the United Kingdom with a positive attitude toward them.”
The latest wave of the survey shows that this positive image persists. Despite a decline in the figure compared to March, approximately two-thirds of Ukrainians continue to view Denmark positively, while the share of negative responses does not even reach 2%.
The previous wave of the survey was conducted in March 2026 among 800 Ukrainian citizens aged 18 and older using self-administered online questionnaires on the SunFlowerSociology panel. The sample was representative by age, gender, and region; the maximum theoretical margin of error for indicators at the 50% confidence level was ±3.5 percentage points.
ACTIVE GROUP, DENMARK, EUROPEAN UNION, EXPERTS CLUB, international relations, NORTHERN EUROPE, PUBLIC OPINION, SOCIOLOGY, UKRAINE



