
According to Interfax-Ukraine, Valery Kirilko, CEO of the “Industrial Parks of Ukraine” group of companies, believes that one solution for changing Ukraine’s warehouse logistics model—given the enemy’s destruction of warehouse and logistics infrastructure—is to create a decentralized network of small warehouses, particularly within industrial parks.
“The war has shown just how vulnerable large distribution centers are. Therefore, we may need to partially move away from concentrating large volumes of goods in a single location and transition to a decentralized network of small warehouses,” –he wrote on Facebook.
According to his proposal, this could mean replacing a single large warehouse spanning tens of thousands of square meters with many smaller ones—ranging from 1,000 to 5,000 square meters—located in different regions and logistically convenient locations.
“That is precisely why we are currently developing the ‘HELP.Warehouse’ program. We are creating several standard designs for small warehouse complexes that can be quickly adapted to a specific plot of land and implemented simultaneously in different regions of Ukraine,” Kirilko noted.
He emphasized that the company is ready to take on the design of standard warehouse facilities, the search for and acquisition of land plots, matters related to utilities and infrastructure, the selection of construction contractors, the organization of construction, and the coordination of project implementation.
“With proper organization, such facilities can be built in approximately 3–5 months. And today, there is another important factor at play—the Ukrainian construction market is going through a challenging period. But that is precisely why many construction companies are willing to work with minimal profit margins, quickly assemble teams, and carry out projects at competitive costs,” he believes.
Kyrylko added that industrial park sites across Ukraine are being considered separately.
“Some of them are already prepared to provide land plots for such projects on preferential or even free terms during the initial period. We can begin restoring warehouse and logistics infrastructure right now,” he notes.
Kirilko invited those who are able to finance such projects—including those who own a land plot that can be leased free of charge for a year, industrial parks that can provide a small plot free of charge for a year, and construction companies acting as investors—to join the initiative.
The company “Industrial Parks of Ukraine” has been active in the development of industrial parks since 2019. According to its data, nearly one in three industrial parks established or registered in Ukraine is or has been supported by the company’s specialists.
According to information on its website, the company manages seven industrial parks, has developed 56 industrial park concepts, and has facilitated the registration of 37 industrial parks.
INDUSTRIAL PARK, INFRASTRUCTURE, LOGISTICS, UKRAINE, WAREHOUSE
According to “Serbian Economist”, Ukraine ranked sixth among Montenegro’s foreign tourism markets in July 2026 in terms of the number of overnight stays in collective accommodation facilities, as evidenced by new MONSTAT data published on August 27.
Ukrainian tourists spent 43,400 nights in hotels, tourist complexes, hostels, and other collective accommodations. In total, approximately 7,350 tourists from Ukraine stayed at such accommodations during the month.
Serbia, Bosnia and Herzegovina, Poland, the United Kingdom, and Russia ranked ahead of Ukraine in terms of the number of overnight stays. Ukrainians accounted for about 4.4% of all overnight stays by foreign guests.
At the same time, the flow of tourists from Ukraine remains fairly stable. The number of tourists from Ukraine has remained virtually unchanged compared to July of last year, while the number of overnight stays decreased by approximately 3%.
Serbia remains the leader in Montenegro’s tourism market, accounting for about a quarter of all foreign overnight stays. At the same time, the influx of Russian tourists rose sharply in July: the number of overnight stays by Russians increased by more than 60% year-over-year.
In total, 244,800 tourists and 1.08 million overnight stays were registered in Montenegro’s collective accommodation establishments in July. Foreigners accounted for over 90% of overnight stays.
However, the actual role of Ukrainians in Montenegro’s tourism sector is greater than what the July hotel statistics indicate. MONSTAT does not include private apartments and vacation rentals—which Ukrainian tourists actively use—in this monthly report. As of 2025, Ukraine accounted for 4.7% of foreign overnight stays in Montenegro’s private sector.
Ukrainian small and medium-sized businesses are increasingly seeking customers, investors, and partners abroad. However, for many small companies, the main problem is not the quality of their product but their low international visibility: a foreign partner simply does not have enough data to quickly identify and assess the company.
In international trade, a corporate presence consists of more than just a website and social media pages. Large companies and banks use professional business databases to verify legal information, addresses, management, industries, the scale of operations, corporate connections, and other information.
“For small businesses, the problem often sounds like this: ‘We are a real company, but no one abroad knows anything about us.’ That is why international business identification is important not only for large corporations. It helps a small Ukrainian company become understandable to a procurement professional, bank, or potential partner in another country,” Maksym Urakin noted.
SMEs should monitor the consistency of their legal and commercial information, maintain a consistent English-language spelling of their name, provide up-to-date contact details, and have a clear description of their activities. It is also important for a company planning to export to understand how it is classified in international systems and whether it can be easily found using industry-specific parameters.
D&B’s international data can be used not only to verify other companies but also to create and update a company’s own business profile. This is particularly relevant for companies seeking to connect to global procurement platforms or work with corporate clients.
Greater visibility does not guarantee a contract, but it reduces the information barrier between Ukrainian SMEs and foreign markets. In many cases, the speed at which a company can be verified determines whether a potential partner will proceed to the next stage of negotiations.
D&B — Interfax-Ukraine helps Ukrainian companies work with international business data and business identification tools.
Dun & Bradstreet is an international provider of business data and analytical solutions whose history began in 1841. D&B works with data on companies worldwide and provides tools for business identification, counterparty verification, credit and commercial risk assessment, compliance, and supply chain management.
The Interfax-Ukraine News Agency is the official representative of Dun & Bradstreet in Ukraine. The specialized D&B — Interfax-Ukraine division provides Ukrainian companies with access to international business data, helps them verify foreign counterparties, and assists them in working with D&B tools.
Questions can be submitted through the specialized D&B resource — dnb.ua, by email at Urakin@interfax.kyiv.ua, or by telephone at +38 (044) 270-65-74.
The housing crisis in Spain continues to deepen amid a long-standing shortage of new construction, a rise in the number of households, and a record increase in population—a significant portion of which is due to migration. The structural housing shortage in the country is estimated at approximately 700,000–750,000 units, according to data from the Funcas analytical center.
The current situation should not be compared to the housing bubble of the 2000s. At that time, significantly more housing was being built in Spain, and market growth was fueled by lending. Now the problem is the opposite—supply consistently lags behind demand.
In recent years, approximately 100,000 new homes have been completed annually in Spain, while about 230,000 new households have been formed. The gap that has accumulated since 2020 has reached nearly 700,000 units.
As a result, both home purchase prices and rental rates are rising. The problem is particularly acute in Madrid, Barcelona, the Balearic Islands, Valencia, and popular coastal areas. At the same time, the shortage is gradually spreading from the largest cities to their suburbs and medium-sized cities. Funcas notes that rents have been rising faster than wages in recent years, and young renters spend an average of about 35% of their budget on housing and utilities.
Experts believe that some of the measures taken by the authorities can only temporarily curb prices but cannot eliminate the root cause of the crisis. Rent controls may lower housing costs for some current tenants, but at the same time reduce the number of apartments that landlords are willing to put on the market. Subsidies for buyers, given limited supply, may also lead to further price increases.
Among the long-term solutions, Funcas cites increasing the supply of land parcels, expediting the issuance of building permits, enhancing legal certainty for developers and property owners, and expanding the stock of affordable rental housing. Social rental housing in Spain accounts for only about 2–3% of the housing stock, which is significantly below the EU average.
Spain’s rapid population growth is placing additional pressure on the market. As of July 1, 2026, the country’s population stood at a record 49.80 million, an increase of 444,200 from the previous year. At the same time, Spain’s National Institute of Statistics (INE) explicitly states that the population increase is driven by people born abroad, while the number of residents born in Spain is declining.
The number of residents in Spain born abroad reached 10.29 million by mid-year, accounting for more than one-fifth of the country’s population. The number of residents with foreign citizenship stood at 7.44 million, having increased by 87,200 in the second quarter alone.
According to the latest comprehensive breakdown from the INE, the largest foreign communities consist of citizens of Morocco—about 969,000,
Colombia—677,000, Romania—609,000, Venezuela—378,000, Italy—346,000, and the United Kingdom—266,000. There are also significant communities of people from Peru, China, Ukraine, and Latin American countries.
The influx continues in 2026. In the second quarter alone, approximately 34,000 Colombian citizens, 23,300 Venezuelans, and 21,100 Moroccans arrived in Spain. In the first quarter, Ukrainians were among the largest groups of new arrivals—about 25,700 people.
Separate statistics from Spain’s Ministry of Migration show that as of the end of June 2026, 353,000 Ukrainian citizens already held valid residence permits, mainly thanks to the temporary protection mechanism.
The growth of the foreign population cannot be considered the sole cause of the housing crisis; experts attribute it primarily to a decade of insufficient construction. However, migration significantly increases the number of households and the demand for rentals, especially in large cities and economically active coastal regions. Given the construction of approximately 100,000 units per year, the additional population growth of hundreds of thousands of people becomes a significant factor in the further rise in housing costs.
Thus, the housing crisis in Spain is driven by several factors: a chronic shortage of new construction, an increase in the number of households, a limited supply of affordable rental housing, internal migration to major cities, foreign buyers, and the tourism sector. Rapid population growth due to immigration exacerbates the existing shortage, but is not its root cause.
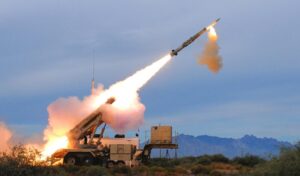
Stocks of Patriot interceptor missiles held by U.S. forces in Europe have plummeted following large-scale deliveries to Ukraine and particularly heavy ammunition consumption during the war with Iran, raising concerns about NATO’s ability to repel sustained ballistic missile attacks.
The Associated Press reported this on August 27, citing a U.S. military official in Europe and a NATO spokesperson, both of whom spoke on condition of anonymity.
According to the U.S. official, the most serious problem concerns the Patriot missiles specifically designed to intercept high-speed ballistic missiles.
He described inventory levels as “below critical” and stated that U.S. forces in Europe currently “definitely” do not have enough interceptors to repel a sustained series of ballistic missile strikes.
The official described the ability to defend against even a single ballistic strike or an errant Russian missile that has veered off course and is heading toward NATO territory as “very limited.”
A NATO spokesperson who spoke with the AP also confirmed the low level of Patriot stockpiles among U.S. and NATO forces in Europe.
However, both the Pentagon and NATO officially reject assessments of a critical shortage.
NATO’s senior military representative, U.S. Army Colonel Martin O’Donnell, told the AP that the claim that the number of Patriot missiles in Europe is “below critical levels” is not true. According to him, NATO has sufficient air defense capabilities both for its own protection and to continue assisting Ukraine.
Pentagon spokesperson Sean Parnell also dismissed reports of a shortage of U.S. ammunition as false and stated that the U.S. military has the necessary stockpiles to conduct operations.
Nevertheless, independent assessments show a significant reduction in U.S. reserves.
According to Mark Kansian, a senior advisor at the Center for Strategic and International Studies (CSIS), Ukraine has received more than 600 Patriot missiles from U.S. and allied stocks since the start of the full-scale war.
However, the main factor behind the sharp decline in reserves was the U.S. war with Iran.
According to CSIS estimates, approximately 65% of U.S. Patriot stockpiles—roughly 1,500 out of 2,330 interceptors—were expended during the campaign against Iran. By the end of July, CSIS analysts estimated that the remaining U.S. Patriot stockpiles stood at fewer than 1,000 missiles.
Ed Arnold, an expert at the British Royal United Services Institute, noted that deliveries to Ukraine had been planned in advance and were relatively manageable, whereas the need for massive deployment of interceptors in the Middle East arose much sooner than expected, exposing the limitations of the production chain.
The shortage is particularly acute for Europe, as there are currently few alternatives to the Patriot system for intercepting modern ballistic missiles.
France and Italy are developing a new version of the SAMP/T NG system, which is expected to have broader capabilities against ballistic targets; however, this new variant has not yet been tested in actual combat conditions. The current version of the SAMP/T has a shorter range than the Patriot.
A sharp increase in production capacity should partially resolve the problem.
In 2026, approximately 600–650 modern PAC-3 MSE missiles are expected to be produced, and the U.S. defense industry plans to increase production capacity to 2,000 interceptors per year by 2030. Lockheed Martin and the Pentagon have already signed agreements designed to significantly expand production.
Additional production capacity is being established directly in Europe.
In September 2026, the first European production center for Patriot missiles is scheduled to launch in Schrobenhausen, Germany. The facility is being established by COMLOG, a joint venture between MBDA Deutschland and the American company Raytheon.
The new facility will carry out final assembly and testing of PAC-2 GEM-T missiles. The first deliveries are expected in 2027. Among the countries that have already placed orders, AP lists Germany, the Netherlands, Romania, and Spain.
Raytheon received a separate $3.7 billion contract in April 2026 to produce GEM-T missiles for Ukraine. The company explicitly stated that the new plant in Germany is also expected to play a key role in replenishing Ukraine’s stockpile of interceptors.
For Ukraine, this situation means increased competition for the limited supply of missiles being produced. Kyiv needs the Patriot system primarily to intercept Russian ballistic missiles, which remain one of the most challenging targets for Ukraine’s air defense.
At the same time, U.S. manufacturers must replenish their own stockpiles, meet the needs of European NATO members, fulfill orders from Middle Eastern countries, and continue to support Ukraine.
CSIS warns that even with a significant ramp-up in production, it will take several years to fully replenish U.S. stockpiles. Until new production lines reach full capacity, the U.S. and its allies will have to prioritize the allocation of a limited number of interceptors among Europe, Ukraine, the Middle East, and the Indo-Pacific region.
According to Fixygen, the cryptocurrency market is closing out the last week of August near local highs: Bitcoin is holding steady at around $80,000 after rising above $81,000, investors are once again actively investing in spot ETFs, and the stablecoin sector continues to evolve from a primarily trading instrument into a full-fledged payment infrastructure.
On August 25, Bitcoin rose to $81,240, its highest level since mid-May. By the morning of Friday, August 28, the leading cryptocurrency had corrected to approximately $79,700; however, for the month of August, it remains up by about 26.7%, which could be its best monthly performance since the end of 2024.
Unlike many previous waves of growth, one of the key factors now is not so much speculative demand as it is investors’ concerns about U.S. government debt, the long-term value of the dollar, and the situation in the Treasury bond market.
Following the U.S. Treasury Department’s decision to increase the repurchase of long-term Treasury bonds, market participants have once again begun discussing the so-called “debasement trade”—the purchase of gold, Bitcoin, and other scarce assets as a hedge against potential currency devaluation.
Standard Chartered noted that such a policy creates precisely the macroeconomic environment for which Bitcoin was originally created. Some analysts suggest that a sustained break above the current resistance zone could pave the way to $95,000–100,000.
That said, this week was significantly calmer than the previous one. By last Friday, Bitcoin had already surged to around $77,000–78,000, posting its best weekly performance in over two years. This week, the market focused more on consolidating this gain than on launching a new upward surge.
Ether also remained relatively stable and was trading near $2,500 by the end of the week. Thus, Ethereum did not replicate the scale of Bitcoin’s August rally but continued its recovery following a weaker first half of the year.
One of the most important signals for the market was the return of funds to U.S. spot Bitcoin ETFs. According to market participants’ estimates, inflows into these funds in August approached $2.4–2.5 billion, with investors directing approximately $2.5 billion into ETFs over the last seven trading sessions.
BlackRock, the largest operator of Bitcoin ETFs, believes that institutional investors are increasingly viewing Bitcoin not only as a high-risk technology asset but also as a potential diversification tool amid debt and currency risks. BlackRock’s IBIT, the largest U.S. fund, already manages over $76 billion in assets.
This is particularly important for the market following a prolonged period of capital outflows from ETFs earlier this year. The return of institutional demand significantly increases the likelihood that August’s growth will prove more sustainable than the short-lived speculative rallies of previous months.
Another significant trend of the week is the accelerating development of stablecoins.
The volume of payments made using cards pegged to stablecoins exceeded $1 billion for the first time in July. RedotPay forecasts that by 2028, the annual volume of such payments could increase approximately fourfold—to $50 billion.
Stablecoins are being used more and more actively not only within crypto exchanges but also for cross-border transfers, corporate settlements, holding dollar liquidity, and everyday payments. This market is growing particularly rapidly in Latin America and Africa, where access to dollar-denominated banking instruments is limited.
This week, another signal came from the United Kingdom: the government proposed expanding the Bank of England’s mandate to include supporting innovation in the payments sector, particularly innovations related to stablecoins and digital currencies.
Another telling development was Chelsea Football Club’s decision to make Circle—the issuer of USDC—the title sponsor of its jerseys. The logo of one of the largest dollar-pegged stablecoins will now appear on the jerseys of the English Premier League club—a level of mainstream integration that would have seemed nearly impossible for the crypto industry just a few years ago.
Consolidation is also continuing in the industry’s institutional segment.
Crypto custodian BitGo has agreed to acquire NYDIG’s institutional trading business. With this acquisition, BitGo will gain a presence in derivatives, structured products, financing, and other services for institutional clients. Approximately 30 NYDIG employees are moving to BitGo. The parties did not disclose the value of the deal.
BitGo previously went public in 2026 and raised approximately $213 million during its IPO. The acquisition of part of NYDIG signals the continued emergence in the crypto market of companies seeking to provide institutional investors with a full range of services—from asset custody to trading, settlement, and structured financing.
Regulation in the U.S., however, remains one of the main sources of uncertainty.
President Donald Trump continues to urge Congress to pass the Clarity Act, which is intended to more clearly delineate the powers of regulators and establish rules for the operation of the cryptocurrency market. The legislative process remains protracted, but the industry is already actively preparing for the midterm congressional elections.
Stand With Crypto, an organization supported by Coinbase, announced this week its endorsement of 32 candidates who have previously voted in favor of cryptocurrency legislation. According to Reuters estimates, the crypto industry as a whole has already allocated approximately $200 million to political activities as part of the 2026 election cycle.
Thus, the last week of August cemented several trends at once: Bitcoin once again reached a level of around $80,000, institutional capital returned to ETFs, stablecoins are increasingly being used for real-world payments, and the largest crypto companies continue to build infrastructure that increasingly resembles the traditional financial sector.
The main risk for the market in the coming weeks remains macroeconomic. Investors are awaiting signals from the Federal Reserve regarding interest rates. Persistently high inflation has already reignited market expectations of a potential rate hike in the U.S., which is traditionally a negative factor for cryptocurrencies.
In September, attention will focus on the Fed meeting on September 16, U.S. labor market data, and trends in U.S. Treasury yields. Provided the dollar remains weak and demand for alternative assets stays high, the $80,000–83,000 range for Bitcoin will become a key technical threshold. A sustained breakout above this level could reignite market talk of $100,000, while rising yields and a hawkish stance from the Fed could push Bitcoin back into the mid-$70,000 range
Fixygen will continue to monitor the dynamics and trends of the crypto market.



