
China was the only G20 country that did not support a number of provisions in the final document of the meeting of finance ministers and central bank governors of the “Group of Twenty,” held August 31–September 1, 2026, in Asheville, North Carolina.
As a result, instead of a joint communiqué agreed upon by all participants, the United States, as G20 chair, issued a chair’s statement. The official document from the U.S. Department of the Treasury states that it was endorsed by all G20 members present, except for China, which opposed four sections.
One of the main points of contention was the issue of global trade imbalances. The text, supported by the other countries, calls on nations to abandon non-market policies and practices that exacerbate imbalances. Countries with excessive and persistent external trade surpluses are urged to eliminate factors that constrain domestic consumption and create excessive dependence of economic growth on exports.
U.S. Treasury Secretary Scott Bessent stated after the meeting that China was the only dissenting participant. He called China’s current account surplus the largest and “unsustainable” and stated that a non-market economic model that constantly increases the supply of cheap export goods cannot be sustainable.
China also did not support provisions to expand the International Monetary Fund’s role in monitoring global economic imbalances. The other G20 members advocated for strengthening the IMF’s analysis, including an assessment of non-market policies, the factors driving external trade imbalances, and their impact on other economies.
Another point of contention was the Strait of Hormuz. The G20 statement expressed concern over ongoing disruptions to energy trade and emphasized the need for free, safe, and predictable shipping through the Strait of Hormuz and other key maritime routes. China opposed the entire relevant section of the document.
In addition, Beijing disagreed with the section concerning sovereign debt restructuring and the continued application of the G20’s Comprehensive Framework for Addressing the Debt Problems of Developing Countries. An official document from the U.S. Treasury Department explicitly states that China objected to paragraphs 4, 10, 11, and 13 of the statement.
Despite the lack of full consensus, the remaining 19 G20 members supported the approach to reducing global imbalances. Reuters notes that the issue has effectively turned into a debate over China’s export model, industrial subsidies, and the growing supply of Chinese products to global markets.
These disagreements come amid growing concerns from the U.S., the EU, and several other major economies regarding China’s manufacturing capacity and its expanding trade surplus. Western nations fear that a glut of Chinese industrial goods could intensify pressure on local manufacturers and increase dependence on specific supply chains.
The meeting in Asheville marked the second gathering of G20 finance ministers and central bank governors under the U.S. presidency in 2026. Key topics included economic growth, global imbalances, public debt, digital assets, financial literacy, and the state of the global financial system.
The G20 currently comprises 19 countries: Argentina, Australia, Brazil, the United Kingdom, Germany, India, Indonesia, Italy, Canada, China, Mexico, Russia, Saudi Arabia, the United States, Turkey, France, South Africa, South Korea, and Japan.
In addition, the European Union and the African Union are full members of the G20. Thus, following the African Union’s accession in 2023, the G20 effectively comprises 21 members—19 countries and two regional organizations.
The Business Activity Expectations Index (BAEI) fell to 48.3 points in August 2026 from 50.1 points in July and was lower than the August 2025 figure (49.0 points), the National Bank of Ukraine (NBU) reported on its website.
The last time the BAI was in negative territory was in February 2026, when it stood at 45.9 points.
“Significant losses resulting from the widespread destruction of production facilities, warehouses, and logistics infrastructure, the blockage of seaports, high fuel prices, and a shortage of skilled workers limited economic activity among enterprises and negatively affected business sentiment,” the regulator noted.
At the same time, business activity was supported by steady consumer demand, international financial support, budgetary funding for infrastructure restoration and road construction, a stable situation in the energy sector, as well as seasonal factors.
Construction companies were the only sector among those surveyed to maintain positive assessments of their performance: the sectoral index stood at 50.7 points in August, compared to 54.2 a month earlier and 54.0 in August of last year.
Construction companies expected an increase in construction volumes, new orders, and purchases of raw materials and supplies, as well as continued growth in the volume of contractor services purchased, albeit at a slower pace.
In the services sector, the sectoral index rose to 49.5 points from 48.8 in July and exceeded the August 2025 figure (47.0 points). Companies maintained positive assessments of new orders and resumed optimistic expectations regarding the volume of services provided and those currently in progress.
Retail businesses reported weaker assessments: the sectoral index fell to 47.5 points from 50.8 in the previous month and 51.8 in August of last year. They expected a decline in sales and purchases of goods for resale, a further reduction in their inventories, and a decrease in profit margins.
Assessments from industrial firms were the most subdued: the sectoral index fell to 47.3 points in August from 50.7 in July and 48.7 in August 2025.
Unlike the previous month, manufacturers expected a decline in production volumes and new orders—particularly export orders—while forecasting an increase in inventories of raw materials and supplies.
Most of the surveyed companies expected price pressures to intensify for both purchases and their own products and services. Only construction companies forecast a slight slowdown in price growth.
Only construction companies planned to increase their workforce, while enterprises in manufacturing, trade, and the service sector expected a reduction in the number of employees, with the most significant decline expected in manufacturing.
The survey was conducted from August 4 to 21, 2026, with 586 enterprises participating: 43.7% from manufacturing, 25.9% from the service sector, 24.6% from trade, and 5.8% from construction.
Among the respondents, 30.9% were large enterprises, 29.2% were medium-sized, and 39.9% were small. Export and import operations were conducted by 35.0% of respondents; 8.0% engaged only in exports; 17.6% engaged only in imports; and 39.4% did not engage in any foreign economic operations.
The Central, Ingulets, and Northern Mining and Processing Complexes (MPCs) of the Metinvest Mining and Metallurgical Group, which were merged into the United Mining and Processing Complex, transferred 2.8 billion hryvnias to budgets at all levels for the January–June period of this year, which is 200 million hryvnias more than in the same period last year.
According to the company’s press release, Metinvest’s Kryvyi Rih mining and processing plants remain a reliable financial foundation for Ukraine even during the war and economic crisis, channeling billions of hryvnias into budgets at all levels. As has traditionally been the case, the main sources of revenue remain subsoil use fees—1.3 billion hryvnias—the unified social contribution—nearly 400 million hryvnias—and personal income tax—350 million hryvnias.
“Ukraine’s mining and metallurgical sector is going through an extremely difficult period; however, thanks to our professional and responsible specialists, Metinvest’s mining and processing plants continue to operate amid shelling and severe logistical and export restrictions. And even despite the decline in production, the United Mining and Processing Complex consistently pays all required taxes and fees. Because taxes right now mean support, protection, and survival for the country as a whole and for local communities in particular,” said Igor Tonev, CEO of the United Mining and Processing Complex.
As previously reported, including its associated companies and joint ventures, the Metinvest Group paid 8.5 billion UAH in taxes and fees to budgets at all levels in Ukraine during the first half of 2026.
In the first quarter of 2026, the United Mining and Processing Complex transferred 1.3 billion UAH to budgets at all levels.
Metinvest is a vertically integrated group of mining and metallurgical enterprises. Its facilities are located in Ukraine—in the Donetsk, Luhansk, Zaporizhzhia, and Dnipropetrovsk regions—as well as in European Union countries, the United Kingdom, and the United States. The holding’s main shareholders are the SCM Group (71.24%) and Smart Holding (23.76%). Metinvest Holding LLC is the management company of the Metinvest Group.
BUDGET, KRYVYI RIH, METINVEST, TAX, ГЗК
Over the next two weeks, domestic prices for gasoline and diesel may rise by 4.5–5 UAH per liter due to a price surge on global markets to levels close to April’s highs; specifically, the price of diesel fuel in London rising above $1,400 per metric ton, according to Serhiy Kuyun, director of the “A-95” consulting group.
“We are expecting domestic prices to rise. Currently, this increase translates to an additional 4.5–5.0 UAH per liter of gasoline and diesel fuel (their current average prices are 80 and 91 UAH per liter, respectively). This could happen within a couple of weeks if current prices stabilize at their current levels,” he wrote on Facebook on Wednesday.
According to the expert, on September 1 and 2, some Ukrainian retail chains had already raised prices by 1 UAH per liter.
“There are no fuel availability issues, neither here nor in Europe. Therefore, the issue is solely about price. The much-discussed 100 UAH per liter mark hasn’t been reached yet, but it’s starting to loom on the horizon again,” Kuyun noted.
As reported by “Energoreforma,” fuel prices in Ukraine showed both slight decreases and increases throughout August.
According to “A-95,” as of September 2, the average retail price in Ukraine for A-95 gasoline is 80.7 UAH/liter, and for diesel fuel, 91.31 UAH/liter.
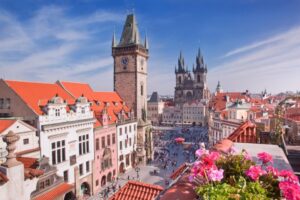
Residential real estate prices in the Czech Republic rose by 10.06% year-over-year in the first quarter of 2026; adjusted for inflation, real growth stood at 8.33%, marking the highest rate since the 2021 housing boom, according to data from the Czech Statistical Office analyzed by Global Property Guide.
According to data from Ukraine’s largest international real estate agency, Homium, the nominal value of residential real estate in the Czech Republic has more than doubled over the past 11 years and is now 18% higher than the previous cyclical peak in the third quarter of 2022.
At the same time, the growth rates of the primary and secondary markets have virtually evened out. New housing prices rose by 10.01% over the year, while existing housing prices increased by 10.07%.
According to Homium, a company that deals in Czech real estate among other markets, price growth is being driven by a combination of limited supply of new housing and a recovery in mortgage demand. The company is also seeing particularly high interest in Prague and Brno, where the supply shortage is most pronounced.
“The Czech market is currently interesting because, following the 2022–2023 correction, it returned to growth fairly quickly. At the same time, buyers are becoming more price-sensitive, so demand is gradually shifting toward small apartments in Prague, outlying areas, and resale properties. For investment buyers, not only the potential appreciation of a property but also its liquidity in the rental market is becoming increasingly important,” Homium commented on the situation.
According to Homium, in May–June 2026, studio apartments and 1+kk apartments in central Prague were listed for approximately 248–414 thousand euros, in the capital’s outskirts for 186–269 thousand euros, and in Brno for 145–207 thousand euros. For 2+kk apartments, the price range was 331,000–580,000 euros, 248,000–373,000 euros, and 207,000–331,000 euros, respectively.
Prague remains the country’s most expensive market. According to data from the Global Property Guide, the average price of an apartment in the capital in 2025 was approximately 5,44 thousand euros per square meter, which was about 82% higher than the Czech average of approximately 3 thousand euros per square meter. In the Prague new-construction market, the average asking price reached about 7,310 euros per square meter, and in the most expensive district, Praha 1, it was about 10,850 euros per square meter.
Older residential properties remain more affordable. The average price of apartments in prefabricated buildings is estimated at approximately 2,94 thousand euros per square meter, while new housing from developers costs on average nearly twice as much—about 5,8 thousand euros per square meter.
Rapid price growth has already become a factor in the country’s monetary policy. On June 18, 2026, the Czech National Bank raised its key two-week repo rate by 0.25 percentage points to 3.75%. The regulator points to persistent inflationary pressures, including those stemming from housing and service costs.
In addition, in June, the CNB decided to increase the countercyclical capital buffer for banks from 1.25% to 1.5% starting in July 2027, citing active lending, rising household and corporate debt, and further increases in apartment prices as reasons for the decision.
The average gross yield on long-term residential leases in the Czech Republic in the second quarter of 2026 was 3.39% per annum. In the most expensive district, Prague 1, yields on individual apartments ranged from approximately 2.3% to 3.3%, while in more affordable areas of Prague, they could approach 4%.
Homium believes that, in the medium term, the main market drivers will remain limited construction rates, the cost of mortgage financing, and sustained demand for housing in major cities. At the same time, following the sharp growth of recent quarters, investors should evaluate the yield of a specific property more carefully, as purchase prices in Prague are rising faster than potential rental yields.
Homium has been operating in the international real estate market for over 10 years and offers properties in the Czech Republic, Spain, Turkey, Greece, Montenegro, Bulgaria, Croatia, Poland, and several other countries. In the Czech Republic, the majority of the properties listed by the company are concentrated in Prague and Karlovy Vary.
The primary source of price statistics is the Czech Statistical Office; the market analysis was published by Global Property Guide and updated in August 2026.
Source:
Global Property Guide – https://www.globalpropertyguide.com/europe/czech-republic/price-history
Homium – https://homium.ua/czech-republic/
CZECH REPUBLIC, housing. Homium, INVESTMENT, PRAGUE, REAL ESTATE



