
According to Experts.news, Turkish Airlines took first place among European airlines in the regional ranking of the 2026 World Airline Awards by the international organization Skytrax, published on September 18.
Air France took second place among European carriers, and Lufthansa took third. They were followed by Iberia, Virgin Atlantic, Swiss International Air Lines, British Airways, KLM Royal Dutch Airlines, Austrian Airlines, and Finnair.
Thus, the ranking of the top ten European airlines is as follows: Turkish Airlines, Air France, Lufthansa, Iberia, Virgin Atlantic, Swiss, British Airways, KLM, Austrian Airlines, and Finnair.
Skytrax also published separate rankings by European region.
In Western Europe, Air France took first place, Lufthansa second, and Virgin Atlantic third. In Northern Europe, Finnair took the lead, followed by SAS Scandinavian and Icelandair.
In Southern Europe, Turkish Airlines also took first place, Iberia second, and Vueling Airlines third.
In Central Europe, LOT Polish Airlines topped the rankings. Wizz Air took second place, and Croatia Airlines came in third. These carriers are of particular practical importance to Ukrainian passengers, as a significant portion of international flights now operate through airports in neighboring European countries following the closure of Ukraine’s civil airspace.
In Eastern Europe, Latvia’s airBaltic topped the 2026 ranking. Air Serbia came in second, and Georgian Airways took third. Bulgaria Air and Romania’s TAROM also made it into the top five.
The World Airline Awards are based on an international passenger survey. The 2025/2026 survey was conducted from September 2025 through August 2026 and covered more than 300 airlines. Respondents represented over 100 nationalities.
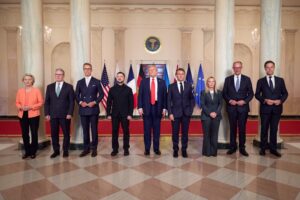
A meeting involving representatives from Ukraine, the U.S., and Europe is set to take place in the near future, Ukrainian President Volodymyr Zelenskyy said following a meeting with Steve Witkoff and Jared Kushner, representatives of U.S. President Donald Trump.
“We agreed that Ukraine, Europe, and the U.S. will meet in the near future. I don’t know where the meeting will take place. Perhaps in Ukraine again,” Zelenskyy said at a press conference in Kyiv.
The president noted that the American delegation’s visit worked for Kyiv “like a Patriot” and emphasized Ukraine’s need for it.
According to him, during the meeting, the parties discussed the challenges facing Ukraine on the eve of winter and a possible winter aid package.
The Experts Club analytical center analyzed data from the international consulting firm Savills on real estate market trends in the world’s leading countries and identified a number of trends in the European real estate market in 2026.
Investment in European real estate reached 54 billion euros in the second quarter of 2026, up 7.7% year-over-year, according to Savills data.
Despite the overall increase in transaction volume, Savills characterizes the recovery of the European market as uneven. Escalating macroeconomic and geopolitical risks have forced investors to raise their standards for property quality.
Capital is now primarily directed toward real estate that provides a stable cash flow, has a transparent market value, and is located in segments with long-term structural demand.
One of the main beneficiaries of this new investment strategy has been so-called “living real estate.”
In the first half of 2026, multifamily rental housing, specialized student dormitories, senior living facilities, and housing for the elderly already accounted for 29% of all real estate investments in Europe.
Thus, nearly one in every three euros of institutional capital directed toward European real estate went to properties directly related to residential living.
The growing interest in this sector is linked to a housing shortage in many major European cities, rising rents, demographic changes, and relatively stable income streams compared to some traditional types of commercial real estate.
At the same time, investor attitudes toward office properties are shifting. High-quality, modern office buildings in central business districts remain in demand, while outdated and poorly located properties are significantly harder to sell or finance.
According to Savills, the market is effectively divided into two types of assets. In the first category, investors are willing to compete for high-quality properties with reliable tenants and predictable income. In the second, real estate with a poor location, high future costs, or uncertain demand may remain outside the scope of investment interest for a long time.
Savills notes that Europe remains an important destination for global capital, but investment requirements have become significantly stricter.
Markets where a significant price correction has already occurred and a clearer entry point for investors has emerged have the best chances of attracting capital. An additional advantage is the limited supply of new properties and stable demand from tenants.
“The recovery is taking place in stages and is driven by investor confidence in specific deals, rather than a general willingness to take risks,” note Savills analysts.
Thus, the European real estate market is gradually emerging from a period of sharp interest rate hikes and asset revaluation; however, the new investment cycle differs significantly from the previous one. Capital is increasingly being directed not simply toward real estate as an asset class, but toward specific segments with the most predictable long-term demand.
Source: Savills, Global Capital Markets Research Q2 2026 — Europe.
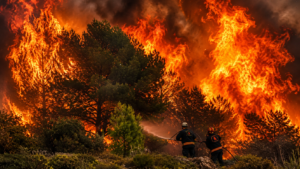
The 2026 fire season in Europe has become one of the most difficult in terms of the geographical spread of fires and the scale of their consequences, with Ukraine ranking among the continent’s most affected countries, the Experts Club information and analytical center reports, citing data from the Global Wildfire Information System (GWIS), the European Forest Fire Information System (EFFIS) and other European bodies.
As of August 31, the area affected by fire in Ukraine was estimated by GWIS at 413.1 thousand hectares, or about 0.69% of the country’s territory. If the Russian Federation is not included in the direct comparison, as the system also takes into account the vast territories of Siberia and the Far East, Ukraine ranks first among the countries of geographical Europe in terms of the absolute area affected by fires.
It is followed by Spain — 242.1 thousand hectares, Italy — 118.3 thousand hectares, France — 105.1 thousand hectares, and Portugal — 60.5 thousand hectares.
In Ukraine, fire statistics have an additional specific feature due to the war. Satellite systems record the territory affected by fire but do not determine its cause. Therefore, alongside heat, drought, careless handling of fire and arson, shelling, explosions and fires along the front line may also play a significant role.
The greatest burden relative to the size of the territory is recorded in the Balkans. In Montenegro, about 1.7% of the country’s territory has been affected by fire, in Bosnia and Herzegovina — more than 1%, and in North Macedonia — about 0.75%. Altogether, Montenegro, Bosnia and Herzegovina, North Macedonia, Albania and Serbia have about 142 thousand hectares of burned areas.
A separate feature of the season has been a sharp increase in fire activity in countries where large fires are traditionally less common. In Belgium, the area affected by fires has already exceeded the average for 2012–2025 by more than ten times, in the Netherlands — by approximately three times, in Austria — by 2.5 times, and in France — by almost 2.5 times.
In the EU itself, by August 30, 636.1 thousand hectares of burned areas had been recorded within 1,861 major fires. This is 36% less than in the record year of 2025, but more than twice the long-term average for the same period.
Office real estate regained the top spot among commercial real estate investment sectors in Central and Eastern Europe in the first half of 2026, according to data from Colliers.
Offices accounted for 29% of total investment in the CEE-6, up from 23% a year earlier. With a total market volume of EUR 5.8 billion, this corresponds to approximately EUR 1.7 billion in investments.
Retail real estate became the second-largest segment, with a 27% share, up from 21% in the first half of 2025.
Investor interest in residential and “living” properties grew even faster. Their combined share rose from 7% to 19%.
At the same time, industrial and logistics real estate—which was the largest market segment just a year ago—saw its share decline from 31% to 17%. This was due not only to changes in activity within the warehouse market itself but also to the rapid growth of transactions in other real estate classes.
Colliers notes that in the office segment, investors are primarily seeking modern buildings in prime locations with high energy efficiency and a stable stream of rental income.
The situation is becoming more challenging for outdated office buildings. They must either undergo modernization or be considered for repurposing.
Thus, the structure of the CEE market is gradually changing: after several years of logistics dominance, capital is once again flowing more actively into traditional offices and retail real estate, while institutional housing is emerging as a major investment segment in its own right.
Czech capital was one of the most active sources of investment in the Central and Eastern European real estate market in the first half of 2026, according to a Colliers study.
The total volume of investments by Czech investors in the region is estimated at approximately 1.9 billion euros. The presence of Czech capital was particularly noticeable in Poland, the largest investment market in Central and Eastern Europe.
Investors from the Czech Republic accounted for 23.6% of all investments in Polish commercial real estate from January through June. Germany accounted for about 19%, Polish capital for 11.5%, U.S. capital for 10.6%, and Hungarian capital for 6.8%.
The Czech Republic itself, meanwhile, remained the second-largest market in the CEE-6. In the first half of the year, deals totaling over 1.4 billion euros were concluded there. This is less than the record 2.2 billion euros for the same period in 2025; however, according to Colliers’ assessment, the market remains one of the most stable in the region.
Yields on premium office properties in Prague are estimated at approximately 5.25%, on prime warehouse facilities at around 5%, and on shopping centers at around 6%. These are among the lowest capitalization rates among the largest markets in Central Europe, reflecting investors’ relatively high valuation of Czech assets.
The activity of Czech capital in neighboring countries is part of a broader trend. Colliers notes that in the Central and Eastern European (CEE) markets, the influence of not only global funds from the U.S. and Western Europe but also investors from Central Europe itself is growing.
This is gradually fostering the development of a distinct regional investment capital capable of sustaining transactions even during periods when major international funds adopt a more cautious approach toward the region.



