
International capital has become noticeably more active in Germany’s residential real estate market: in the third quarter of 2026, foreign buyers accounted for about 75% of investment volume in this segment, according to data from the international consulting firm CBRE.
The volume of residential real estate transactions in Germany from July through September totaled approximately €2.3 billion, marking the best quarterly result since the beginning of the year. Compared to the second quarter, investment volume increased by approximately 17%.
Overall, from January through September 2026, investment in German residential real estate approached 5.9 billion euros, which is approximately 4% less than during the same period last year.
However, CBRE does not disclose the geographic breakdown of foreign investors nor specify which countries’ capital accounted for the bulk of these investments. Therefore, the 75% figure should be viewed as the share of total foreign institutional capital, rather than as an indicator of investments by citizens of any specific country.
This primarily refers to professional investors—investment funds, management companies, family offices, and other large capital holders—who purchase residential portfolios and multi-unit properties. These figures do not reflect the activity of private foreign investors who purchase individual apartments or houses in Germany.
Large portfolio transactions played a key role in the market’s recovery. Portfolio transactions accounted for approximately 75% of total investment volume in the third quarter, with just a few large transactions accounting for more than half of the quarterly turnover.
Existing residential buildings and completed new-construction projects remain the primary focus of interest—they accounted for about 89% of transactions. Investments in projects in the early stages of construction, including forward purchases and forward funding, remain significantly weaker.
CBRE attributes this to a decline in the supply of new multifamily projects. High construction and financing costs, as well as risks for developers, are limiting the launch of new projects.
The most active investors were those focused on higher returns and future appreciation of property values. Value-add and opportunistic strategies accounted for about 58% of quarterly investment volume, while the more conservative core and core-plus strategies accounted for about 42%.
At the same time, the number of transactions fell to 44 from 51 in the second quarter. Thus, the increase in turnover is attributable not to a rise in the number of purchases, but primarily to a larger average transaction size.
Residential real estate remains the largest segment of the German investment market: in the first nine months of the year, it accounted for about 25% of total real estate investment in Germany.
As before, international capital continues to focus on the country’s seven largest markets—Berlin, Munich, Frankfurt, Hamburg, Düsseldorf, Cologne, and Stuttgart. At the same time, CBRE notes growing interest in regional markets, where investors expect to find a more attractive risk-return ratio.
The average peak yield for apartment buildings in the largest cities rose by 0.2 percentage points in the third quarter—to 3.59%—making entry prices more attractive to some investors.
Source: CBRE Germany — Residential Investment Market Q3 2026
foreign investor, GERMANY, HOUSING, INVESTMENTS, REAL ESTATE
From January through September 2026, Ukraine exported insulated wires and cables, including fiber-optic products, worth $1.065 billion, maintaining shipment volumes at virtually the same level as the same period last year.
According to data from the State Customs Service, Germany remains the largest market for Ukrainian cable products. Over the nine-month period, shipments to this country totaled $348.7 million, down 2.8% compared to January–September 2025.
Germany’s share of Ukraine’s total exports of wires and cables decreased by approximately 1 percentage point—to 32.7%—but the country continues to account for nearly one-third of the industry’s total export revenue.
Poland ranks second, with Ukraine supplying $177.1 million worth of products, compared to $168.1 million a year earlier. Thus, exports to Poland increased by approximately 5.4%.
Hungary retained its third position with purchases totaling about $172 million, virtually unchanged from last year’s figure of $172.3 million.
The three largest European markets—Germany, Poland, and Hungary—accounted for a total of nearly $698 million in January–September, or about 65.5% of Ukraine’s total exports of wires and cables.
In September, exports of these products totaled $122.7 million. Compared to September of last year, this figure decreased by 6.6%, but compared to August 2026, it increased by 26%.
The cable industry remains one of the most prominent export-oriented segments of Ukraine’s machine-building and component manufacturing sectors. A significant portion of the products is supplied to companies in the European automotive, electrical engineering, and industrial sectors.
For the full year 2025, Ukraine increased its exports of insulated wires and cables by 10.6%—to $1.41 billion. If shipment rates in the fourth quarter remain close to last year’s levels, the annual export volume in 2026 may also remain at around $1.4 billion.
Germany remains one of the countries with a high level of positive perception among Ukrainians; however, in August 2026, this figure dropped significantly compared to the previous survey wave. According to the results of a survey by Active Group and Experts Club, 69.9% of respondents have a positive attitude toward Germany, while 5.5% have a negative one, reports the Experts Club Information and Analytical Center.
According to the August survey, 26.8% of Ukrainians view Germany entirely positively, and 43.1% view it mostly positively. A neutral stance was held by 23.5% of respondents. A mostly negative attitude was expressed by 4.9%, a completely negative one by 0.6%, and another 1.2% were undecided.
The balance of positive and negative assessments stands at plus 64.4 percentage points. This keeps Germany among the countries with a distinctly positive perception, although the figure is lower compared to previous surveys. In August 2026, Germany ranked behind France and the Netherlands among Western European countries in terms of the share of positive attitudes.
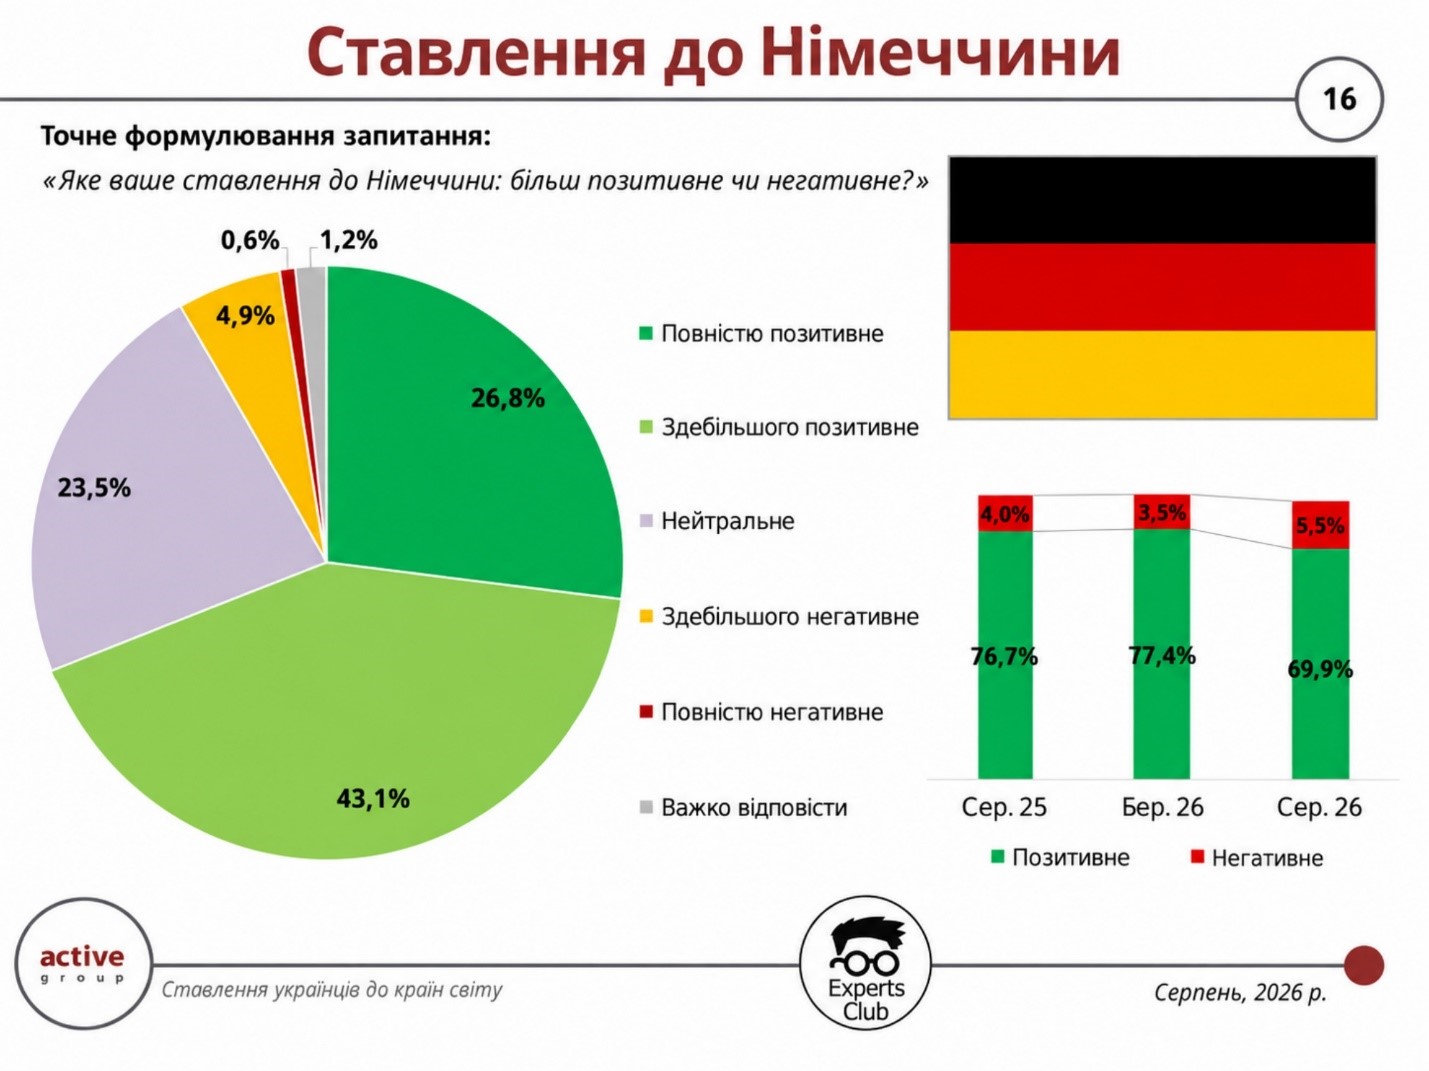
In March 2026, 77.4% of respondents viewed Germany positively: 32.9% viewed it entirely positively and 44.5% viewed it mostly positively. Negative assessments accounted for only 3.5%, while 18.4% of respondents chose a neutral response.
Thus, over the course of five months, the share of positive assessments decreased by 7.5 percentage points—from 77.4% to 69.9%—while negative assessments increased by 2 percentage points—from 3.5% to 5.5%—and neutral assessments rose by approximately 5.1 percentage points. The balance between positive and negative assessments fell from 73.9 to 64.4 percentage points. However, positive attitudes still outnumber negative ones by nearly 13 to 1.
At the same time, Germany remains one of Ukraine’s largest trading partners. In the first half of 2026, Ukrainian exports to Germany totaled approximately $1.267 billion, imports amounted to $3.208 billion, and total trade volume reached about $4.48 billion. The trade deficit for Ukraine amounted to approximately $1.94 billion. Ukraine’s main exports included cable products, rapeseed, furniture, soybeans, and metal pipes, while imports from Germany consisted of automobiles, pharmaceuticals, petroleum products, and agricultural machinery.
Oleksandr Pozniy, director of the research firm Active Group, commenting on Ukrainians’ high regard for Germany in the previous wave of the survey, attributed it to a combination of factors that go beyond purely economic relations.
“Germany is viewed as a strategic ally in the political and security spheres. Hundreds of thousands of Ukrainian refugees have found shelter there, and large-scale financial and military aid plays a key role in the resilience of our state. The combination of these factors explains why more than three-quarters of Ukrainians view Germany positively and why this country remains among the undisputed leaders in terms of trust within our society,” Pozniy noted.
The new wave of the survey shows that the level of positive attitudes toward Germany has declined compared to the spring, but there has been no fundamental change in the structure of public opinions: positive responses continue to significantly outnumber negative ones, and the main increase occurred not in the category of negative attitudes but in that of neutral ones.
The survey was conducted in August 2026 using an online self-administered questionnaire via the SunFlowerSociology panel among 800 Ukrainian citizens aged 18 and older. The sample is representative by age, gender, and region; the maximum theoretical margin of error for indicators at the 50% confidence level is ±3.5 percentage points.
ACTIVE GROUP, EXPERTS CLUB, FOREIGN TRADE, GERMANY, international relations, Pozniy, PUBLIC OPINION, SOCIOLOGY, UKRAINE
According to Experts Club, France and the Netherlands have the highest share of positive attitudes among Ukrainians among the Western European countries included in the study — 72.8% and 71.2%, respectively. Germany is viewed positively by 69.9% of respondents, and Switzerland by 66.9%. These findings come from the third wave of the study “Ukrainians’ Attitudes Toward Countries Around the World,” conducted by Active Group in collaboration with Experts Club, reports the Experts Club Information and Analytical Center.
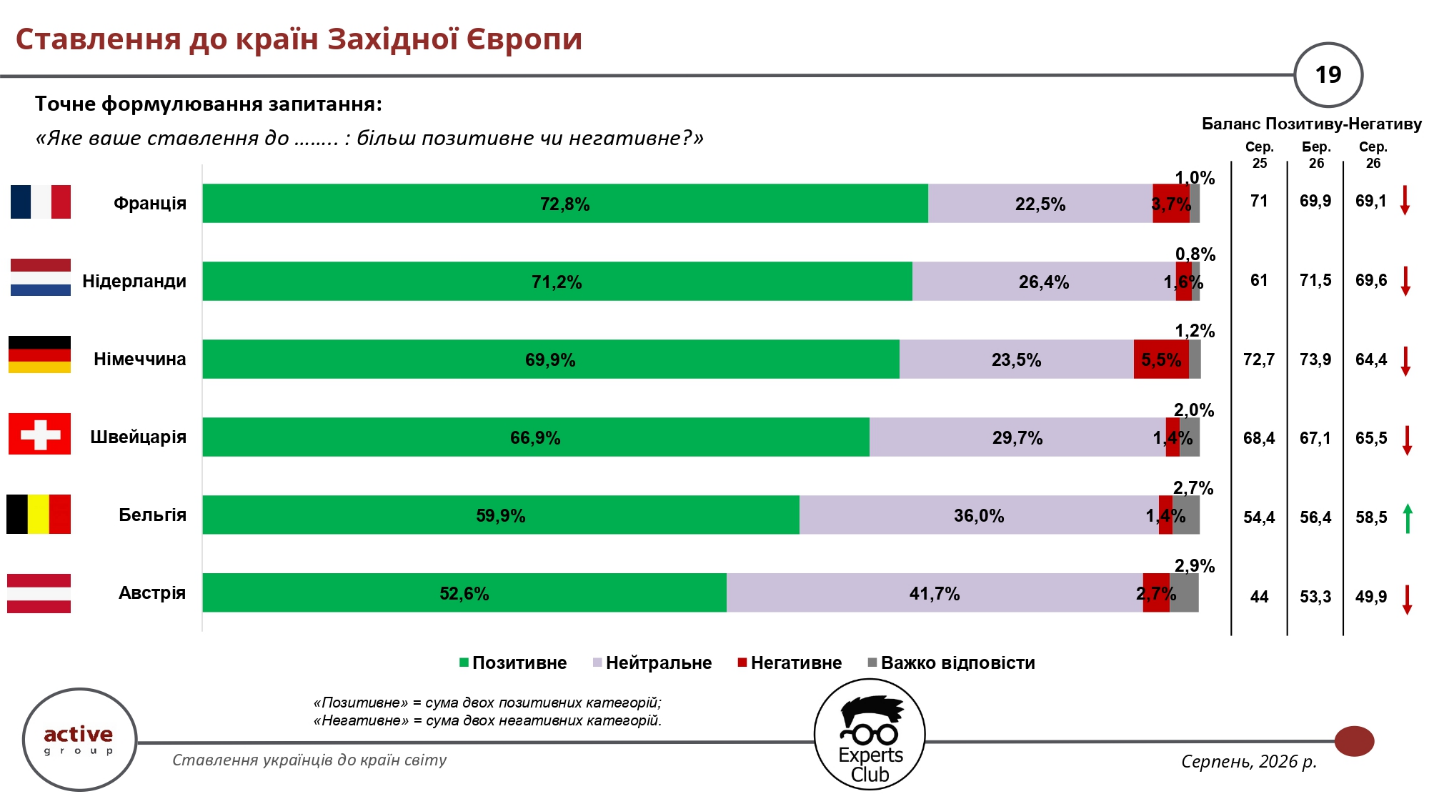
According to the results of the August survey, 22.5% of respondents have a neutral attitude toward France, 3.7% have a negative attitude, and another 1% were undecided. The balance of positive and negative assessments stands at 69.1 percentage points, compared to 69.9 percentage points in March 2026 and 71 percentage points in August 2025.
For the Netherlands, the balance of positive and negative attitudes stands at 69.6 percentage points. Specifically, 71.2% of respondents view the country positively, 26.4% neutrally, and only 1.6% negatively. In March 2026, the balance was slightly higher—71.5 percentage points—while in August 2025 it stood at 61 percentage points.
69.9% of Ukrainians view Germany positively, 23.5% neutrally, and 5.5% negatively. Its net balance fell to 64.4 percentage points, compared to 73.9 percentage points in March and 72.7 percentage points in August of last year. Thus, among the six Western European countries surveyed, Germany showed the most significant decline in this indicator between March and August 2026.
Switzerland is viewed positively by 66.9% of respondents, negatively by only 1.4%, and 29.7% hold a neutral view. The balance stands at 65.5 percentage points, compared to 67.1 percentage points in March.
Belgium is the only country in this group where the balance increased in August compared to March—from 56.4 to 58.5 percentage points. 59.9% of respondents view the country positively, 36% neutrally, and 1.4% negatively. In August 2025, the balance stood at 54.4 percentage points
Austria received the lowest share of positive responses among the Western European countries surveyed—52.6%. At the same time, only 2.7% of Ukrainians view it negatively, while 41.7% chose a neutral response. The balance stands at 49.9 percentage points, compared to 53.3 percentage points in March 2026 and 44 percentage points in August 2025. Overall, the data indicate that the lower levels of positive attitudes toward Belgium and Austria are primarily due to a higher proportion of neutral, rather than negative, assessments.
Maksym Urakin, founder of the Experts Club Information and Analytical Center, deputy director of the Interfax-Ukraine news agency, and candidate of economic sciences, emphasized the importance of systematic communication between foreign partners and Ukrainian society.
“The first recommendation is to regularly showcase concrete achievements and specific actions. The second is to be open to questions and inquiries from the media and the public,” Urakin noted.
Oleksandr Pozniy, director of the research company Active Group, for his part, drew attention to the link between public awareness and the practical development of bilateral cooperation.
“We should focus not only on raising general awareness. We need to expand cooperation with countries where we can achieve a positive balance,” Pozniy noted.
The survey was conducted in August 2026 using self-administered online questionnaires in the SunFlowerSociology panel among 800 Ukrainian citizens aged 18 and older. According to the organizers, the sample is representative in terms of age, gender, and region; the maximum theoretical statistical margin of error at a 95% confidence level is 3.5%. This is the third wave of the study, following surveys conducted in August 2025 and March 2026.
ACTIVE GROUP, AUSTRIA, BELGIUM, EXPERTS CLUB, FRANCE, GERMANY, SOCIOLOGY, SWITZERLAND, THE NETHERLANDS, UKRAINE, WESTERN EUROPE
According to the European Union’s statistical office, in 2025, European Union countries imported 2.9 million metric tons of coffee worth a total of EUR 18.7 billion from non-EU countries.
In terms of volume, imports have increased only slightly over the past ten years (from 2.7 million metric tons in 2015), but in terms of value, they have risen significantly (from EUR8.6 billion), the report states.
Last year, the main coffee suppliers were Brazil (1.005 million metric tons, or 34% of the total volume) and Vietnam (587,500 metric tons, or 20%). EU countries also purchased coffee from Uganda (262,400 metric tons, 9%), Colombia (162,900 metric tons, 6%), and Honduras (136,500 metric tons, 5%).
Germany accounted for about one-third of imports, purchasing 1.01 million metric tons of coffee (34% of the total volume). Next were Italy (608,000 metric tons, 21%), Spain (281,600 metric tons, 10%), Belgium (269,200 metric tons, 9%), and the Netherlands (216,600 metric tons, 7%).
In 2025, the European Union produced over 2.2 million metric tons of coffee (including coffee substitutes and decaffeinated beverages). This is 12% more than in 2015 (2 million metric tons).
The leading producers were Germany (561,200 metric tons, or 25% of the total volume) and Italy (514,200 metric tons, 23%). They were followed, at a considerable distance, by Spain (211,900 metric tons, 10%), France (146,800 metric tons, 7%), Poland (134,800 metric tons, 6%), Sweden (79,400 metric tons, 4%), and Finland (39,000 metric tons, 2%). Collectively, these seven countries accounted for 77% of production.
Germany will reduce the annual limit for admitting workers under the Westbalkanregelung programme from 50,000 to 25,000 people, which will affect citizens of six Western Balkan countries at once — Albania, Bosnia and Herzegovina, Kosovo, Montenegro, North Macedonia and Serbia, the Experts Club analytical center reports, citing data from the German government and the Federal Employment Agency.
The new limit is to take effect from 2027 and effectively means a return to the level that existed before June 2024, when Germany doubled the annual quota from 25,000 to 50,000 people.
Westbalkanregelung has been in force since 2016 and is a special mechanism providing citizens of the Western Balkans with access to the German labor market.
The main difference between the programme and many other channels of labor migration is that it applies not only to qualified specialists. A citizen of one of the six countries can obtain permission to work in Germany if they have a specific job offer from a German employer, while recognition of professional qualifications in Germany is generally not a mandatory requirement.
Regulated professions, such as doctors, remain an exception, as separate qualification recognition requirements apply to them.
It is precisely because of this that Westbalkanregelung has become one of the most accessible channels of legal labor migration from the region to Germany.
At the same time, there are no separate national quotas for Serbia, Albania, Bosnia and Herzegovina, Kosovo, Montenegro or North Macedonia. The limit is common to all six countries, so reducing it to 25,000 people will mean increased competition among applicants from across the region.
Demand for the programme already significantly exceeds supply.
According to Germany’s Federal Employment Agency, demand continued to grow after the quota was increased to 50,000 places. In December 2025 alone, the agency had to reject around 18,000 applications because the annual limit had already been exhausted.
At the same time, the scale of labor migration from the Western Balkans significantly exceeds the figures directly related to this programme.
The Federal Employment Agency notes that, among the relevant category of foreign workers, citizens of Albania, Bosnia and Herzegovina, Kosovo, Montenegro, North Macedonia and Serbia account for around a quarter of all employees in Germany covered by social insurance who have a residence permit or permanent residence based on employment.
Thus, over the past decade, the Western Balkans have become one of the important external sources of labor for the German economy.
“The German decision is interesting because it comes against the backdrop of two opposing trends. On the one hand, the German economy is experiencing a structural shortage of workers and is interested in attracting foreign labor. On the other hand, the state is tightening migration controls and reducing one of the most accessible employment channels for citizens of the Western Balkans,” said Maksym Urakin, founder of the Experts Club analytical center.
According to Experts Club, the most immediate consequence of the quota reduction may be increased competition for permits among citizens of the six countries.
If demand already exceeded supply with a limit of 50,000 places, halving the quota could potentially increase waiting times and the share of applicants who will not be able to use the programme in a particular calendar year.
At the same time, the Westbalkanregelung mechanism itself is not being closed. Citizens of the region will still be able to work in Germany through other labor migration channels provided for by law if they meet the established requirements.
Germany’s decision is also of particular interest from the demographic perspective of the Western Balkans themselves. Serbia, Bosnia and Herzegovina, North Macedonia, Albania, Montenegro and Kosovo have for many years been sources of labor migration to EU countries, primarily Germany, Austria and other Western European economies.
For the countries of the region, the mass outflow of the working-age population has a dual effect. Remittances from citizens working abroad support household incomes and domestic consumption, but at the same time emigration increases labor shortages within the Balkan economies themselves.
The outflow of medical personnel, construction workers, drivers, technical specialists, service-sector employees and other categories that are in demand both in Germany and in the domestic labor markets of the countries of the region remains particularly sensitive.
“For the Western Balkans, Germany’s decision may somewhat reduce one of the channels of labor outflow, but it is unlikely by itself to substantially change migration processes. The difference in wages and employment opportunities between Germany and most of the region remains the main economic driver of migration,” Urakin believes.
The reduction of Westbalkanregelung is part of a broader adjustment of the German government’s migration policy. Among its objectives, the cabinet lists reducing irregular migration, expanding the list of safe countries of origin, increasing the number of returns and introducing stricter regulation of migration flows.
At the same time, Berlin continues to emphasize the need for legal migration for the German labor market.
This creates a certain paradox: Germany is restricting one of the most in-demand regional channels of labor migration at precisely the moment when population ageing and staff shortages are forcing the German economy to search more actively for workers outside the country.
For the Western Balkans, the consequences are also ambiguous. The quota reduction potentially reduces opportunities for new labor emigration, but at the same time may somewhat reduce pressure on national labor markets, which themselves face worker shortages.
The key indicator of the effectiveness of the decision will be how quickly the new quota of 25,000 permits is exhausted after its introduction. If demand remains at its current level, Westbalkanregelung will effectively become a significantly more competitive channel of access to the German labor market.
The Westbalkanregelung programme has been in force in Germany since 2016 and applies to citizens of Albania, Bosnia and Herzegovina, Kosovo, Montenegro, North Macedonia and Serbia. In mid-2024, the annual limit was increased from 25,000 to 50,000 people. The German government has decided to limit it again to 25,000 permits per year.
Sources: Federal Government of Germany, Federal Employment Agency of Germany.
EMPLOYMENT, GERMANY, Labor market, MIGRATION, Western Balkans



