
The Czech Republic and Moldova have the highest net sentiment—the balance of positive and negative attitudes—among Ukrainians among the Central and Eastern European countries included in the study—56.2 and 48.2 percentage points, respectively. At the same time, the balance of attitudes toward Poland turned negative in August 2026, while assessments of Slovakia and Hungary improved significantly compared to previous waves. This is evidenced by the results of the third wave of the study “Ukrainians’ Attitudes Toward Countries Around the World,” conducted by Active Group in collaboration with Experts Club, according to the Experts Club Information and Analytical Center.
The Czech Republic received the highest share of positive assessments in this group—61.3%. 32.1% of respondents have a neutral attitude toward it, 5.1% have a negative attitude, and another 1.6% were undecided. The balance of positive and negative attitudes stands at 56.2 percentage points, compared to 64.4 percentage points in March 2026 and 58.7 percentage points in August 2025.
Regarding Moldova, 55.4% of respondents have a positive attitude, 35.6% are neutral, and 7.2% have a negative attitude. The balance stands at 48.2 percentage points, which is lower than the 54.7 percentage points recorded in March but higher than the 46.6 percentage points recorded in August of last year.
Regarding Romania, 45.2% of respondents expressed a positive attitude, 42.3% were neutral, and 9.8% were negative. The balance fell to 35.4 percentage points from 41.7 percentage points in March. In Bulgaria, positive assessments accounted for 42.7%, neutral ones for 47.6%, and negative ones for 7.4%, with the balance standing at 35.3 percentage points, compared to 51.5 percentage points in March.
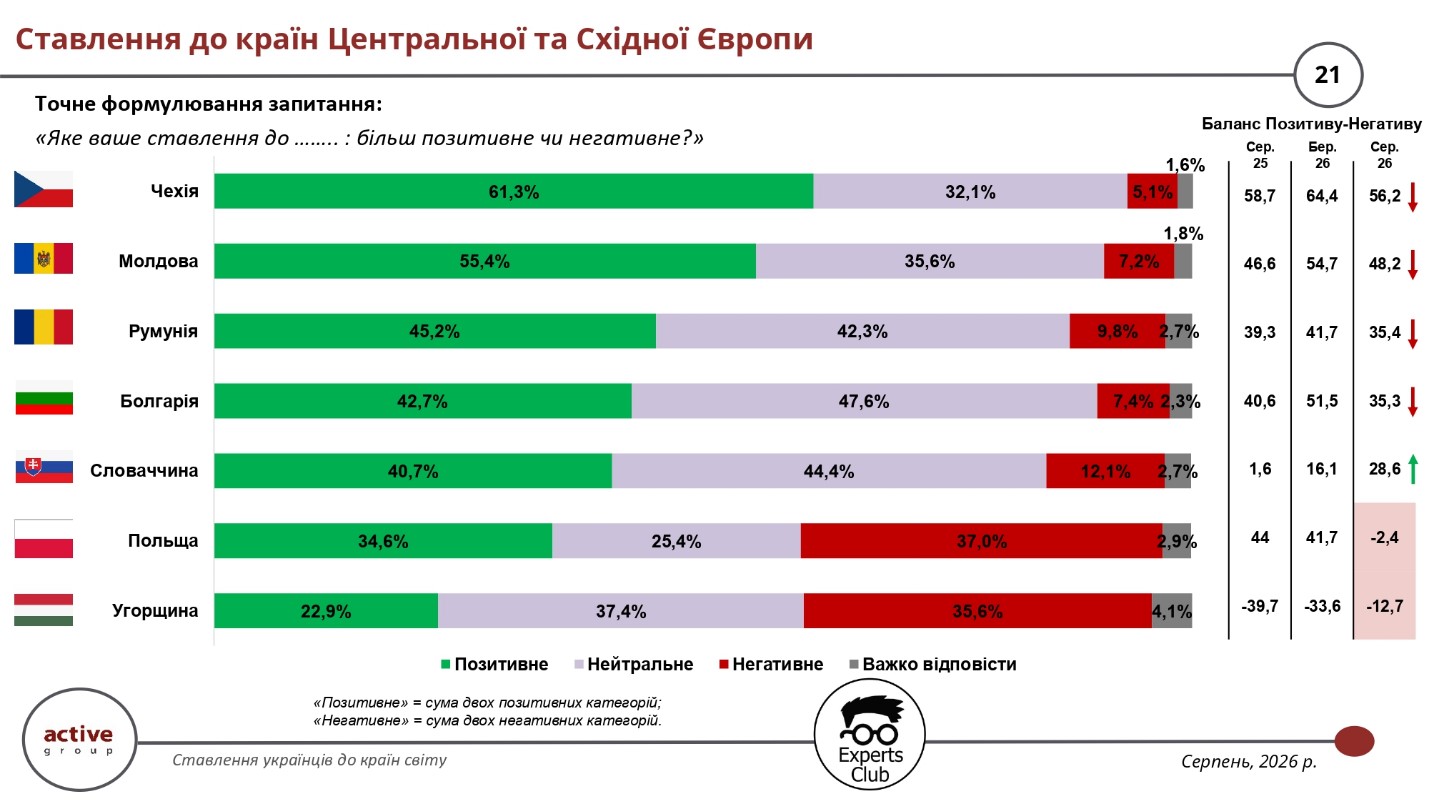
Unlike most countries in the group, attitudes toward Slovakia showed a noticeable improvement. It is viewed positively by 40.7% of respondents, negatively by 12.1%, and neutrally by 44.4%. The balance rose to 28.6 percentage points from 16.1 percentage points in March 2026 and just 1.6 percentage points in August 2025.
The sharpest negative trend was recorded regarding Poland. 34.6% of Ukrainians view it positively, 37% negatively, and 25.4% neutrally. As a result, the net balance stands at minus 2.4 percentage points, whereas in March 2026 it was plus 41.7 percentage points, and in August 2025—plus 44 percentage points. The deterioration in attitudes toward Poland was one of the most notable shifts in the third wave of the survey.
Hungary remains in the negative zone: 22.9% of respondents expressed a positive attitude, 35.6% a negative one, and 37.4% a neutral one. At the same time, its balance improved to minus 12.7 percentage points compared to minus 33.6 percentage points in March and minus 39.7 percentage points in August 2025.
Maksym Urakin, founder of the Experts Club Information and Analytical Center, deputy director of the Interfax-Ukraine news agency, and candidate of economic sciences, emphasized that public perception of countries must be analyzed in parallel with Ukraine’s actual economic ties.
“That is why it is very important for us to analyze our main partners. The first recommendation is to regularly showcase concrete projects, specific actions, and the presence here of foundations, embassies, teams, and diplomats in the humanitarian sphere and in science. We also need to use our sociological data to draw conclusions and strengthen our relations, particularly trade relations,” Urakin noted.
Oleksandr Pozniy, director of the research firm Active Group, highlighted the practical significance of the study’s findings for economic and diplomatic policy.
“We should focus on developing more than just general awareness. First and foremost, business associations, the Ministry of Economy, and the Ministry of Foreign Affairs need to work to develop bilateral relations and improve the balance of trade. We must expand cooperation with countries where we can achieve a positive trade balance,” Pozniy noted.
The survey was conducted in August 2026 using self-administered online questionnaires in the SunFlowerSociology panel among 800 Ukrainian citizens aged 18 and older. According to the organizers, the sample is representative by age, gender, and region, with a maximum theoretical margin of error of 3.5%. This is the third wave of the study, following surveys conducted in August 2025 and March 2026.
ACTIVE GROUP, BULGARIA, Central Europe, CZECH REPUBLIC, EASTERN EUROPE, EXPERTS CLUB, HUNGARY, MOLDOVA, POLAND, Pozniy, ROMANIA, SLOVAKIA, SOCIOLOGY, UKRAINE, URAKIN
According to Experts Club, China ranked last among Ukraine’s 50 largest trading partners in terms of the balance of positive and negative attitudes among Ukrainians—in August 2026, the figure stood at minus 25.4 percentage points. The next lowest results were recorded for India and Hungary—minus 14.3 and minus 12.7 percentage points, respectively. This is evidenced by the results of the third wave of the study “Ukrainians’ Attitudes Toward Countries Around the World,” conducted by Active Group in collaboration with Experts Club, reports the Experts Club Information and Analytical Center.
The balance was defined as the difference between the shares of positive and negative assessments. Regarding China, 18.2% of respondents expressed a positive attitude, 43.6% a negative one, and another 33.9% a neutral one. Thus, China received the lowest score among all countries surveyed, despite the fact that in the first half of 2026, China was Ukraine’s largest trading partner with a trade volume of approximately $14.68 billion.
The top ten countries with the lowest scores also included Lebanon—minus 9.2 percentage points—and Poland—minus 2.3 percentage points. Serbia, Algeria, Libya, Vietnam, and Tunisia remained in the positive range, however, their scores were among the lowest among the countries surveyed: Serbia at plus 2.3 percentage points, Algeria at plus 2.2, Libya at plus 1.0, Vietnam at plus 9.4, and Tunisia at plus 11.0 percentage points.
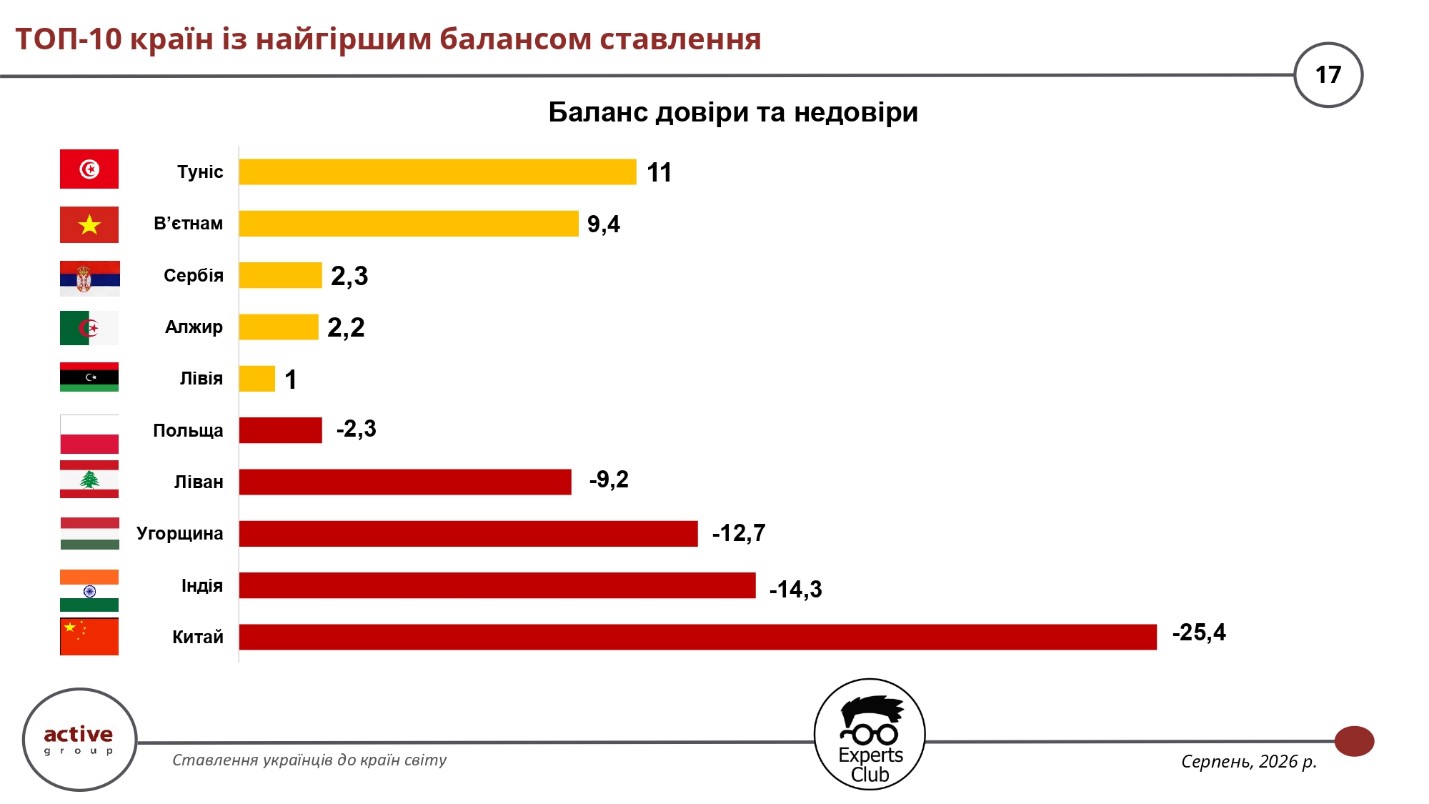
The shift in attitudes toward Poland was particularly noticeable. In March 2026, the balance of positive and negative assessments stood at +41.7 percentage points, whereas in August it fell to –2.3 percentage points. A positive attitude toward Poland was expressed by 34.6% of respondents, a negative one by 37%, and a neutral one by 25.4%. At the same time, Poland remains one of Ukraine’s largest trading partners and the largest market for Ukrainian goods exports among individual countries in the first half of 2026.
Maksym Urakin, founder of the Experts Club Information and Analytical Center, deputy director of the Interfax-Ukraine news agency, and candidate of economic sciences, noted that the results of the sociological survey should be analyzed in conjunction with actual trade figures.
“Second, we must be open to questions and inquiries from the media and the public. We also need to make use of our sociological research,” Urakin noted. In his view, systematic communication and the demonstration of concrete results of cooperation can help governments better explain the nature of bilateral relations to Ukrainian society.
Oleksandr Pozniy, director of the research company Active Group, highlighted the need to combine public awareness with the practical development of economic ties.
“We need to do more than just raise general awareness. We must expand cooperation with countries where we can achieve a positive trade balance,” Pozniy noted. He emphasized the role of business associations, economic institutions, and diplomatic missions in developing bilateral ties, especially with markets where Ukraine can increase its exports.
Overall, the survey results show that the scale of trade and economic ties does not always correspond to public attitudes toward the respective country. China stands out as the most striking example: it has the highest trade volume among individual partners, yet is simultaneously associated with the lowest ratings among Ukrainians.
The survey was conducted in August 2026 using self-administered online questionnaires in the SunFlowerSociology panel among 800 Ukrainian citizens aged 18 and older. The sample is representative by age, gender, and region; the maximum theoretical margin of error for indicators at the 50% confidence level is ±3.5 percentage points. This is the third wave of the study, following surveys conducted in August 2025 and March 2026.
ACTIVE GROUP, CHINA, EXPERTS CLUB, FOREIGN TRADE, HUNGARY, INDIA, international relations, POLAND, SOCIOLOGY, UKRAINE
In Hungary, starting January 1, 2027, the VAT rate for certain new housing units may increase from the current reduced rate of 5% to the standard rate of 27%, which will put additional pressure on the prices of apartments in new buildings, according to local media reports.
The current preferential rate of 5% applies to new apartments with an area of up to 150 square meters and single-family homes with an area of up to 300 square meters that meet the established requirements. According to an official clarification from the Hungarian National Tax and Customs Administration (NAV), this regime, in its current form, remains in effect until December 31, 2026.
After that, the standard VAT rate of 27% will apply to properties that do not meet the conditions of the transition period.
However, a significant portion of projects already underway will be able to retain the tax benefit until the end of 2030. Specifically, the 5% rate may apply after December 31, 2026, if the required building permit has become final by the end of 2026. Transitional provisions are also in place for projects implemented under the construction notification procedure.
As a result, the Hungarian market may effectively feature new construction projects with varying tax burdens simultaneously, depending on the project’s start date and legal status.
The potential impact on housing prices could be significant. An apartment costing 100 million forints, taking into account the current 5% VAT rate, has a pre-tax price of approximately 95.2 million forints. If a 27% rate were applied to the same base, the final price would be approximately 121 million forints. The theoretical difference is about 21 million forints, or approximately 58,000 euros.
However, the actual price increase may be smaller, as developers may absorb part of the additional tax burden themselves in the face of weakening demand.
A decline in buyer activity is already being observed in the market. According to data from the National Bank of Hungary, the number of real estate transactions in the first quarter of 2026 fell by 18% compared to the same period the previous year. According to Duna House estimates, approximately 8,100 residential real estate transactions were concluded in August—13.1% fewer than in July and 29% fewer than a year earlier.
At the same time, developers are accelerating the preparation of new projects. In the first half of 2026, permits were issued and notifications were registered in Hungary for the construction of 16,588 residential units, which is 29% more than during the same period in 2025.
The change in the tax regime does not directly affect the resale housing market. However, the widening price gap between new projects subject to a 27% VAT rate, properties retaining the 5% rate, and the resale market may affect the structure of demand and housing prices overall.
Certain new apartments in officially designated “rust belt action areas” will remain an exception: provided they meet the requirements established for them, the preferential 5% rate will continue to apply even after January 1, 2027.
Hungary plans to meet the country’s natural gas needs without supplies from Russia by October 2027, said István Kapitány, the country’s Minister of Economy and Energy.
“If everything goes as we expect, Hungary’s gas supply will be secured from other, non-Russian sources by the deadline set by the European Union in October of next year,” the minister said in an interview with Telex published on September 18.
According to Kapitány, Hungary’s high dependence on Russian gas did not arise from a lack of technical capacity to purchase fuel from other countries. Hungary is connected by gas pipelines to several neighboring countries, and the Russian supply system was used for a long time primarily because it was considered the most cost-effective option. The minister did not specify by how much the share of Russian gas has already decreased in recent months.
The deadline is directly linked to new EU regulations. EU Regulation 2026/261 provides for the cessation of imports of Russian pipeline gas under long-term contracts after September 30, 2027. In exceptional cases, if a country is unable to ensure the required level of storage filling, the deadline may be extended to November 1, 2027.
For Hungary, the transition is particularly significant, as the state-owned MVM maintains a long-term contract with Gazprom Export for approximately 4.5 billion cubic meters of gas per year. The contract originally runs through 2036; however, MVM’s own documents note that the European ban will effectively prevent the use of Russian long-term supplies after the fall of 2027. The company is already expanding its portfolio of alternative gas sources.
LNG is becoming one of the key areas of focus. MVM ONEnergy has signed a five-year contract with the U.S.-based Chevron for approximately 2 billion cubic meters of liquefied natural gas. Deliveries under this contract are scheduled to begin on October 1, 2027, immediately after EU restrictions on Russian pipeline gas take effect.
In addition, MVM has reached an agreement with Azerbaijan’s SOCAR for the supply of 800 million cubic meters of gas over a two-year period starting in 2026.
Romania is emerging as another potential source. The development of the Neptun Deep field in Romania’s sector of the Black Sea is expected to begin production in 2027. Once it reaches full capacity, it is projected to supply approximately 8 billion cubic meters of gas per year, which will create additional opportunities for deliveries to Central Europe, including Hungary.
Thus, Captain’s statement signals a significant shift in Hungarian energy policy: Budapest, which in previous years had opposed an accelerated phase-out of Russian fuel, is now preparing its gas supply balance to meet EU requirements by the fall of 2027. At the same time, the minister emphasized that the country has sufficient gas supplies for the current heating season and that the authorities do not anticipate any problems with the physical availability of fuel.
The Hungarian housing market continued its recovery in 2025, with prices rising by 20% in nominal terms and by 15% after adjusting for inflation. The number of registered transactions approached 136,000, and the final figure, according to estimates by the Hungarian Central Statistical Office (KSH), is expected to exceed 140,000 transactions, according to the latest annual market review.
However, the KSH has not yet published detailed statistics for 2025 breaking down homebuyers by citizenship. The latest available comprehensive snapshot shows that in 2024, foreign nationals purchased 6,600 residential properties in Hungary with a total value of approximately 834 million euros. This represented a 5.2% increase in the number of properties compared to the previous year.
Thus, foreigners accounted for about 5% of all real estate transactions in Hungary in 2024, and in monetary terms, they accounted for 6.4% of the market’s turnover. In total, approximately 131,100 real estate properties were sold in the country that year.
Following a decline in activity in 2023, the number of transactions in Hungary rose by 25% in 2024—to 131,100. Growth continued in 2025: as of the data cutoff, the Hungarian Central Statistical Office (KSH) had received information on 135,700 sales, of which 128,200 were in the resale market and approximately 7,600 were new construction units. The final number of transactions is expected to exceed 140,000.
The market picked up particularly noticeably in the second half of the year following the launch of the Home Start government program for subsidized housing loans. In September, the number of sales was 47% higher than a year earlier, and in the fourth quarter, KSH estimated annual growth in the number of transactions at approximately 10%.
In Budapest, the average price per square meter for resale housing in the fourth quarter of 2025 was approximately 3,240 euros.
The average price of a sold property reached approximately 184,000 euros. Prefabricated apartments sold for an average of approximately 165,000 euros, while single-family homes sold for 284,000 euros.
The price per square meter in the capital rose by 21% over the year. At the same time, growth was even higher in certain segments: prefabricated apartments rose in price by approximately 35%.
Outside the capital, the highest prices among administrative centers at the end of 2025 were observed in Debrecen—about 2,620 euros per square meter, Dióra—2,450 euros, Veszprém—2,440 euros, and Szeged—about 2,380 euros per square meter.
Although comprehensive statistics for 2025 are nearly complete, the most recent detailed ranking of buyers by citizenship published by the KSH still pertains to 2024.
Foreign nationals purchased 6,600 residential properties that year, which is 5.2% more than in 2023.
The total value of real estate purchased by foreigners amounted to approximately 834 million euros, or 6.4% of the Hungarian housing market’s turnover.
Statistics by major groups of foreigners in 2024:
Germany — 1,369 properties
China — 708
Romania — 671
Slovakia — 671
Netherlands — 438
Vietnam — 329
Austria — 268
Russia — 185
Ukraine — 144
Israel — 137
Differences between groups of foreign buyers are particularly noticeable in terms of the geographic location of purchases.
Chinese citizens completed 91.5% of their transactions in Budapest, Vietnamese buyers — 96%, and Russians — 84.9%.
Ukrainians were significantly less focused on the capital: only 39.6% of the homes they purchased were located in Budapest. Thus, the majority of Ukrainian buyers chose other cities and regions of Hungary.
Germans, despite ranking first in the number of transactions, showed virtually no concentration in the capital—Budapest accounted for only 8% of their purchases. The KSH notes high activity among German citizens in small towns in the Southern and Western Transdanubia regions.
The average price of a property purchased by a Ukrainian citizen was approximately 96,000 euros, and the average price per square meter was about 1,350 euros.
Nationwide in Hungary, foreigners account for about 5% of the total number of transactions, but their share is significantly higher in Budapest. In 2024, foreign citizens accounted for 7.8% of residential purchases in the capital and 10% of their total value.
In the inner districts of Pest, foreigners accounted for approximately 19% of all transactions and, in terms of value, represented about 26% of the market. Chinese and Vietnamese buyers were particularly prominent here.
Thus, the latest official statistics already allow us to assess the Hungarian real estate market for 2025: approximately 136,000 registered transactions, with the prospect of exceeding 140,000 after final data processing; a 20% increase in prices; and a further significant rise in housing costs in Budapest and most major cities.
However, the breakdown of purchases by citizenship for 2025 has not yet been published.
Source: Hungarian Central Statistical Office (KSH).
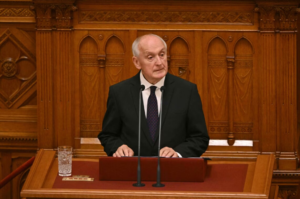
The Hungarian parliament has elected former Supreme Court president András Baka as the country’s new president, marking another important stage in the restructuring of Hungary’s political system following the end of Viktor Orbán’s 16-year rule.
On 11 August, 140 MPs voted for the 73-year-old lawyer, while six voted against. Representatives of the opposition Fidesz party did not participate in the vote, protesting against the early termination of the powers of the previous president, Tamás Sulyok. Baka is due to officially take office on 19 August.
Baka’s election is primarily of political and institutional significance. The president of Hungary does not head the government or determine the country’s economic or foreign policy, but can serve as a constitutional counterweight to the parliamentary majority and the cabinet. This function is particularly important now, as Prime Minister Péter Magyar’s Tisza party holds a constitutional majority in parliament and is carrying out sweeping changes to the institutions shaped under Orbán.
Baka fits well into this political arrangement. From 1991 to 2008, he served as a judge at the European Court of Human Rights, and in 2009 parliament elected him president of the Supreme Court of Hungary. His mandate was terminated early in early 2012 after he publicly criticised the Orbán government’s judicial reforms. The European Court of Human Rights subsequently found violations of his right of access to a court and freedom of expression.
Therefore, Baka’s return to one of the country’s highest public offices almost 15 years later has clear symbolic significance. It demonstrates the new authorities’ intention to distance themselves from the institutional model of the Orbán era while simultaneously making the independence of the judiciary one of the central themes of the political transformation.
“For Hungarian society, this is much more than an ordinary change of president. After sixteen years of dominance by a single political force, any large-scale restructuring of state institutions will inevitably be perceived differently by society. For supporters of change, this is an opportunity to restore the system of checks and balances, while for a significant proportion of Fidesz supporters, what is happening may look like political revenge by the new authorities,” said Oleksandr Poznii, an expert at the Experts Club analytical centre and co-founder and director of the Active Group research company.
According to Poznii, the key test will be the ability of the new institutions to demonstrate genuine independence from Péter Magyar’s government.
“Baka’s main task is not to become the president of the victorious party. If the new head of state can truly distance himself from the government and act as an arbiter between different political groups, this will be an important signal to society. Otherwise, Hungary risks seeing not the dismantling of the former model of concentrated power, but merely a change in the political force controlling that model,” Poznii noted.
The sociologist also draws attention to the high degree of political polarisation in Hungarian society. In such a situation, the significance of the presidential office is determined not so much by the scope of its formal powers as by the trust that different groups of the population place in the head of state.
“In countries with strong political polarisation, symbolic institutions can be far more important than the text of the constitution might suggest. The president may not manage the economy or foreign policy, but he can either reduce the level of conflict in society or, conversely, become another participant in that conflict. Therefore, the main measure of Baka’s success will not be the number of laws he blocks, but whether he can be perceived as the president of all Hungarians,” Poznii emphasised.
Following his election, Baka himself stated that under the previous authorities the system of checks and balances had effectively ceased to function, but stressed that political change should not turn into revenge against supporters of the former government. He also declared his intention to represent citizens with different political views.
Hungary is a parliamentary republic, meaning that the real centre of executive power is located not in the presidential palace, but in the government.
Under the Fundamental Law of Hungary, the president is the head of state, embodies the unity of the nation and is responsible for safeguarding the democratic functioning of state institutions. At the same time, the president has no executive power of his own and does not head the ministries.
Nevertheless, his powers extend beyond purely ceremonial functions. The president signs laws adopted by parliament and, before signing, may return a law to MPs once for reconsideration. If he considers a document to be contrary to the Fundamental Law, he may refer it to the Constitutional Court.
Following parliamentary elections, the president proposes a candidate for prime minister to parliament. He also formally appoints ministers upon the recommendation of the head of government, performs a range of personnel and representative functions, and represents the Hungarian state in foreign relations.
Thus, the head of state can delay certain decisions by the parliamentary majority or initiate a constitutional review of them, but cannot independently determine the country’s political course.
The prime minister, by contrast, is the effective head of the executive branch. The government is the principal body of executive power and public administration, while the prime minister determines its overall political course. It is the prime minister who forms the government team, directs the work of the cabinet and, through the parliamentary majority, implements the principal budgetary, economic, social and foreign policy decisions.
Therefore, the key political figure in Hungary remains Péter Magyar, who came to power following Tisza’s victory in the April parliamentary elections. The party won two-thirds of the seats in parliament, ending Orbán’s 16-year period of uninterrupted rule.
After coming to power, Magyar began seeking the replacement of the heads of a number of state institutions associated with the previous system of government. One of the most notable episodes was the early termination of President Tamás Sulyok’s term of office.
For the new authorities, Baka’s election is particularly symbolic because of his long-standing conflict with the Orbán system. The former president of the Supreme Court is effectively returning to the highest level of state politics after the defeat of the political force under which he lost his judicial post.
At the same time, this is precisely where one of the main risks facing Hungary’s new political system emerges. Tisza holds a constitutional majority and therefore has exceptionally broad powers to change laws and institutions. The new authorities must consequently dismantle the mechanisms created under Orbán while simultaneously proving that they are not replacing them with their own party control.
This is the paradox of Hungary’s new political arrangement: Magyar has obtained an exceptionally strong position thanks to his parliamentary majority, while Baka is expected to embody a limit on the excessive concentration of power.
For Ukrainian audiences, Hungary’s transformation also has foreign policy significance. Following Orbán’s defeat, Budapest’s position on Ukraine has become less confrontational, although Magyar does not present himself as an unconditional supporter of Kyiv and continues to link some bilateral issues to the situation of the Hungarian minority in Transcarpathia.
Therefore, the ultimate criterion for determining whether Hungary has entered a new political era will be not only the departure of officials from the Orbán era, but also whether the new authorities can establish a system of institutions capable of functioning independently of whichever party controls parliament and the government.



