
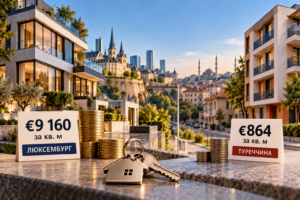
The most expensive newly built homes among the European markets surveyed are located in Luxembourg, the Czech Republic and Germany, while the cheapest are in Turkey, Serbia and Albania. At the same time, in a number of cities in Central and Southeastern Europe, purchasing housing requires more than 15 average annual salaries, according to the findings of the Deloitte Property Index 2026 study.
As the international consulting company Deloitte reported on October 13, 2026, its 15th annual study covered 25 countries and 71 cities. The indicators are based on data for 2025 and include prices of newly built residential properties, apartment purchase affordability, rental rates, residential construction and mortgage lending.
According to Deloitte, the average price per square meter of new housing in Luxembourg reached €9,160, compared with €5,412 in the Czech Republic, €5,200 in Germany, €5,199 in Austria and €5,186 in the Netherlands.
By contrast, the average price of new housing in Turkey was €864 per sq. m, compared with €1,706 in Serbia, €1,720 in Albania, €1,917 in Romania and €1,931 in Greece.
Thus, the difference between the most expensive and cheapest national markets among the countries surveyed exceeded tenfold.
Ranking of countries with the highest average prices for new housing in 2025:
Luxembourg — €9,160 per sq. m.
Czech Republic — €5,412.
Germany — €5,200.
Austria — €5,199.
Netherlands — €5,186.
Five countries with the lowest prices:
Turkey — €864 per sq. m.
Serbia — €1,706.
Albania — €1,720.
Romania — €1,917.
Greece — €1,931.
At the same time, a low absolute price per square meter does not always mean high housing affordability for the local population, since the determining factor is the ratio between property prices and household incomes.
The least affordable among the cities surveyed was the Albanian city of Vlorë, where purchasing a standard new apartment measuring 70 sq. m requires 21.3 average gross annual salaries. In Prague, this figure was 16.9 annual salaries, in Athens — 16, and in Slovakia’s Košice and the Czech city of Brno — 15 each.
Cities with low housing affordability also included Bratislava, where purchasing a standard apartment requires 13.7 annual salaries, and Banská Bystrica, with a figure of 13.4.
At the opposite end was the Italian city of Turin, where purchasing a new 70 sq. m home requires 4.7 average annual salaries. In Norway’s Bergen and Denmark’s Odense, the figure was 4.9 salaries each.
Overall, the number of European cities surveyed where purchasing a standard apartment requires more than ten annual salaries increased from 11 to 19.
Separately, Deloitte analyzed the largest urban markets in terms of the absolute cost of new housing. Munich was the most expensive, with an average price of €11,200 per sq. m. It was followed by Luxembourg City at €10,567, Amsterdam at €8,650 and Barcelona at €8,037.
The cheapest new homes among the major cities surveyed were offered in Turkey: the average price was €870 per sq. m in Ankara, €1,155 in Izmir and €1,339 in Istanbul.
In 2025, increases in average new housing prices were recorded in 19 of the 22 countries for which Deloitte had comparable nationwide data. The highest rates of price growth were observed in Romania (+14.4%), Croatia (+14.3%), Slovakia (+12.5%) and Hungary (+10.9%).
By contrast, according to the study, average prices in euros decreased by 9% in Turkey and 2.5% in Serbia. At the same time, individual urban markets showed the opposite trend. In particular, new housing prices rose by 20% in Belgrade and by approximately 24% in the Albanian city of Durrës.
Luxembourg became the most expensive rental housing market, with an average monthly rate of €45.4 per sq. m. In Paris, rent amounted to €31.2 per sq. m, in Barcelona — €30.9, Dublin — €30.8 and Oslo — €28.9.
Significant differences in the cost of mortgage lending also persist across European countries. Deloitte recorded the highest average rates in Hungary at 9.08%, Poland at 6.91%, Romania at 5.86% and Norway at 5.44%. The lowest figures were in Bulgaria and Finland at 2.77% each, Turkey at 2.84%, Croatia at 2.90% and Spain at 2.94%.
The average mortgage rate in the countries surveyed fell by 0.38 percentage points to 4.09%.
Turkey led in the number of completed residential units, with nearly 674,000 housing units put into operation in 2025. The corresponding figure was 379,000 in France, 209,000 in Poland and 207,000 in Germany.
Ukraine is not represented in the Deloitte Property Index 2026 ranking, so its average price per square meter cannot be directly compared with the figures for other countries within the framework of this study.
At the same time, according to the State Statistics Service of Ukraine, the housing price index in the primary market increased by 13% in 2025, while in the secondary market it rose by 13.4%. These indicators reflect changes in prices in Ukrainian hryvnias rather than the average price per square meter in euros, and therefore are not part of the Deloitte ranking.
Additionally, in May 2026, the State Statistics Service updated its methodology for calculating housing price indices in accordance with European statistical standards.
Deloitte analysts note that the main problem facing the European market remains the mismatch between rising housing prices and household incomes. The situation is aggravated by the limited supply of new homes, high construction costs, lengthy permit procedures and the cost of mortgage financing.
The Deloitte Property Index is an annual international study of residential real estate markets that the company has conducted for 15 years. It is used to compare housing prices and affordability, residential construction, rental markets and mortgage lending across European countries.
Sources: Deloitte Property Index 2026 — official study, Deloitte, press release dated October 12, 2026, State Statistics Service of Ukraine — housing price statistics.

The number of housing starts in the United States in February increased by 10.7% compared to the previous month and amounted to 1.521 million at an annualized rate, according to a press release from the country’s Commerce Department. This is the most significant increase in the last nine months.
According to the revised data, in January the number of new buildings was 1.374 million (down 12.3%), not 1.331 million (down 14.8%), as previously reported.
Analysts on average had forecast a 7.1% decline from the previously announced January level, according to Trading Economics.
Construction of single-family homes jumped 11.6% last month to 1.129 million. The number of new apartment buildings (including apartments and condominiums), a more volatile segment of the market, increased by 8.6% to 377 thousand.
Meanwhile, the number of building permits for new homes in February increased by 1.9% to 1.518 million in annualized terms. This is the highest figure since August last year. Analysts had expected a rise of only 0.4%.
At the same time, the number of permits for the construction of single-family houses increased by 1%, and apartment buildings – by 4.1%.
Sales of apartments in Ukrainian new buildings in the third quarter of 2023 recovered by 24% from the pre-war level, while demand for housing is already at 70-80%, according to a study by the LUN real estate portal.
“We compared the sales of developers with the figures for 2021. At the end of 2022, sales recovered to 11%. In 2023, sales grew rapidly and as of the third quarter recovered by almost a quarter to 24%. We see the market recovering in all segments in 2023. Now people are buying ready-made housing or with a commissioning period of up to 1 year. But it is already obvious that deferred demand is forming. In the absence of escalation, we can expect the market to stabilize,” said Olga Okhrimenko, LUN Sales Director, at the RED Online Meeting “Housing Market: Results 2023 and Forecasts 2024”.
According to the study, sales in Kyiv and Kyiv region are recovering at a slower pace and are currently at 17% of the pre-war level. At the same time, sales in Lviv and the region reached 42%.
To date, sales have been opened in 83% of residential complexes in Ukraine, and construction has resumed at 77% of construction sites, LUN notes. In December 2023, 916 residential complexes are under construction, of which 4% have already been sold out, 3% have not yet started sales, and 5% have stopped sales.
The largest number of residential complexes with open sales is in the Kyiv region: 230 in Kyiv and 182 in Kyiv region. Other leaders are Lviv region (238 objects for sale), Odesa (135), Ivano-Frankivsk (91), Khmelnytsky (88) and Ternopil (80).
According to LUN, after the start of the full-scale invasion, sales started in 275 residential complexes, most of them in Lviv region (79), Kyiv region (43), Ternopil region (29), Ivano-Frankivsk region (24) and Zakarpattia region (23). During this period, 294 residential complexes completed sales.
Okhrimenko noted that over the past six months, the issuance of mortgage loans under the eHouse program has been showing active dynamics, which has a positive impact on the demand for housing.
“As for the interest in buying an apartment, today it has recovered to the level of 70-80% after falling to 30% in February 2022. People are now interested in buying an apartment again, both in the primary and secondary real estate markets,” the expert said.
At the same time, the slow pace of housing commissioning may provoke a shortage of new apartments for participants in the 7% government program, under which the chosen house must be no older than three years. Thus, according to LUN, in January-September 2023, 15% less housing was commissioned in the capital than last year, 35% less in Kyiv region, and 38% less in Lviv.
Average prices for new buildings increased in almost all regions over the year, according to the study. Prices remained at the same level in Kyiv (UAH 47.3 thousand per square meter), Lviv region (UAH 35.8 thousand per square meter) and Dnipropetrovs’k region (UAH 39.2 thousand per square meter). At the same time, prices decreased by 6% (to UAH 33 thousand per square meter) in Odesa region, by 8% (to UAH 31.1 thousand per square meter) in Vinnytsia region and by 21% (to UAH 26.9 thousand per square meter) in Mykolaiv region.
The largest increase in average housing prices was recorded in Kharkiv region – by 35% (to UAH 28.3 thousand per square meter), Kirovohrad region – by 26% (to UAH 31.5 thousand per square meter), Khmelnytsky region – by 22% (to UAH 24.3 thousand per square meter).
According to LUN, Lviv holds the lead in terms of the high cost of new buildings with 48.5 thousand UAH/sq. m. This is followed by Kyiv at 48 thousand UAH/sq m, Uzhhorod at 41.5 thousand UAH/sq m, Dnipro at 40 thousand UAH/sq m and Odesa at 36.2 thousand UAH/sq m.
In the secondary market, average housing prices increase depending on the distance from the area of active hostilities, Okhrimenko noted.
“The farther the region is from the fighting, the higher the prices are. The exception is the capital. Many Kyiv residents are not returning yet and have not decided to buy housing. That is why Kyiv is not raising prices yet, and has even reduced them a bit,” she explained.
The largest increase in prices in the secondary market over the past six months was shown by Lviv – a “plus” of $6.4 thousand, up to $58.5 thousand for a one-bedroom apartment. Prices also increased significantly in Ivano-Frankivsk (+$4.7 thousand, up to $31.7 thousand), Chernihiv (+$4 thousand, up to $31 thousand) and Cherkasy (+$3.4 thousand, up to $38.4 thousand).
Average prices for two-bedroom apartments in the secondary market increased the most in Vinnytsia (+$8.9 thousand, to $59.9 thousand), as well as in Chernivtsi (+7 thousand, to $62 thousand), Lviv (+$7 thousand, to $87 thousand) and Cherkasy (+$7 thousand, to $57 thousand).
Three-bedroom housing on the secondary market has risen in price the most in Vinnytsia (+$8.8 thousand, to $75.8 thousand), Lviv (+$7.7 thousand, to $108.7 thousand), Ivano-Frankivsk (+$7 thousand, to $60 thousand). At the same time, the average price of three-bedroom apartments in the secondary market in Kyiv fell by $8 thousand to $135 thousand.

Sales of new homes in the United States in June decreased by 2.5% compared to the previous month and amounted to 697 thousand in terms of annualized rate, the Ministry of Commerce reported.
According to the revised data, 715 thousand homes were sold in May this year, not 763 thousand, as previously reported.
At the same time, analysts on average expected a 5% decline in sales last month from the previously announced May level – to 725 thousand, according to Trading Economics.
Sales of new homes in June increased by 23.8% compared to the same month a year earlier.
The median price of a new home in the United States last month was $415.4 thousand, compared to $417.3 thousand in May and $432.7 thousand in June 2022.
The number of new buildings for sale at the end of June amounted to 432 thousand compared to 429 thousand a month earlier. At the current rate of sales, it would take 7.4 months to sell all new buildings in the United States, compared to 7.2 months in May. Experts traditionally believe that a six-month supply indicates a balanced market.
New real estate accounts for about 10% of the US housing market, but sales of new homes are registered immediately after the signing of the contract, which makes them a more relevant indicator of the market.
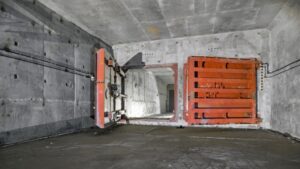
Kyiv authorities are initiating appeals on the need to improve the legislation in terms of the requirement of compulsory equipping new housing with shelters, the press service of Kyiv City State Administration said.
“Today, developers, unfortunately, bypass the existing requirements of compulsory installation of shelters in houses. The reason is in the gaps of the current legislation, which requires providing for shelters in the construction project or the possibility to use the shelter nearby. Well, the “or” should not be! We can see what it has led to: there are practically no new buildings in the fund of protective constructions”, – deputy head of Kyiv City State Administration Petr Panteleev is quoted in the press release.
In addition, he notes that the SES and local self-government are also removed from the process of taking the houses into use.
According to the KSCA, from 4.2 thousand shelters tested in the capital 2.9 thousand are suitable for use, another 736 can be shelters, provided they are properly equipped. 578 facilities do not meet the regulatory requirements for the premises where shelters can be equipped.
As reported, the law “On Amendments to Certain Legislative Acts of Ukraine on ensuring civil protection requirements during the planning and development of territories,” which, in particular, provides for mandatory placement of bomb shelters in new buildings, was signed by the president in August 2022.
Share of new buildings, in which construction was resumed, by regions of Ukraine

Source: Open4Business.com.ua and experts.news



