
In January–September 2026, Ukraine increased its imports of insulated wires and cables by 22.7%—to $540.7 million, with China significantly outpacing traditional European suppliers in this segment for the first time.
According to the State Customs Service, imports of Chinese cable products reached $157 million, compared to $92.6 million during the same period last year.
Thus, in just one year, shipments from China grew by approximately 69.5%, and its share of Ukraine’s wire and cable imports approached 29%.
Hungary remains the second-largest supplier. Over the nine-month period, Ukraine imported $124 million worth of wires and cables from Hungary, compared to $114 million a year earlier, representing an increase of approximately 8.8%.
Poland ranked third with shipments totaling $74 million, compared to $74.7 million in January–September 2025.
Thus, China, Hungary, and Poland together accounted for about $355 million, or nearly two-thirds of all Ukrainian imports of cable products.
The main change in the market structure was the strengthening of China’s position. Just a year ago, Hungary was the largest supplier, whereas now the value of Chinese imports exceeds that of Hungary’s by approximately $33 million.
The rapid growth in imports may be linked to increased demand for electrical products, the restoration of energy infrastructure, telecommunications projects, construction, industrial equipment, and automotive components.
At the same time, imports are growing significantly faster than exports. Over the first nine months, Ukrainian exports of wires and cables remained roughly at last year’s level—$1.065 billion—while imports rose by nearly a quarter.
By the end of 2025, Ukraine had imported $590.7 million worth of wires and cables, which was 24.3% higher than in 2024. In just the first nine months of 2026, the volume of imports had already approached the total for the entire previous year.
According to Experts Club, China ranked last among Ukraine’s 50 largest trading partners in terms of the balance of positive and negative attitudes among Ukrainians—in August 2026, the figure stood at minus 25.4 percentage points. The next lowest results were recorded for India and Hungary—minus 14.3 and minus 12.7 percentage points, respectively. This is evidenced by the results of the third wave of the study “Ukrainians’ Attitudes Toward Countries Around the World,” conducted by Active Group in collaboration with Experts Club, reports the Experts Club Information and Analytical Center.
The balance was defined as the difference between the shares of positive and negative assessments. Regarding China, 18.2% of respondents expressed a positive attitude, 43.6% a negative one, and another 33.9% a neutral one. Thus, China received the lowest score among all countries surveyed, despite the fact that in the first half of 2026, China was Ukraine’s largest trading partner with a trade volume of approximately $14.68 billion.
The top ten countries with the lowest scores also included Lebanon—minus 9.2 percentage points—and Poland—minus 2.3 percentage points. Serbia, Algeria, Libya, Vietnam, and Tunisia remained in the positive range, however, their scores were among the lowest among the countries surveyed: Serbia at plus 2.3 percentage points, Algeria at plus 2.2, Libya at plus 1.0, Vietnam at plus 9.4, and Tunisia at plus 11.0 percentage points.
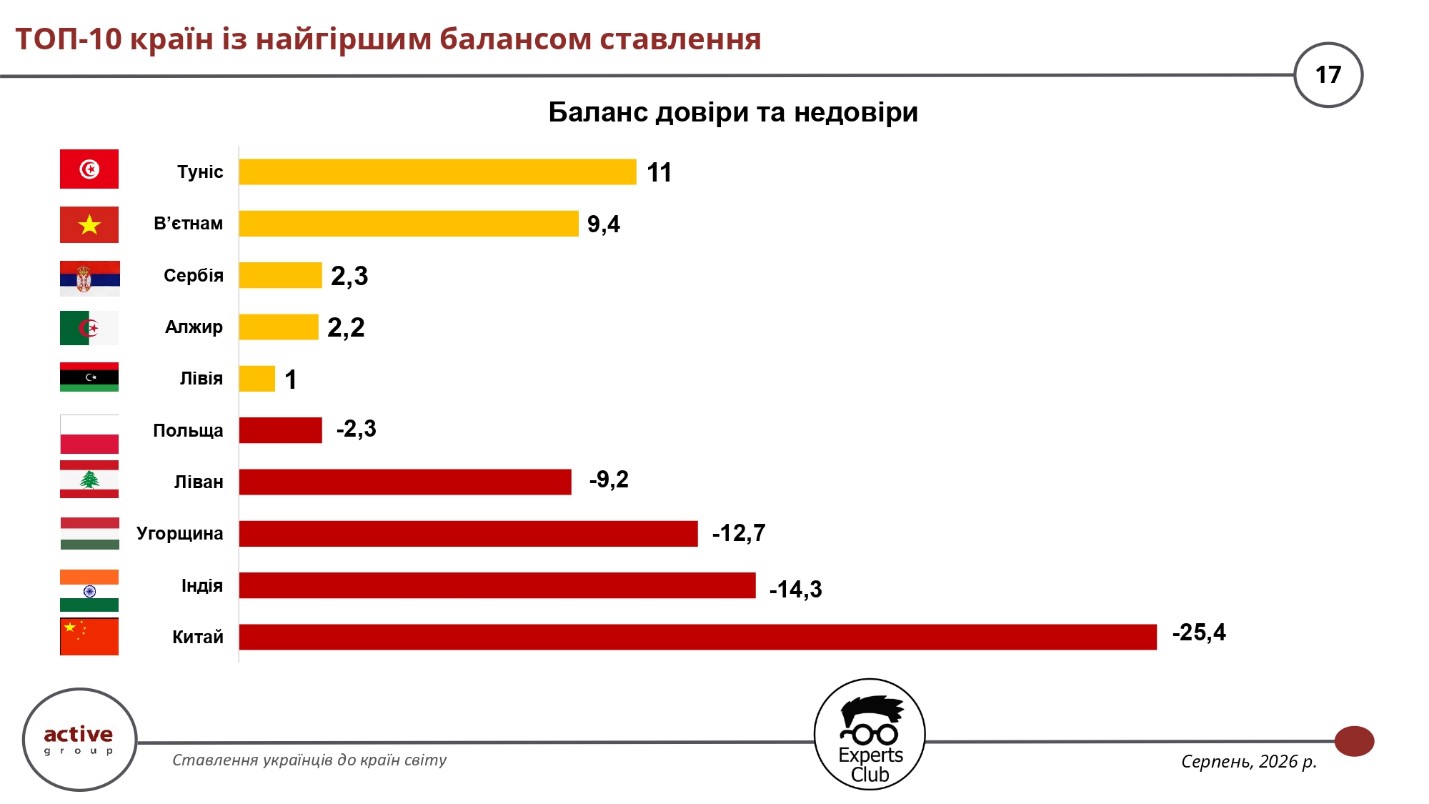
The shift in attitudes toward Poland was particularly noticeable. In March 2026, the balance of positive and negative assessments stood at +41.7 percentage points, whereas in August it fell to –2.3 percentage points. A positive attitude toward Poland was expressed by 34.6% of respondents, a negative one by 37%, and a neutral one by 25.4%. At the same time, Poland remains one of Ukraine’s largest trading partners and the largest market for Ukrainian goods exports among individual countries in the first half of 2026.
Maksym Urakin, founder of the Experts Club Information and Analytical Center, deputy director of the Interfax-Ukraine news agency, and candidate of economic sciences, noted that the results of the sociological survey should be analyzed in conjunction with actual trade figures.
“Second, we must be open to questions and inquiries from the media and the public. We also need to make use of our sociological research,” Urakin noted. In his view, systematic communication and the demonstration of concrete results of cooperation can help governments better explain the nature of bilateral relations to Ukrainian society.
Oleksandr Pozniy, director of the research company Active Group, highlighted the need to combine public awareness with the practical development of economic ties.
“We need to do more than just raise general awareness. We must expand cooperation with countries where we can achieve a positive trade balance,” Pozniy noted. He emphasized the role of business associations, economic institutions, and diplomatic missions in developing bilateral ties, especially with markets where Ukraine can increase its exports.
Overall, the survey results show that the scale of trade and economic ties does not always correspond to public attitudes toward the respective country. China stands out as the most striking example: it has the highest trade volume among individual partners, yet is simultaneously associated with the lowest ratings among Ukrainians.
The survey was conducted in August 2026 using self-administered online questionnaires in the SunFlowerSociology panel among 800 Ukrainian citizens aged 18 and older. The sample is representative by age, gender, and region; the maximum theoretical margin of error for indicators at the 50% confidence level is ±3.5 percentage points. This is the third wave of the study, following surveys conducted in August 2025 and March 2026.
ACTIVE GROUP, CHINA, EXPERTS CLUB, FOREIGN TRADE, HUNGARY, INDIA, international relations, POLAND, SOCIOLOGY, UKRAINE
European Union countries and the United Kingdom remain the top foreign economic priority for Ukrainians: in August 2026, 69.9% of respondents noted the need to prioritize the development of trade and economic relations with these countries. This is evidenced by the results of the third wave of the study “Ukrainians’ Attitudes Toward Countries Around the World,” conducted by Active Group in collaboration with the Experts Club Information and Analytical Center, according to the Experts Club Information and Analytical Center.
At the same time, support for the European direction has declined compared to previous waves of the study. In August 2025, 82.8% of respondents cited EU countries and the United Kingdom; in March 2026, 81.1%; and in August, 69.9%. Thus, over the course of a year, the figure decreased by 12.9 percentage points.
The trend regarding the United States is even more pronounced. In August 2025, 58.8% of respondents supported prioritizing the development of trade and economic relations with the United States; in March 2026, this figure was 59.2%, while in August it stood at 11.9%.
In August 2026, 8.4% of respondents named China as a priority, compared to 35.4% in March and 26.7% in August of the previous year. At the same time, China remains one of Ukraine’s most important trading partners, highlighting the discrepancy between the actual structure of foreign trade and public perceptions of the desired directions for its development.
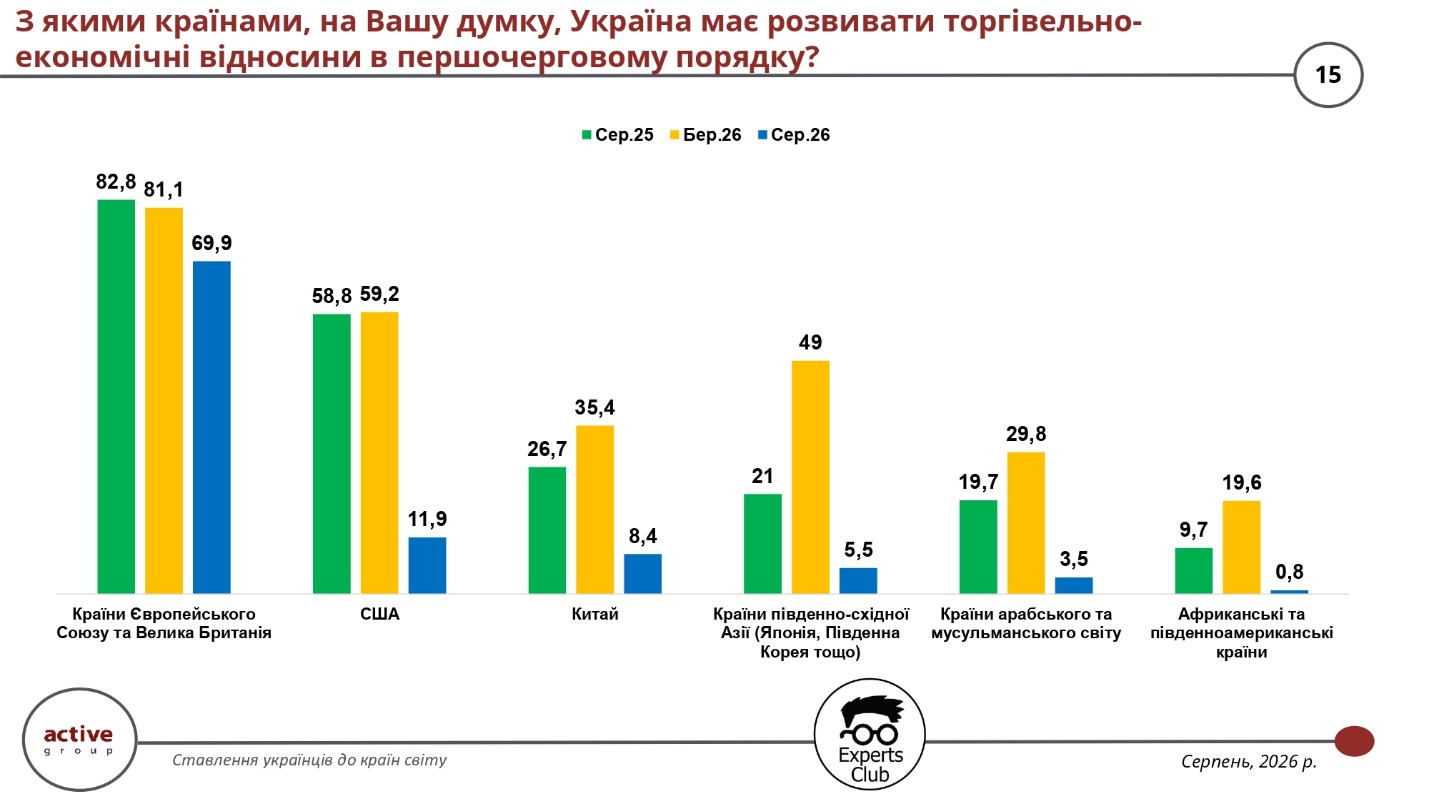
Another 5.5% of those surveyed in August advocated for prioritizing the deepening of economic relations with countries in Southeast Asia—Japan, South Korea, and other nations in the region. In March, this figure stood at 49%, and a year earlier—at 21%. Countries in the Arab and Muslim world were cited by 3.5% of respondents, compared to 29.8% in March, while African and South American countries were cited by 0.8%, compared to 19.6%.
Maksym Urakin, founder of the Experts Club information and analytical center, emphasized the need for more active communication between international partners and Ukrainian society.
“We need to regularly showcase concrete achievements and specific actions. Openness toward the media and the public helps strengthen relations, particularly trade relations,” Urakin noted.
According to him, sociological surveys can serve as a practical tool for government agencies, diplomatic missions, and the business community in determining the direction of bilateral relations.
Oleksandr Pozniy, director of the research firm Active Group, also highlighted the need to strengthen the economic component of international cooperation.
“We need to do more than just raise general awareness. Businesses and government agencies need to work more actively on developing bilateral relations,” Pozniy noted.
The survey was conducted in August 2026 using self-administered online questionnaires via the SunFlowerSociology panel. A total of 800 Ukrainian citizens aged 18 and older were surveyed. The sample is representative by age, gender, and region; the stated maximum theoretical margin of error is ±3.5 percentage points. Previous waves of the survey were conducted in August 2025 and March 2026.
ACTIVE GROUP, CHINA, EUROPEAN UNION, EXPERTS CLUB, FOREIGN TRADE, international relations, SOCIOLOGY, UKRAINE, UNITED KINGDOM, UNITED STATES
Poland became the largest gold buyer among the world’s central banks in January-August 2026, increasing its reserves by approximately 98 tonnes, according to an Experts Club analysis based on World Gold Council (WGC) data published on October 6.
In August, global central banks continued actively increasing their gold reserves, purchasing another 39 tonnes on a net basis compared with 23 tonnes a month earlier. However, the ranking of cumulative purchases since the beginning of the year differs noticeably from the results of August alone.
According to the WGC, the largest gold buyers in January-August 2026 included:
Poland – about 98 tonnes
China – about 80 tonnes
Uzbekistan – about 50 tonnes
Kazakhstan – about 36 tonnes
Czech Republic – about 14 tonnes
The National Bank of Poland retained first place thanks to the continuation of its large-scale precious metal accumulation programme. In August alone, the Polish central bank purchased another approximately 7.8 tonnes.
As a result, Poland’s gold holdings approached 648 tonnes, while the National Bank’s strategic target is 700 tonnes.
China ranks second. In August, the People’s Bank of China was the largest buyer in the world, increasing its reserves by as much as 20.2 tonnes.
In January-August, China purchased about 80 tonnes of gold, while its official gold reserves reached approximately 2,387 tonnes. Gold accounts for about 9% of the country’s international reserves.
At the same time, China has continued buying the precious metal for 22 consecutive months, making it one of the most consistent buyers among the world’s largest central banks.
Uzbekistan ranks third, having increased its gold reserves by approximately 50 tonnes since the beginning of the year. In August, the country purchased another approximately 7.8 tonnes. The total volume of gold in Uzbekistan’s reserves reached approximately 439 tonnes, with the precious metal accounting for about 90% of the country’s international reserves.
Kazakhstan ranks fourth, with purchases of approximately 36 tonnes over eight months. In August, the National Bank of Kazakhstan added about 7.4 tonnes, bringing its gold holdings to approximately 377 tonnes. Gold accounts for about 79% of the country’s international reserves.
The Czech Republic rounds out the top five largest buyers. The Czech National Bank purchased 14 tonnes since the beginning of the year, including approximately 1.7 tonnes in August. The country’s total gold reserves reached around 86 tonnes.
Notably, the Czech Republic has been increasing its gold holdings for 42 consecutive months, implementing one of the most consistent reserve expansion programmes among European central banks.
At the same time, Turkey and Russia became the largest gold sellers since the beginning of 2026. Turkey reduced its reserves by approximately 82 tonnes, although in August it returned to purchases and bought about 2.9 tonnes. Russia sold about 56 tonnes in January-August, including approximately 6.2 tonnes in August.
The World Gold Council notes that the continued presence of the same countries among active buyers indicates the long-term nature of gold accumulation policies. Monthly changes in purchase volumes largely reflect the implementation schedules of these programmes, market conditions and the liquidity needs of individual countries.
According to the WGC, in January-August 2026 central banks reported net purchases of approximately 170 tonnes of gold. At the same time, officially recorded changes in reserves do not necessarily reflect total public-sector demand, as some central bank transactions become known with a delay or are not disclosed.
The World Gold Council regularly tracks changes in central banks’ official gold reserves based on data from the International Monetary Fund, national regulators and other official sources. The WGC regards central bank demand as one of the key factors in the global gold market.
Central banks, CHINA, CZECH REPUBLIC, EXPERTS CLUB, GOLD, gold reserves, KAZAKHSTAN, POLAND, UZBEKISTAN, WORLD GOLD COUNCIL
In August 2026, central banks around the world increased their official gold reserves by a total of 39 metric tons in net terms, with the People’s Bank of China emerging as the largest buyer, according to an analysis by Experts Club based on data from the World Gold Council (WGC) published on October 6.
According to the WGC, the main buyers of gold in August were:
China — 20.2 metric tons
Poland — 7.8 metric tons
Uzbekistan — 7.8 metric tons
Kazakhstan — 7.4 metric tons
Turkey — 2.9 metric tons
Czech Republic — 1.7 metric tons
Bolivia—about 1 metric ton
Ghana—about 1 metric ton
China continued to purchase gold for the 22nd consecutive month. In August, the People’s Bank of China increased its gold reserves by approximately 20.2 metric tons—the largest monthly increase since October 2023.
From January through August, China purchased about 80 metric tons of gold. The country’s official gold reserves reached approximately 2,387 metric tons, accounting for about 9% of China’s total international reserves.
Despite China’s lead in August alone, Poland remains the largest buyer of gold since the beginning of 2026. The National Bank of Poland purchased about 7.8 metric tons in August and 98 metric tons since the start of the year. Poland’s gold reserves have grown to approximately 648 metric tons, approaching its stated target of 700 metric tons.
Uzbekistan increased its reserves by approximately 7.8 metric tons. Since the beginning of the year, the country has purchased about 50 metric tons of gold, bringing its total gold reserves to approximately 439 metric tons. Gold accounts for about 90% of Uzbekistan’s reserves.
Kazakhstan purchased about 7.4 metric tons of gold in August, bringing its total purchases since the beginning of the year to approximately 36 metric tons. The country’s gold reserves reached about 377 metric tons, or 79% of its international reserves.
Turkey returned to net purchases after three months of sales, acquiring about 2.9 metric tons. However, since the beginning of 2026, the country has remained a major net seller—the total reduction in reserves amounts to about 82 metric tons, with the bulk of sales occurring in the first quarter.
The Czech National Bank purchased about 1.7 metric tons, thereby extending its streak of net gold purchases to 42 consecutive months. Since the start of the year, the Czech Republic has added about 14 metric tons, increasing its reserves to 86 metric tons.
Overall, from January through August 2026, central banks worldwide reported net purchases of approximately 170 metric tons of gold.
The World Gold Council notes that the composition of the largest buyers remains relatively stable. This indicates that central banks are purchasing gold primarily as part of their long-term reserve management policies, while monthly fluctuations are linked to the timing of program implementation, market conditions, and individual countries’ liquidity needs.
For comparison: in July, central banks worldwide purchased 23 metric tons of gold on a net basis. Thus, in August, the volume of net purchases increased by approximately 70% month-over-month.
Official source: World Gold Council, Central Bank Gold Statistics, published on October 6, 2026.
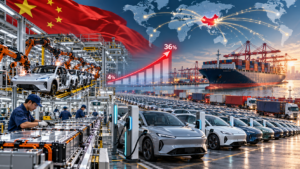
Over the past 25 years, China has increased its share of global automobile production approximately ninefold—from 4% in 2000 to 36% in 2025—transforming itself from a relatively small manufacturer into the world’s largest automotive hub. This was reported by the Experts Club information and analytical center, citing a study by the consulting firm Strategy Partners.
According to analysts’ estimates, around 2 million vehicles were produced in China in 2000, while by 2025 production exceeded 34 million vehicles per year. Thus, over a quarter of a century, the volume of Chinese automobile production increased approximately 17-fold.
China’s position strengthened particularly rapidly after 2010. The country not only formed the world’s largest domestic automobile market, but also created a large-scale manufacturing base covering virtually the entire value chain — from components and batteries to vehicle manufacturing and software.
One of the main factors behind the further growth of China’s automotive industry was the transition to electric vehicles and hybrid models. Chinese manufacturers gained strong positions in the new energy vehicle segment — NEV, which includes fully electric vehicles and plug-in hybrids.
At the same time, Chinese companies are actively increasing their presence abroad. China has become the world’s largest automobile exporter, while local manufacturers are expanding sales and creating their own production capacities in Europe, Asia, Latin America and other regions.
As a result, the structure of the global automobile market has also changed. While in the early 2000s it was shaped primarily by manufacturers from the United States, Japan and Western Europe, by the mid-2020s China had become the industry’s largest individual manufacturing hub.
The growth of China’s automotive industry is accompanied by the strengthening of its own national brands. BYD, Geely, Chery, SAIC, Great Wall Motor and other manufacturers are increasingly competing with European, American, Japanese and South Korean automotive groups not only in China’s domestic market but also in export markets.
China’s own battery manufacturing base has become a significant competitive advantage. Chinese companies hold leading positions in the global production of traction batteries, while the country controls a significant share of global production chains related to raw material processing and the manufacture of components for electric vehicles.
According to Strategy Partners, the transformation of China’s automotive industry demonstrates the country’s transition from a model of catching-up industrial development to technological leadership in certain segments of the industry.
If current trends continue, competition between Chinese and traditional global automakers will increasingly shift into the areas of electric vehicles, battery technologies, software, autonomous driving and production costs.
auto industry, AUTOMOBILE, CHINA, Electric vehicle, PRODUCTION



