
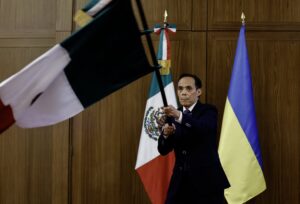
Mexico and Ukraine have significant potential for further expanding bilateral relations in the political, economic, scientific, and academic spheres, said Audencio Contreras González, Mexico’s Ambassador Extraordinary and Plenipotentiary to Ukraine.
“I am convinced that Mexico and Ukraine have significant potential for further strengthening bilateral relations. Our countries deserve broader, deeper, and more dynamic relations—ranging from open political dialogue based on mutual respect to mutually beneficial scientific, academic, and economic cooperation,” the ambassador said at a diplomatic reception in Kyiv marking the 216th anniversary of the start of Mexico’s struggle for independence.
The event was attended by Ukraine’s Deputy Minister of Foreign Affairs Mariana Betsa, as well as representatives of government agencies, the diplomatic corps, academic and business circles, civil society, and the Mexican community.
Contreras González noted that celebrating Mexico’s national holiday in Ukraine holds special significance.
“We celebrate it together with a people whom we sincerely admire and who, under extremely difficult circumstances, deeply value their identity, their sovereignty, and their right to independently determine their own future as an independent state living in peace, just as the Mexican people do,” the diplomat emphasized.
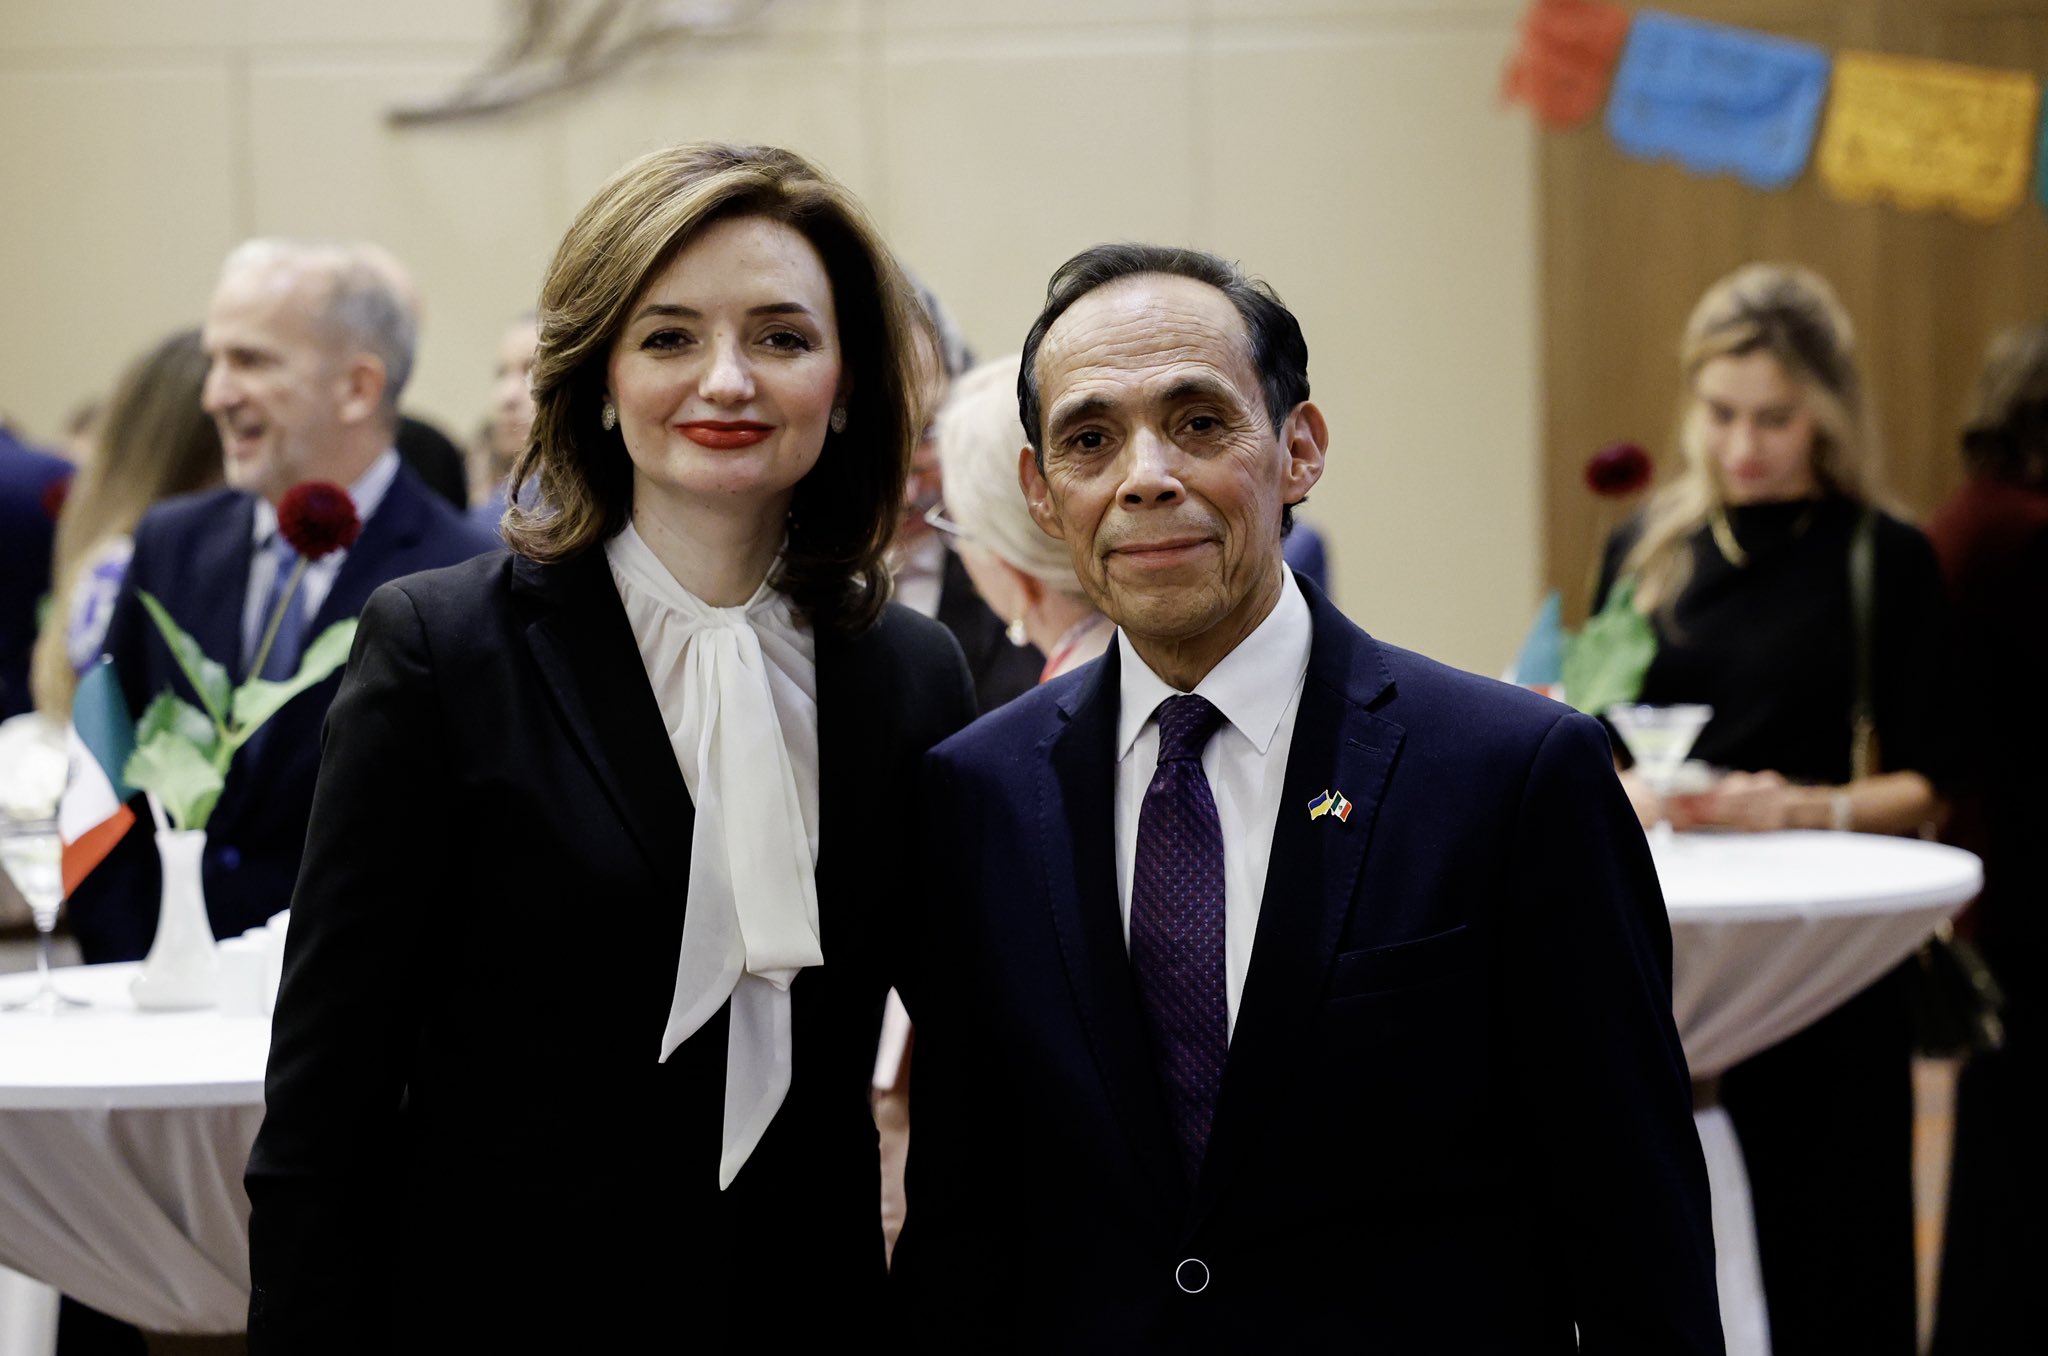
According to him, Mexico’s foreign policy is based on the constitutional principles of non-interference, the peaceful settlement of disputes, and the rejection of the use of force in international relations.
“It is precisely these principles that define our clear position on condemning the invasion of Ukraine, upholding international law, and promoting dialogue to achieve a just and lasting peace,” the ambassador stated.
He also emphasized the importance of cultural diplomacy and closer ties between the societies of the two countries, despite the significant geographical distance.
“Strengthening bilateral relations begins with our societies—which are geographically distant but share common values and traits, as well as a centuries-old history of statehood—getting to know one another better,” noted Contreras González.
During the reception, guests were introduced to elements of Mexican culture and national traditions, including music, cuisine, and the traditional decorative art of papel picado.
The ambassador expressed hope for the swiftest possible establishment of a just and lasting peace in Ukraine and the further strengthening of Ukrainian-Mexican cooperation.
Mexico recognized Ukraine’s independence on December 25, 1991, and diplomatic relations between the two countries were established on January 14, 1992.
The Embassy of Ukraine in Mexico City was opened in January 1999. Mexico initially maintained diplomatic relations with Ukraine through its embassies in Russia and later in Poland; in 2000, an honorary consulate began operating in Kyiv. The Permanent Embassy of Mexico in Ukraine began operations on May 1, 2005, and its official inauguration took place on June 20, 2005, during a state visit by Mexican President Vicente Fox.
Audencio Contreras González heads the Mexican Embassy in Ukraine and presented his credentials to the President of Ukraine on August 16, 2024.
Ukraine’s international reserves amounted to $48.7 billion at the end of August 2026, which is approximately $8.6 billion, or 15%, less than at the beginning of the year, according to an analysis by the Experts Club information and analytical center.
As of January 1, reserves stood at a record level of $57.3 billion, and by the beginning of February they had risen to $57.7 billion. After that, they declined for four consecutive months: to $54.8 billion as of March 1, $52 billion as of April 1, $48.2 billion as of May 1, and $45.7 billion as of June 1.
The main factors behind the decline were significant foreign exchange interventions by the National Bank, government debt payments, and uneven inflows of international financial assistance.
The situation changed sharply in June, when Ukraine received large tranches of external financing. Reserves increased by 12.1% over the month — to $51.27 billion. About $11.3 billion was credited to the government’s foreign currency accounts, including $6.82 billion from the EU and almost $4.5 billion through the World Bank.
In July, reserves remained almost unchanged, but in August they again decreased by approximately $2.5 billion, or 5%, to $48.7 billion.
In August, the NBU sold about $4.82 billion on the foreign exchange market, while $927.3 million was credited to the government’s foreign currency accounts. Ukraine also directed $721.8 million toward servicing and repaying government debt in foreign currency and paid $258.2 million to the IMF.
Net international reserves declined even more sharply over the month — by 6.9%, to $33.8 billion.
At the same time, the current level of reserves remains approximately 5.8% higher than a year ago, when they stood at about $46 billion as of September 1, 2025.
Experts Club founder and economist Maksym Urakin previously emphasized that the absolute size of reserves should not be regarded as a guarantee of currency security.
“Reserves at the level of $51.2 billion remain a significant foreign exchange buffer, but the absolute figure itself should not create an impression of complete protection. The sustainability of reserves depends on the regularity of international financing, the volume of NBU interventions, debt payments, and the economy’s ability to increase export revenues,” Urakin noted.
According to the NBU, the current level of reserves remains sufficient and provides financing for approximately four months of future imports.
Private landlords in the U.K. are increasingly selling properties or planning to exit the market amid rising financing costs and tax and regulatory burdens. The decline in supply is already leading to further increases in rent and is occurring at a time when the country is experiencing a change in government and a period of heightened economic uncertainty.
According to official data from the UK’s Office for National Statistics (ONS), in July 2026, the average private rent reached £1,393 per month, up 3.7% year-over-year. In England, the figure stood at £1,451, and in London, it was £2,317 per month.
A study by the Lomond agency network paints a similar picture, showing that British renters are already spending an average of 32.7% of their annual income on housing. According to the company’s methodology, the average rent was £1,369 per month, 4.3% higher than a year earlier. The discrepancy with ONS data is due to different sample sizes and calculation methods.
At the same time, supply from landlords is shrinking. A July survey by the Royal Institution of Chartered Surveyors (RICS) showed that new listings from landlords stood at -27%. Market participants report that landlords are reducing their portfolios or exiting the sector entirely. Despite more subdued demand from tenants, the balance of expectations for further rent increases rose to +28%.
A survey of more than 2,000 landlords conducted by Property118 in the second quarter paints an even bleaker picture: 40.2% had already reduced their portfolios over the previous two years, while only 6% had expanded them. Looking ahead to the next three years, 67.7% of respondents expect to sell at least part of their real estate holdings, while 27.1% intend to exit the market entirely.
One of the main reasons remains the high cost of borrowing. The Bank of England’s base rate stands at 3.75%, significantly higher than the levels seen during the era of cheap money prior to 2022. More than a third of the landlords surveyed will need to refinance their mortgages within the next year, which for many means switching from old, cheap fixed rates to significantly more expensive terms.
An additional factor has been the most significant reform of the private rental market in many years. As of May 1, 2026, the main provisions of the Renters’ Rights Act came into effect in England: Section 21 evictions without cause have been abolished, fixed-term leases are being replaced by a system of periodic tenancies, and landlords’ responsibilities have been strengthened. Starting in late 2026, the government will begin implementing a mandatory private rental housing registry, for which registration will incur a fee. Additional quality standards and a mandatory ombudsman will be introduced in the future.
That said, it would be incorrect to attribute the mass plans to sell properties solely to the new law. Pressure on the sector has been building for years due to tax changes, restrictions on mortgage interest deductions, and rising costs for insurance, repairs, and property maintenance. The new rules have merely become yet another factor forcing owners to reevaluate the economics of buy-to-let.
The situation in the housing market is unfolding against a backdrop of serious political instability in the United Kingdom. Keir Starmer stepped down as prime minister in the summer of 2026 after losing support within the Labour Party, and in September he decided to leave Parliament as well. He was succeeded by Andy Burnham, who became the UK’s seventh prime minister in a decade.
The new administration must simultaneously address the cost of living, the funding of social programs, and pressure on public finances. Yields on long-term British government bonds rose to approximately 5.26% in early September—a high not seen since 2008—which increases borrowing costs not only for the government but also, indirectly, for the entire economy. Investors are awaiting the new cabinet’s October budget and trying to understand how Burnham intends to finance his social and infrastructure initiatives.
It is still premature to speak of a full-blown economic crisis or recession in the UK. GDP grew by 0.4% in the second quarter of 2026, following 0.6% growth in the first quarter, though the pace of growth is slowing. Inflation accelerated again in July to 2.9%, unemployment reached 4.9%, and British businesses remain cautious about new investments.
It is precisely this combination of weak economic growth, high interest rates, and political uncertainty that is exacerbating problems in the rental market. The new cabinet aims to strengthen tenant protections, but as private landlords withdraw from the market, the opposite effect occurs: the fewer apartments available on the market, the greater the pressure on rent.
This presents a complex dilemma for the British government. If regulations and taxes continue to erode returns on private rentals faster than the government and institutional investors can build new housing, some of the costs of tenant protections may effectively be passed back to tenants in the form of higher rents and fewer housing options.
In the medium term, this could accelerate a structural shift in the British market: small private landlords will gradually be replaced by professional build-to-rent operators, pension funds, and investment funds capable of operating with lower returns and withstanding significantly stricter regulation.
Thus, the exit of British landlords is not an isolated real estate issue, but part of a broader picture: expensive capital, an economic slowdown, a crisis of political stability, and, at the same time, the government’s attempt to significantly tighten regulation of the housing market. For tenants, the main risk is not the mass disappearance of rental housing per se, but rather its continued rise in price and the shift in ownership from small landlords to large institutional investors.
About 11–12 million people living in the territory controlled by Ukraine may be below the poverty line if the World Bank’s latest estimate of the share of the poor population is applied to current demographic estimates.
According to data from the Experts Club information and analytical center and the World Bank’s spring study, *Monitoring Living Conditions in Ukraine*, the poverty rate in Ukraine in 2025 was estimated at 41.6% of the population, compared with 37% in 2024. This figure has effectively doubled compared with 2021.
Olha Holubovska, president of the All-Ukrainian Association of Infectious Disease Specialists, noted during a roundtable discussion at the Interfax-Ukraine agency that this is no longer merely a decline in living standards, but a population living below the established poverty line and increasingly unable to finance medical treatment independently.
To convert this indicator into absolute figures, it is necessary to take into account that there is no exact current population figure for Ukraine because of the war and the absence of a census. According to an estimate by the Ptoukha Institute for Demography and Life Quality Studies of the National Academy of Sciences of Ukraine, approximately 27–29 million people lived in government-controlled territory in the summer of 2026.
If the poverty rate of 41.6% is conditionally applied to this range, the result is between 11.2 million and 12.1 million people.
This figure is an estimate rather than the official number of poor people as of September 2026, since the World Bank indicator relates to 2025, while the population estimate relates to 2026. Nevertheless, it demonstrates the real scale of the problem.
The World Bank calculates the indicator based on the actual subsistence minimum published by the Ministry of Social Policy and household survey data. At the same time, the bank notes not only an increase in poverty but also growing inequality: the Gini coefficient rose from 0.44 in 2024 to 0.50 in 2025. The real earned income of the poorest 20% of households fell by more than 30%, while it increased among the wealthiest groups.
At the same time, the financial resilience of families continues to deteriorate. At the end of 2025, about 17% of households were already borrowing money to cover basic expenses, approximately the same proportion were unable to pay utility bills on time, and the share of families forced to sell property to finance everyday needs increased.
Families with children, pensioners, internally displaced persons and residents of frontline territories remain particularly vulnerable.
Ukrainian MP Lesia Zaburanna noted during the roundtable discussion that the consequences of rising poverty are already visible not only in frontline regions but also in Kyiv, where residents are reducing spending on food, medical treatment and providing for their children.
China was the only G20 country that did not support a number of provisions in the final document of the meeting of finance ministers and central bank governors of the “Group of Twenty,” held August 31–September 1, 2026, in Asheville, North Carolina.
As a result, instead of a joint communiqué agreed upon by all participants, the United States, as G20 chair, issued a chair’s statement. The official document from the U.S. Department of the Treasury states that it was endorsed by all G20 members present, except for China, which opposed four sections.
One of the main points of contention was the issue of global trade imbalances. The text, supported by the other countries, calls on nations to abandon non-market policies and practices that exacerbate imbalances. Countries with excessive and persistent external trade surpluses are urged to eliminate factors that constrain domestic consumption and create excessive dependence of economic growth on exports.
U.S. Treasury Secretary Scott Bessent stated after the meeting that China was the only dissenting participant. He called China’s current account surplus the largest and “unsustainable” and stated that a non-market economic model that constantly increases the supply of cheap export goods cannot be sustainable.
China also did not support provisions to expand the International Monetary Fund’s role in monitoring global economic imbalances. The other G20 members advocated for strengthening the IMF’s analysis, including an assessment of non-market policies, the factors driving external trade imbalances, and their impact on other economies.
Another point of contention was the Strait of Hormuz. The G20 statement expressed concern over ongoing disruptions to energy trade and emphasized the need for free, safe, and predictable shipping through the Strait of Hormuz and other key maritime routes. China opposed the entire relevant section of the document.
In addition, Beijing disagreed with the section concerning sovereign debt restructuring and the continued application of the G20’s Comprehensive Framework for Addressing the Debt Problems of Developing Countries. An official document from the U.S. Treasury Department explicitly states that China objected to paragraphs 4, 10, 11, and 13 of the statement.
Despite the lack of full consensus, the remaining 19 G20 members supported the approach to reducing global imbalances. Reuters notes that the issue has effectively turned into a debate over China’s export model, industrial subsidies, and the growing supply of Chinese products to global markets.
These disagreements come amid growing concerns from the U.S., the EU, and several other major economies regarding China’s manufacturing capacity and its expanding trade surplus. Western nations fear that a glut of Chinese industrial goods could intensify pressure on local manufacturers and increase dependence on specific supply chains.
The meeting in Asheville marked the second gathering of G20 finance ministers and central bank governors under the U.S. presidency in 2026. Key topics included economic growth, global imbalances, public debt, digital assets, financial literacy, and the state of the global financial system.
The G20 currently comprises 19 countries: Argentina, Australia, Brazil, the United Kingdom, Germany, India, Indonesia, Italy, Canada, China, Mexico, Russia, Saudi Arabia, the United States, Turkey, France, South Africa, South Korea, and Japan.
In addition, the European Union and the African Union are full members of the G20. Thus, following the African Union’s accession in 2023, the G20 effectively comprises 21 members—19 countries and two regional organizations.
The EU economy today faces challenges such as rising energy prices, fragmentation of the single market, complex administrative rules, and competition that is not always fair, said European Commission (EC) President Ursula von der Leyen.
“For a long time, the European economic model was based on several self-evident truths: cheap imported energy, open global trade, ever-wider access to the Chinese market, strategic protection from the U.S., and the West’s technological edge. These truths have disappeared,” the EC President stated while delivering a speech on Thursday in Paris at the annual “2026 Meeting of French Entrepreneurs” conference.
Von der Leyen sees the solution to these pressing problems as restoring entrepreneurs’ freedom to invest in the short term and, in the long term, making innovation, productivity, and scaling up the sustainable drivers of European economic growth.
The European Commission President outlined her prescriptions for healing the European economy.
The first priority is to simplify regulations and restore a level playing field. The goal is to reduce the administrative burden by 25% for all businesses and by 35% for small and medium-sized enterprises by 2029.
“However,” von der Leyen continued, “the demand for simplicity must be combined with the demand for fairness regarding foreign competition. This is particularly relevant to our relations with China. China is our major economic partner, and our position is clear and unwavering: to reduce risks, but not to sever ties. However, being a partner does not mean putting up with constant imbalances.”
She identified the financing of EU member states’ economies as the second priority. In her view, far too many projects remain stalled because the initial investment step is too risky, demand is too uncertain, or capital is too expensive. Of course, the EC President noted, these efforts cannot be financed solely through national budgets.
“But Europe has savings. Unfortunately, these savings are ‘idle.’ 10 trillion euros in household savings continue to sit in bank deposits, and a significant portion of European savings is invested outside our continent. Europe must now channel these funds to support its own businesses,” von der Leyen said.
Among other measures to strengthen the EU economy, she highlighted the comprehensive development and consolidation of the EU single market, reducing energy costs, the adoption of artificial intelligence as a “powerful driver of productivity,” and expanding free trade with international partners.



