
The Security Service of Ukraine dismantled an international drug smuggling ring operating out of Southern Europe and seized the largest shipment of cocaine since the start of the full-scale war, valued at approximately 70 million hryvnia. As part of a special operation in the Kyiv, Dnipropetrovsk, and Lviv regions, ten suspected members of an international drug syndicate were detained simultaneously, the SBU reported on August 12.
According to the security service, the group was involved in the distribution of wholesale shipments of cocaine, ecstasy, and other psychotropic substances imported from abroad. The SBU estimates the monthly revenue from these illegal activities at 15–20 million hryvnias.
Investigators believe a Kyiv resident was the organizer of the group’s activities in Ukraine. According to law enforcement, he recruited people to distribute drugs in various regions of the country.
During the first series of searches, SBU officers discovered approximately 2 kg of cocaine and other prohibited substances. Subsequently, more than 8 kg of cocaine and other potent substances were found in hiding places. The SBU estimated the total value of the seized substances at approximately 70 million hryvnias.
Thus, this amounts to approximately 10 kg of cocaine, not including the other seized substances. The SBU describes this shipment as the largest the agency has uncovered in Ukraine since the start of the full-scale war.
The ten detainees have been notified of charges under Part 3 of Article 307 of the Criminal Code of Ukraine—the illegal production, acquisition, storage, transportation, or sale of narcotic drugs and psychotropic substances committed by an organized group. They are currently in custody. The investigation has also established the possible involvement of three Ukrainian citizens currently in Spain in organizing the trafficking route. The issue of their extradition to Ukraine is currently being resolved.
The operation was carried out by SBU officers under the procedural supervision of the Dnipro District Prosecutor’s Office in Kyiv.
The SBU operation comes amid high cocaine supply in Europe. According to the 2026 European Drug Report, cocaine remains the second most prevalent illicit drug in Europe after cannabis. Approximately 4.3 million Europeans aged 15–64 have used it in the past year.
The EUDA notes that large shipments of cocaine continue to flow into Europe primarily from South America, with international criminal networks actively exploiting global commercial and maritime cargo flows. Large quantities of the drug are regularly seized at European ports.
Spain and the Western Balkans are a key component of the European system for combating international drug trafficking, primarily due to the activities of major organized crime groups in the region.
Europol notes that certain criminal networks linked to Montenegro are involved in organizing large-scale cocaine shipments from South America to European markets and have connections both within the EU and in Latin America.
In April 2026, Europol reported the arrest in Montenegro of one of the leading members of the so-called “Balkan Cartel.” Montenegrin law enforcement authorities charged a group of suspects in connection with the illicit trafficking of approximately 2,700 metric tons of cocaine between October 2024 and April 2026. The drugs had previously been seized during several operations in EU countries and South America.
The National Bank of Ukraine’s (NBU) increase of the monthly limit on non-cash foreign currency purchases by individuals from 50,000 UAH to 200,000 UAH may lead to a short-term rise in demand, but will not have a significant impact on the foreign exchange market, according to bankers surveyed by Interfax-Ukraine.
“In our opinion, there may be a certain surge in demand for non-cash foreign currency purchases in the first few days after the changes take effect,” said Emal Bakhtari, director of the financial instruments sales department at Raiffeisen Bank.
According to him, the proportion of customers who previously found the monthly limit of 50,000 UAH insufficient is relatively small. He suggested that the National Bank would, if necessary, smooth out short-term spikes in demand through currency interventions.
Serhiy Mamedov, Chairman of the Board of Globus Bank, also does not expect a proportional increase in demand following the fourfold increase in the limit. According to him, the limit determines only the maximum possible transaction amount, whereas the public’s purchase of cash foreign currency was not previously restricted by a similar monthly limit.
Currency liberalization in and of itself is unlikely to pose a threat to exchange rate stability at this point, Mamedov believes. Substantial international reserves give the regulator the ability to smooth out excessive exchange rate fluctuations, and the high discount rate should maintain the attractiveness of hryvnia-denominated instruments; however, this model depends to a large extent on the regularity of international financial assistance.
Anton Kurinny, a dealer in OTP Bank’s Global Markets Department, also forecasts an increase in demand for foreign currency but does not expect this to have a significant impact on the interbank market, where importers’ needs and the shortfall in export proceeds remain the more significant factors.
According to Kurinnyi, additional demand may also arise in the cash market following the increase in the daily limit for currency withdrawals from 100,000 UAH to 200,000 UAH, since the cash exchange rate hovers close to interbank quotes and is sometimes even lower than them.
Mamedov identified the worsening balance between goods imports and exports as a separate risk. According to the data he cited, in January–July 2026, goods imports totaled $58.1 billion, while exports amounted to $24.1 billion, resulting in a trade deficit of approximately $34 billion.
According to the banker, a further increase in the trade imbalance and problems with maritime logistics could intensify structural demand for foreign currency and the need for NBU interventions, while the dynamics of reserves will also depend on the volume of international financing.
Oleksandr Pecheritsyn, director of the analytical research department at Raiffeisen Bank, assesses the risk of a significant outflow of household savings from hryvnia deposits and domestic government bonds (OVGZ) into foreign currency as limited.
In his view, hryvnia-denominated deposits and domestic government bonds remain more attractive than holding savings in foreign currency cash, and the growth in household investments in domestic government bonds was primarily driven by their higher returns relative to the expected devaluation of the hryvnia.
At the same time, Pecheritsyn suggests that raising the limit on non-cash foreign currency purchases could reduce the volume of so-called “technical” foreign currency deposits, which households opened for three months to subsequently obtain foreign currency.
“If the volume of such deposits declines and banks need foreign currency resources to conduct active operations—particularly lending—interest rates on foreign currency deposits may rise slightly. At the same time, this will not necessarily become a general trend across the entire banking sector,” he noted.
Raising the daily limit on cash foreign currency withdrawals could theoretically also boost public interest in foreign currency deposits; however, according to Pecheritsyn’s assessment, given the population’s average incomes and savings, this effect will not be widespread and will not lead to a significant increase in such deposits.
As previously reported, effective August 11, the NBU increased the monthly limit on the public’s purchase of non-cash foreign currency from 50,000 hryvnias to 200,000 hryvnias and extended it to include the purchase of non-cash bank metals and securities issued by foreign entities.
The regulator also raised the daily limit on cash withdrawals by individuals from foreign currency accounts in Ukraine and abroad from 100,000 hryvnias to 200,000 hryvnias and eased a number of other foreign exchange restrictions for individuals and legal entities.
The National Bank stated that the new package of easing measures will not pose risks to the stability of the foreign exchange market and has already been factored into the updated macroeconomic forecast, which projects an increase in international reserves to nearly $70 billion by 2026.
Poland’s Deputy Minister of the Interior, Maciej Duszkiewicz, highlighted the contribution of Ukrainians to the functioning of the Polish economy. He made this statement during an appearance on Polsat News.
Polsat News reports that Duszczyk believes that in many cases, the absence of Ukrainians is noticeable. “If it weren’t for Ukrainian citizens, we’d be waiting 10 minutes for the bus instead of five. After all, they fill the gaps in the Polish labor market. That’s why a certain part of the Polish economy depends on refugees from Ukraine. Generally speaking, these are Ukrainians living in Poland, and we need to reiterate this more and more often, because if a situation were to arise where one day all Ukrainians united and refused to go to work, the Polish economy would grind to a halt,” he said.
He also criticized the Law and Justice (PiS) party’s proposal to deport unemployed men of draft age from Ukraine. In this context, the figure of 3,000 people has been mentioned in public discussions. “Three thousand is a small group. Let me remind you that 900,000 people have been mobilized in Ukraine, so this is no help at all. In fact, those who aren’t working in Poland are either caring for their disabled children or are people who were wounded on the front lines and are undergoing rehabilitation in Poland,” he said.
When asked whether refugees will begin returning to Ukraine once the war ends, Dushchyk replied that “this is a process we’ve observed in other countries, and it’s very easy to predict.”
“Sometimes, those who say, ‘I’m staying,’ end up leaving because something happens. And those who say, ‘I’ll leave as soon as the war ends,’ end up staying. Of course, these trends change with each passing month, as the roots they put down in the host society—in this case, Polish society—grow deeper and deeper. “If someone has enrolled their children in school, they’re learning Polish; if a person is working in the labor market, the likelihood that they’ll return to Ukraine without a strong incentive to do so is practically very low,” he noted.
In the first half of 2026, foreign citizens purchased 51,627 residential properties in Spain, which is approximately 4% more than during the same period last year and marks the highest figure in the history of relevant statistics from Spanish registries.
The second quarter proved to be the most active: foreigners concluded over 26,800 transactions, and their share of all registered residential property purchases reached 15.98%—a historic high, according to data from the Colegio de Registradores de España.
At the same time, the overall Spanish housing market, on the contrary, cooled slightly in the second quarter. The number of transactions fell by 5.7% compared to the previous quarter—to 167,934 thousand, with sales of new-construction properties dropping by 11.5% to 34,919 thousand. Thus, foreign demand strengthened against the backdrop of declining overall buyer activity.
British citizens remained the largest group of foreign buyers in the first half of the year. They purchased 3,567 properties, though the number of transactions fell by approximately 10% year-over-year.
Dutch citizens were close behind, with 3,489 purchases—a 12% increase compared to the first half of 2025. The gap between the two largest groups was just 78 transactions. In the second quarter alone, British buyers concluded 1,843 transactions, while Dutch buyers concluded 1,830.
Official statistics for the second quarter show that British buyers accounted for 6.99% of all foreign transactions, while Dutch citizens accounted for 6.94%. Germans came in third with a share of 6.11%.
Germany retained its third place among the largest foreign markets, although demand from German buyers declined slightly over the first half of the year—by approximately 2%. At the same time, the number of purchases by Italian citizens rose by 11%, by Polish citizens—also by 11%, by French citizens—by 3%, and by Irish citizens—by 6%. Belgian demand, on the other hand, fell by approximately 16%.
Thus, the structure of foreign demand in Spain is becoming increasingly diversified. Ten years ago, British buyers were significantly ahead of other nationalities, whereas now the gap between the United Kingdom, the Netherlands, Germany, and the next group of European buyers has narrowed considerably. In the first quarter of 2026, for example, British and Dutch buyers accounted for 6.82% and 6.56% of foreign purchases, respectively.
The most detailed official report from the Colegio de Registradores for the first quarter of 2026 shows that Ukrainians ranked 10th among foreign buyers, accounting for 3.08% of all foreign real estate transactions; Ukrainian citizens accounted for approximately 765 purchases over the three-month period.
In terms of the number of transactions at the start of the year, Ukrainians trailed behind the British, Dutch, Moroccans, Germans, Italians, French, Romanians, Poles, and Belgians, but outpaced citizens of China, Sweden, Ireland, the United States, and Russia.
By comparison, Chinese nationals accounted for 2.69% of foreign purchases, while Russians accounted for only 1.44%. Thus, the share of Ukrainians was more than twice that of Russians.
The full official report for the first half of the year, broken down by nationality, has not yet been presented in the registrars’ brief press release; therefore, the exact number of purchases made by Ukrainians over the six-month period should be interpreted with caution. If the share remains at around 3%, this could amount to approximately 1,500 transactions for January–June; however, this is an estimated figure, not a separately published official statistic.
The opposite trend is observed among Russian citizens. In the first half of the year, Russians purchased fewer than 1,000 properties, and the number of transactions fell by more than 20% year-over-year.
In the second quarter, the share of foreign buyers reached 32.27% in the Balearic Islands and 31.03% in the Valencian Community. At the same time, the share of foreign buyers increased in all of the country’s autonomous communities.
In the first quarter, a high concentration of foreign demand was also observed in the Canary Islands—22.78% of transactions—and in the Murcia region—21.73%. In the province of Alicante, foreigners accounted for about 44.7% of home sales, and in Málaga—more than a third.
Overall, over the past 12 months, foreign citizens have purchased approximately 99,400 residential properties in Spain, meaning the market has come very close to the 100,000-mark for foreign transactions per year.
The growth in international demand is occurring alongside a rapid rise in real estate prices. The average registered housing price in the second quarter reached a new all-time high of 2,487 euros per square meter, increasing by 2.4% quarter-over-quarter and 9.2% year-over-year. The resale index showed even more significant year-over-year growth—16.7%.
Thus, despite a decline in the total number of transactions in Spain, foreign demand continues to strengthen. At the same time, the market is becoming less dependent on traditional British and German buyers: the role of the Netherlands, Poland, and a number of other European countries is growing, while Ukrainians remain among the most prominent nationalities in the Spanish real estate market.
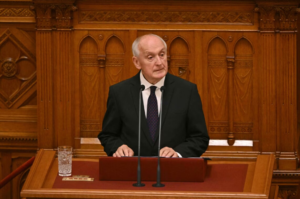
The Hungarian parliament has elected former Supreme Court president András Baka as the country’s new president, marking another important stage in the restructuring of Hungary’s political system following the end of Viktor Orbán’s 16-year rule.
On 11 August, 140 MPs voted for the 73-year-old lawyer, while six voted against. Representatives of the opposition Fidesz party did not participate in the vote, protesting against the early termination of the powers of the previous president, Tamás Sulyok. Baka is due to officially take office on 19 August.
Baka’s election is primarily of political and institutional significance. The president of Hungary does not head the government or determine the country’s economic or foreign policy, but can serve as a constitutional counterweight to the parliamentary majority and the cabinet. This function is particularly important now, as Prime Minister Péter Magyar’s Tisza party holds a constitutional majority in parliament and is carrying out sweeping changes to the institutions shaped under Orbán.
Baka fits well into this political arrangement. From 1991 to 2008, he served as a judge at the European Court of Human Rights, and in 2009 parliament elected him president of the Supreme Court of Hungary. His mandate was terminated early in early 2012 after he publicly criticised the Orbán government’s judicial reforms. The European Court of Human Rights subsequently found violations of his right of access to a court and freedom of expression.
Therefore, Baka’s return to one of the country’s highest public offices almost 15 years later has clear symbolic significance. It demonstrates the new authorities’ intention to distance themselves from the institutional model of the Orbán era while simultaneously making the independence of the judiciary one of the central themes of the political transformation.
“For Hungarian society, this is much more than an ordinary change of president. After sixteen years of dominance by a single political force, any large-scale restructuring of state institutions will inevitably be perceived differently by society. For supporters of change, this is an opportunity to restore the system of checks and balances, while for a significant proportion of Fidesz supporters, what is happening may look like political revenge by the new authorities,” said Oleksandr Poznii, an expert at the Experts Club analytical centre and co-founder and director of the Active Group research company.
According to Poznii, the key test will be the ability of the new institutions to demonstrate genuine independence from Péter Magyar’s government.
“Baka’s main task is not to become the president of the victorious party. If the new head of state can truly distance himself from the government and act as an arbiter between different political groups, this will be an important signal to society. Otherwise, Hungary risks seeing not the dismantling of the former model of concentrated power, but merely a change in the political force controlling that model,” Poznii noted.
The sociologist also draws attention to the high degree of political polarisation in Hungarian society. In such a situation, the significance of the presidential office is determined not so much by the scope of its formal powers as by the trust that different groups of the population place in the head of state.
“In countries with strong political polarisation, symbolic institutions can be far more important than the text of the constitution might suggest. The president may not manage the economy or foreign policy, but he can either reduce the level of conflict in society or, conversely, become another participant in that conflict. Therefore, the main measure of Baka’s success will not be the number of laws he blocks, but whether he can be perceived as the president of all Hungarians,” Poznii emphasised.
Following his election, Baka himself stated that under the previous authorities the system of checks and balances had effectively ceased to function, but stressed that political change should not turn into revenge against supporters of the former government. He also declared his intention to represent citizens with different political views.
Hungary is a parliamentary republic, meaning that the real centre of executive power is located not in the presidential palace, but in the government.
Under the Fundamental Law of Hungary, the president is the head of state, embodies the unity of the nation and is responsible for safeguarding the democratic functioning of state institutions. At the same time, the president has no executive power of his own and does not head the ministries.
Nevertheless, his powers extend beyond purely ceremonial functions. The president signs laws adopted by parliament and, before signing, may return a law to MPs once for reconsideration. If he considers a document to be contrary to the Fundamental Law, he may refer it to the Constitutional Court.
Following parliamentary elections, the president proposes a candidate for prime minister to parliament. He also formally appoints ministers upon the recommendation of the head of government, performs a range of personnel and representative functions, and represents the Hungarian state in foreign relations.
Thus, the head of state can delay certain decisions by the parliamentary majority or initiate a constitutional review of them, but cannot independently determine the country’s political course.
The prime minister, by contrast, is the effective head of the executive branch. The government is the principal body of executive power and public administration, while the prime minister determines its overall political course. It is the prime minister who forms the government team, directs the work of the cabinet and, through the parliamentary majority, implements the principal budgetary, economic, social and foreign policy decisions.
Therefore, the key political figure in Hungary remains Péter Magyar, who came to power following Tisza’s victory in the April parliamentary elections. The party won two-thirds of the seats in parliament, ending Orbán’s 16-year period of uninterrupted rule.
After coming to power, Magyar began seeking the replacement of the heads of a number of state institutions associated with the previous system of government. One of the most notable episodes was the early termination of President Tamás Sulyok’s term of office.
For the new authorities, Baka’s election is particularly symbolic because of his long-standing conflict with the Orbán system. The former president of the Supreme Court is effectively returning to the highest level of state politics after the defeat of the political force under which he lost his judicial post.
At the same time, this is precisely where one of the main risks facing Hungary’s new political system emerges. Tisza holds a constitutional majority and therefore has exceptionally broad powers to change laws and institutions. The new authorities must consequently dismantle the mechanisms created under Orbán while simultaneously proving that they are not replacing them with their own party control.
This is the paradox of Hungary’s new political arrangement: Magyar has obtained an exceptionally strong position thanks to his parliamentary majority, while Baka is expected to embody a limit on the excessive concentration of power.
For Ukrainian audiences, Hungary’s transformation also has foreign policy significance. Following Orbán’s defeat, Budapest’s position on Ukraine has become less confrontational, although Magyar does not present himself as an unconditional supporter of Kyiv and continues to link some bilateral issues to the situation of the Hungarian minority in Transcarpathia.
Therefore, the ultimate criterion for determining whether Hungary has entered a new political era will be not only the departure of officials from the Orbán era, but also whether the new authorities can establish a system of institutions capable of functioning independently of whichever party controls parliament and the government.
According to Serbian Economist, Belgrade continues to account for a significant portion of Serbia’s construction and investment activity, while the development of the real estate market in other regions of the country remains noticeably less uniform.
In the second quarter of 2026, the Belgrade region was the only region in Serbia where construction activity grew in real terms, with growth reaching 51% compared to the same period last year.
This is evidenced by data from the Republic Statistical Office of Serbia (RZS), published on August 10.
In all other regions of the country, construction activity declined in the second quarter. In Vojvodina, the value of completed construction work at constant prices fell by 2%; in Šumadija and Western Serbia, by 27.5%; and in Southern and Eastern Serbia, by 32.3%.
Thus, the latest quarterly statistics indicate a sharp widening of the gap between the capital and the rest of Serbia in terms of the volume of construction work.
Across Serbia as a whole, the value of construction work in the second quarter rose by 20.6% in current prices compared to April–June 2025.
Building construction grew particularly rapidly. In constant prices, the volume of work in this segment increased by 32.4% year-over-year, while for other construction projects, including infrastructure, the figure decreased by 7.1%.
Vera Yegorova-Tolsta, founder of the Belgrade real estate agency VIDOVSTAN, believes that the concentration of capital in the capital is a sustained trend and is linked not only to local demand but also to Belgrade’s investment appeal.
“Belgrade remains a distinct market within Serbia. It is home to jobs, foreign businesses, major infrastructure projects, and a significant portion of investment demand. Therefore, new projects in the capital’s prestigious neighborhoods typically find buyers faster than similar properties in smaller cities. At the same time, within Belgrade itself, the differences between neighborhoods and the quality of projects are becoming increasingly noticeable,” says Yegorova-Tolstaya.
In practice, this means that nationwide Serbian statistics do not always fully reflect the situation for an apartment buyer in the capital. The growth in supply across the country may be accompanied by persistently high prices in Belgrade’s most popular neighborhoods.
Yegorova-Tolstaya has also previously noted that the Serbian market remains stable, but demand is becoming more selective, and the quality and location of properties are becoming increasingly important.
It will be possible to definitively assess the extent to which construction activity in the second quarter affected apartment prices in Belgrade after the publication of the latest quarterly report from the RGZ Real Estate Price Register.
https://t.me/relocationrs/3427



