
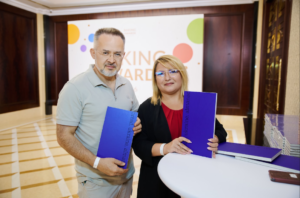
After several years of work, the publication “Bread. Ukraine. Almanac” has been released in Ukraine — a bilingual informational and historical art book dedicated to Ukrainian bread, its role in history, culture, everyday life and the modern food industry.
At the heart of the publication is an attempt to show that the concept of Ukrainian bread is much broader than the familiar product on the everyday table. For some, it is the taste of childhood and a family recipe; for others, it is palianytsia, regional baked goods or bread from a local bakery. At the same time, behind these familiar images stand the history of the development of agriculture, milling and breadmaking, folk traditions and the modern large-scale food industry.
The almanac traces how bread accompanied Ukraine and Ukrainians through different historical periods. It was preserved in family memory and rituals, became an image in cinema, poetry, photography and other forms of art, and with the development of industry turned into an important part of a large production complex.
A special place in the publication is devoted to the dramatic pages of Ukrainian history. The authors address the tragedy of the Holodomor, during which bread became a symbol of the very right of a person to life. It acquired a new symbolic meaning after the beginning of the full-scale war. One of the best-known examples was the word “palianytsia,” which in 2022 became a distinctive linguistic marker of Ukrainian identity.
At the same time, “Bread. Ukraine. Almanac” tells not only about the past. Considerable attention is paid to modern breadmaking, artisanal technologies, regional traditions and the development of the industry. In the book, bread appears simultaneously as an everyday product, a cultural phenomenon, the result of the work of the agricultural and food sectors, and part of the country’s economic history.
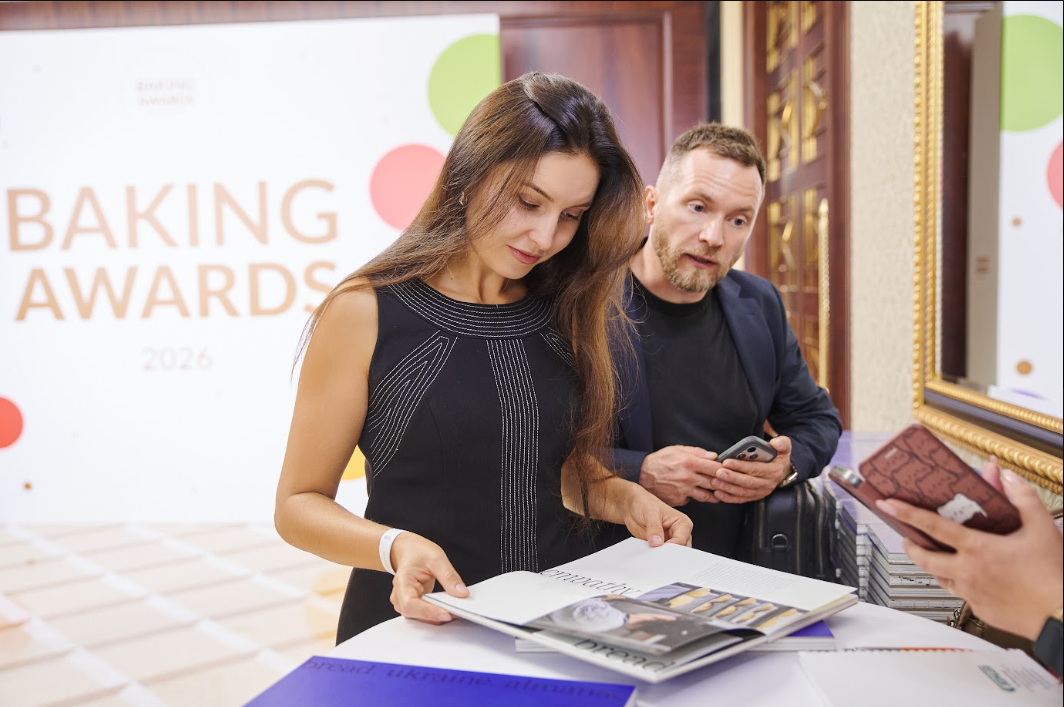
At the same time, the authors do not attempt to give a single definition to the concept of “Ukrainian bread.” The book is structured as a collection of different stories, each of which reveals a separate part of this topic — from old mills and family recipes to industrial bakeries, modern technologies and the artistic interpretation of bread.
This approach leaves the reader room for further exploration of the topic: after one piece, one can turn to an old Ukrainian film; after another, one can study regional baked goods, the history of milling, traditional technologies or modern Ukrainian breadmaking in greater detail.
“Bread. Ukraine. Almanac” has been prepared in Ukrainian and English, and is therefore intended not only for a Ukrainian but also for an international audience. The publication can be used as a presentation book about Ukraine, its history, gastronomic culture and one of the country’s most important industries.
The almanac is designed as a modern collectible art book. A distinctive color palette, unconventional layout, archival and contemporary visual materials create a separate visual language for the publication and emphasize its gift-book character.
The premiere of the almanac took place during Baking Awards 2026. The publication was presented by Yurii Duchenko, President of the All-Ukrainian Association of Bakers, and Rodion Rybchynskyi, Director of the “Flour Millers of Ukraine” Union.
The print run of “Bread. Ukraine. Almanac” is limited. Detailed information about the publication and the possibility of ordering it are available on the official “Bread. Ukraine” website.
The partners of the “Bread. Ukraine. Almanac” edition were the All-Ukrainian Association of Bakers and the “Flour Millers of Ukraine” Union. The industry organizations unite enterprises of Ukraine’s breadmaking and flour-milling industries and work to develop the domestic market, increase the competitiveness of Ukrainian products and expand their presence abroad. Among their areas of activity are strengthening Ukraine’s export potential, promoting Ukrainian flour, bakery products and other grain-processing products in foreign markets, developing international contacts and facilitating the participation of Ukrainian producers in specialized international events.
Global grain trade in the 2026/27 agricultural year (July–June) will total 505.8 million metric tons, which is 3.5% less than last year, according to a forecast by the FAO (Food and Agriculture Organization of the United Nations).
According to the organization’s monthly grain report, the new estimate is 3.5 million metric tons lower than the previous forecast made in September. “This reflects a downward revision of wheat and corn export forecasts, driven primarily by shipping challenges through the Black Sea and insufficient capacity on alternative transport routes,” the report states. “The upward revision to the barley trade forecast only partially offsets the lost trade volumes in corn and wheat.”
Forecasts for corn exports from the EU were lowered due to reduced supply from Ukraine resulting from logistical difficulties. At the same time, an increase in export supply from Australia has allowed for an upward revision of the forecast for barley trade, a significant portion of which will be shipped to China.
The improved forecast for wheat exports from Kazakhstan has not fully offset the decline in shipments from Russia and Ukraine.
According to the forecast, international rice trade will decline by 2.2% in calendar year 2026; however, it may increase by 1.7% in 2027, reaching 61.2 million metric tons. “In 2027, a recovery in import demand is forecast for most regions; however, the availability of sufficient domestic stocks in East Asian countries suggests that the downward trend in their purchasing volumes may continue for the third consecutive year,” the document states.
According to the FAO forecast, the wheat harvest in 2026 will total 813.9 million metric tons, 3.3% less than last year, while the total grain output will be 2.979 billion metric tons (2.1% less).
Ukraine and Uzbekistan are introducing a “transport visa-free regime,” which provides for the abolition of permits and related quotas for direct and transit international freight truck transportation between the two countries.
A corresponding protocol between the governments of Ukraine and the Republic of Uzbekistan amending the bilateral Agreement on International Road Transport was signed on September 30, 2026, according to the Ukrainian Embassy in Uzbekistan.
According to the diplomatic mission, the preparation of the document took nearly a year.
The main change will be the simplification of direct and transit freight transport by eliminating the need to obtain permits, as well as quantitative quotas for such transport. This regime, by analogy with other agreements in the field of international road transport, is referred to as “transport visa-free travel.”
For Ukrainian and Uzbek carriers, this will mean the removal of one of the administrative barriers to organizing freight transport between the two countries and transit through their territories.
The embassy expects that the liberalization of road transport will contribute to the restoration of Ukraine’s trade and economic ties with Uzbekistan, which were partially disrupted due to logistical problems following the start of full-scale Russian aggression.
The agreement takes on particular significance amid the restructuring of Ukraine’s foreign trade and the search for alternative transport corridors to Central Asia.
“The removal of bureaucratic barriers should soon facilitate the restoration of full-fledged trade and economic ties between Ukraine and the Republic of Uzbekistan,” the embassy noted.
The diplomatic mission also described the new agreement as one of the steps toward Ukraine’s return to Central Asian markets via new logistics routes.
The protocol, signed on September 30, amends the existing intergovernmental Agreement between Ukraine and Uzbekistan on international road transport. Specifically, it concerns the liberalization of direct and transit freight transport by road. The embassy’s statement does not provide for the abolition of other customs, border, or transportation procedures required for the international transport of goods.
Original source – Embassy of Ukraine in the Republic of Uzbekistan.
According to Fixygen, the cryptocurrency market ended the week of September 28 through October 2 mostly in positive territory: Bitcoin (BTC) once again surpassed the $86,000 mark, Ethereum (ETH) approached the $2,750 mark, and investors shifted their focus to the outlook for U.S. interest rates and the continued inflow of institutional capital into digital assets.
As of Friday morning, Bitcoin was trading at around $86,500, having risen nearly 3% over the previous 24 hours. During trading, prices approached $87,000. For comparison, on September 25, BTC was trading at around $84,400.
Ethereum traded in the range of $2,740–$2,750 on Friday, compared to approximately $2,670 at the start of the week.
Cryptocurrencies were supported by a decline in expectations regarding further monetary tightening by the U.S. Federal Reserve. Following the release of U.S. labor market data, which came in weaker than expected, Treasury yields fell, and market estimates suggest the likelihood of a Fed rate hike in October has decreased significantly.
The liquidation of short positions served as an additional driver of growth. As Bitcoin rose to $87,000, the volume of liquidations in the cryptocurrency market exceeded $300 million over the course of a single day.
This week marked a continuation of a strong third quarter for cryptocurrencies. From July through September, Bitcoin rose by more than 40%, and Ethereum by more than 70%, although both of the largest cryptocurrencies remain below their all-time highs set in 2025.
Amid the market recovery, Citigroup raised its 12-month price forecasts for the largest cryptocurrencies. The forecast for Bitcoin has been raised to $113,000 from the previous $82,000, and for Ethereum to $3,028,000 from $2,024,000. The bank attributes the revision to increased activity in the cryptocurrency market, changes in the macroeconomic situation, and the resumption of capital inflows into cryptocurrency ETFs.
A key development this week was the continued convergence of the traditional banking system with stablecoins. On September 28, Citigroup and the U.S. crypto exchange Coinbase announced an expansion of their partnership in the field of digital payments.
The companies intend to integrate Citi’s banking infrastructure with Coinbase’s cryptocurrency payment infrastructure. Corporate clients will be able to use solutions for accepting payments in stablecoins and converting them into traditional currencies. The partnership is primarily focused on international settlements and payments operating 24/7.
Another trend of the week was the continued development of rules governing how institutional investors handle crypto assets.
On October 1, the U.S. Securities and Exchange Commission (SEC) proposed a new framework for the custody of digital assets by investment advisors and regulated funds. This proposal aims to establish a specific regulatory framework for the custody of cryptoassets and to define the conditions under which financial institutions may hold digital assets.
Thus, the U.S. regulator is gradually shifting from regulating the crypto market primarily through enforcement to establishing specific rules for digital assets.
At the same time, regulations in the United Kingdom are changing. On September 30, the Financial Conduct Authority (FCA) began accepting applications from cryptocurrency companies wishing to operate under the UK’s new regulatory regime for digital assets.
Companies must submit their applications by February 28, 2027. The UK’s new cryptocurrency market regulatory framework is set to take effect in October 2027.
The market’s attention remains firmly focused on the tokenization of traditional financial assets. One of the key developments in late September was an agreement between the New York Stock Exchange and Blockchain.com to expand access to tokenized U.S. stocks and ETFs.
The parties signed a memorandum of understanding that provides for the possibility of granting Blockchain.com clients access to tokenized securities traded on a dedicated digital platform operated by the NYSE. The project’s implementation will depend on obtaining the necessary approvals from regulatory authorities.
Another notable change is taking place in the stablecoin market. Tether is preparing to bring USDT back into the Bitcoin ecosystem more than a decade after the token effectively left it. This is expected to happen using the new RGB protocol, which allows for the issuance of digital assets based on the Bitcoin network.
At the same time, the stablecoin market continues to face regulatory and sanctions-related risks. A report published this week by the U.S. Senate Permanent Subcommittee on Investigations highlighted the widespread use of USDT by entities linked to Iran to circumvent sanctions. In response, Tether announced its cooperation with U.S. authorities and reported that it had frozen nearly $550 million in USDT linked to Iran in 2026.
Thus, the week highlighted several trends that are currently shaping the crypto industry: the recovery in the value of major digital assets, the return of institutional demand, the integration of stablecoins into traditional banking payments, and the gradual establishment of a comprehensive regulatory framework in the U.S. and the U.K.
In the coming weeks, key factors for the market will remain the Fed’s decisions, the dynamics of U.S. Treasury yields, capital flows into cryptocurrency ETFs, and further U.S. regulatory decisions.
Provided demand remains strong, the $87,000–$90,000 range remains the next key level for Bitcoin. However, cryptocurrencies’ high sensitivity to interest rates and macroeconomic data poses a risk of sharp corrections following strong growth in the third quarter.
Sources: Reuters, SEC, FCA, Coinbase, CoinDesk.
According to the Serbian business media outlet Parametar, Croatia is claiming property worth over $2.7 billion located in Montenegro that remained there following the breakup of Yugoslavia. And this is by no means limited to the well-known training sailing ship “Jadran.”
This was stated by Croatian Minister of Foreign and European Affairs Gordan Grlić Radman during a visit to Montenegro. Zagreb has documentation regarding property that ended up on Montenegrin territory and was sold or transferred to other owners after the breakup of Yugoslavia.
Among these, the minister specifically mentioned military ships, submarines, and a military hospital.
The “Jadran” has become the most well-known part of the dispute. The training sailing ship was built in the 1930s and was used by the Yugoslav Navy. The vessel is currently in Montenegro, while Croatia insists on its return.
But the property dispute is only part of a much broader list of Zagreb’s demands on Podgorica.
The Croatian Ministry of Foreign Affairs lists the following among the unresolved issues:
– the return of the “Jadran” and the settlement of other property claims;
– compensation for former Croatian prisoners of the Morin camp;
– the search for 14 people who are still considered missing in action following the war of the 1990s;
– the investigation and prosecution of war crimes;
– the return of property belonging to Croatian families in Montenegro and the conclusion of protracted court proceedings;
– the preservation of a memorial plaque at the site of the former Morin camp;
– renaming the swimming pool in Kotor named after Zoran Hopčević;
– resolving the maritime border between the two countries.
These issues take on particular significance in light of Montenegro’s EU accession negotiations.
Croatia is already using its status as an EU member state to block the closure of certain negotiation chapters. In September, a planned intergovernmental conference had to be postponed after Zagreb refused to agree to the closure of several chapters.
Currently, Croatia is blocking the closure of chapters related to transport policy, foreign policy and security, the judicial system and fundamental rights, as well as justice, freedom, and security.
Podgorica hopes to conclude negotiations and become the 28th member of the European Union in 2028. However, this date is not guaranteed: the consent of EU member states is required for progress and final accession.
At the same time, Croatia is currently the main source of bilateral demands on Montenegro, which directly affect the negotiation process. There is currently no comparable official set of claims from other EU member states.
This creates a rather interesting situation: the closer Montenegro gets to the EU, the greater the significance of long-standing disputes dating back to the breakup of Yugoslavia.
And Croatia’s property claims, totaling more than $2.7 billion, are now becoming not only a matter of relations between Zagreb and Podgorica but also a potential factor capable of influencing the timing of Montenegro’s accession to the European Union.
Global food prices rose by 1.5% in September compared with the revised August figure, driven by higher prices for grains, vegetable oils, and sugar, according to the monthly report by the FAO (the Food and Agriculture Organization of the United Nations).
The FAO Food Price Index stood at 136 points in September, 2 points (1.5%) higher than the revised August figure. The index was 5.8% higher than in September 2025 but 15.1% below the peak reached in March 2022.
The Cereal Price Index rose by 5.1% compared with August and by 17.2% compared with September 2025. On a monthly basis, global wheat prices rose by 6.3%, reaching their highest level since August 2023. However, the report notes that daily prices declined somewhat toward the end of the month.
“This increase was primarily driven by logistical challenges in the Black Sea region, which prompted importers to turn to alternative suppliers. Drought conditions in some parts of North America ahead of the winter wheat planting season were an additional factor driving price increases,” the document states.
Global corn prices rose 5.6% compared to August and reached their highest level in the past three years. This is due to a projected decline in supply caused by lower-than-expected yields in the U.S. and reduced export capacity in Brazil. “Trade disruptions in the Black Sea region have led to a reduction in corn export supply, while ongoing uncertainty regarding shipping through the Strait of Hormuz has fueled concerns about high costs for fuel, fertilizers, and freight. This exerted additional upward pressure on commodity prices, especially for biofuel production, particularly corn,” the report states.
The price index for all types of rice rose by 1.4% amid higher prices for long-grain rice (indica) due to concerns about weather conditions and a seasonal decline in supply.
The vegetable oil price index in September was 0.9% higher than in August and 18.3% higher year-over-year. The increase was primarily driven by rising global prices for palm oil, which fully offset the decline in sunflower oil prices. Sunflower oil prices fell for the third consecutive month amid forecasts of abundant supply in the Black Sea region; however, ongoing logistical difficulties and limited capacity on alternative export routes prevented prices from falling further, according to the report.
Soybean and canola oil prices remained virtually unchanged over the month.
The meat price index in September fell by 1.1% compared to the revised August figure and is in line with the level from a year ago. This was driven by weaker poultry and pork prices, while beef and lamb prices remained generally stable. Global poultry prices fell amid a significant volume of export supply from Brazil and weaker import demand from the EU. Pork prices declined amid substantial supply in major exporting countries. Australian beef export prices fell amid intensifying competition in the global market, while prices in Brazil rose as demand from the U.S. picked up. Lamb prices remained virtually unchanged.
The dairy price index in September was 0.1% lower than in August. On a year-over-year basis, prices fell by 19.1%.
“The decline in cheese prices was almost entirely offset by rising prices for dry milk, while butter prices remained virtually unchanged,” the report states. “Prices for nonfat dry milk were 33.1% higher than last year’s level, and prices for dry milk rose in all major exporting countries due to sustained import demand, particularly from Asian countries.”
The sugar price index in September was 6.1% higher than in August and 14.7% higher than in September 2025. The index has been rising for the third consecutive month and is at its highest level since April 2025.
The increase is primarily driven by the projected decline in global sugar supply during the 2026/27 agricultural season. In particular, it is expected that a reduction in planted acreage and unfavorable weather conditions during the growing season in the EU will lead to a decline in the sugar beet harvest. A decline in sugar production is forecast for Thailand, and the outlook for India is also less favorable. In addition, delays in the harvest in Brazil’s key sugarcane-growing region due to heavy rains have exerted additional upward pressure on global sugar prices.
The FAO Food Price Index is a weighted average that tracks changes in international prices for five major food commodity groups.



