
The European Union did not support Ukraine’s request for early disbursement of additional funding in 2026 and emphasized that the allocation of funds will depend directly on Kyiv’s implementation of agreed-upon reforms, according to the Financial Times, citing a letter from European Commissioners Valdis Dombrovskis and Marta Kos to Verkhovna Rada Chairman Ruslan Stefanchuk.
This summer, Ukraine estimated its additional defense needs at approximately $27 billion and approached the European Commission with a proposal to advance a portion of the funds from the two-year €90 billion Ukraine Support Loan program (€60 billion earmarked for defense, €30 billion for direct budget support). According to the program’s terms, up to €45 billion is to be made available to Ukraine in 2026, with the remaining €45 billion to follow in 2027.
According to the FT, European Commissioners have made it clear that access to funding is contingent upon fulfilling an agreed-upon list of commitments. Specifically, this involves the elimination of VAT exemptions for small international parcels, the introduction of taxation rules for digital platforms, and proper financial monitoring of politically exposed persons (PEPs)—changes to which have raised concerns in Brussels as a deviation from the anti-corruption agenda. According to the publication’s assessment, meeting these requirements will pave the way for Kyiv to receive approximately 34 billion euros in support as early as 2026.
At the same time, the European Commission emphasized that the rejection of the request for an early advance payment does not mean a curtailment of financial assistance. On October 1, the parties announced that they had agreed on sources of funding for budgetary and defense needs through the end of 2026, noting that there is no unfunded financial gap for the current year.
In addition, on October 2, the European Commission transferred another tranche of 2.9 billion euros to Ukraine as part of the Ukraine Facility program. The total amount of aid to Kyiv from the EU and its member states since the start of Russia’s full-scale invasion has reached 227.4 billion euros.
According to Experts.news, the largest banks are beginning to move traditional bank money onto the blockchain, creating a potential competitor to the USDT and USDC stablecoins. In the UK, Barclays, HSBC UK, Lloyds Banking Group, Monzo, Nationwide, NatWest, and Santander are already testing tokenized deposits, while in the U.S., Citi is simultaneously building infrastructure that allows corporate clients to work with stablecoins via Coinbase.
In effect, two models for the future of digital money are taking shape. The first involves the use of independent stablecoins issued by companies such as Tether and Circle. The second transfers existing funds from bank accounts onto the blockchain.
British banks took an important step in this direction on September 24, 2026. The industry association UK Finance announced the completion of the first real-world customer transactions involving tokenized deposits in pounds sterling as part of the Great British Tokenized Deposit (GBTD) project.
Participants in the project include Barclays, HSBC UK, Lloyds Banking Group, Monzo, Nationwide, NatWest, and Santander.
The banks conducted two live mortgage refinancing transactions. The tokenized funds were automatically blocked until the terms of the agreement were met, after which the payment was processed without any additional manual steps.
Another test involved a purchase on a consumer marketplace. It demonstrated the ability to transfer tokenized bank funds between customers of different banks via a shared infrastructure.
The main difference between this model and USDT or USDC lies in the legal nature of the money.
A tokenized deposit is not a separate cryptocurrency. It is a digital representation of regular money that the customer already holds in a bank account.
If there is 1,000 GBP in a bank account, the bank can theoretically represent this amount in the digital infrastructure as a corresponding amount of tokenized pounds. In this case, the bank continues to bear the obligation to the customer, and the funds themselves retain the legal status of a bank deposit.
A stablecoin works differently.
USDT is issued by Tether, and USDC by Circle. The user effectively exchanges regular money for a digital token, the value of which the issuer commits to maintaining at the level of the corresponding fiat currency through reserve assets.
Therefore, a tokenized bank deposit and a stablecoin may look the same on the blockchain, but economically they are different instruments.
Banks have a significant advantage—their existing system of trust, regulation, and customer relationships.
UK Finance explicitly states that tokenized deposits must retain the regulatory guarantees of traditional bank deposits while acquiring the properties of digital money—programmability, faster settlements, and the ability to automatically execute payments once specified conditions are met.
It is precisely this programmability that could become one of the technology’s main advantages.
For example, when purchasing real estate, funds can be automatically transferred to the seller only after the transaction has been registered. Payment to a supplier can be made after confirmation of delivery. In financial transactions, the transfer of a security and payment for it can occur almost simultaneously.
As a result, the number of intermediate transactions is reduced, as is the risk that one party will fulfill its obligations while the other does not.
The next phase of the British project will involve using tokenized deposits to settle payments for digital assets. GBTD participants plan to link customers’ tokenized funds to digital securities.
In this way, banks are attempting to create within the regulated financial system the opportunities that blockchain and stablecoins initially offered outside of it.
However, it is still too early to write off USDT and USDC.
The scale of the existing stablecoin market is incomparable to the banks’ experiments. According to CoinGecko data as of October 3, the market capitalization of USDT alone is approximately $184 billion, while that of USDC is approximately $74 billion.
The total stablecoin market already exceeds $300 billion.
Stablecoins are particularly strong in international money transfers. They operate around the clock, can move between different blockchains and platforms, and do not require the sender and recipient to be served by the same bank.
This is where a fundamental problem arises for the traditional banking system.
If a significant portion of international payments shifts to USDT, USDC, or other stablecoins, banks will have to compete for payment flows that previously passed almost entirely through the banking infrastructure.
Furthermore, a massive shift of funds from bank deposits to stablecoins could potentially reduce banks’ deposit base, which is used to lend to the economy.
The Bank of England is explicitly taking this risk into account as it develops new regulations for digital currencies.
In June 2026, the Bank of England published draft rules for systemic stablecoins. The regulator proposed a model under which at least 40% of a systemic stablecoin’s reserves must be held directly at the Bank of England, while up to 60% may be invested in short-term UK government bonds.
Restrictions on the amount of stablecoins that individual users and companies can hold are also being considered for a transitional period.
However, the Bank of England does not propose banning stablecoins. On the contrary, its strategy envisions the coexistence of several types of digital currencies.
In the future, traditional bank deposits, their tokenized versions, regulated stablecoins, and a potential central bank digital pound could all be used simultaneously.
Therefore, real competition is developing not so much between banks and cryptocurrencies as between different models of digital money.
Citi’s strategy is illustrative in this regard.
On September 28, Citi and Coinbase announced an expansion of their partnership, which effectively combines traditional banking infrastructure with stablecoins.
Coinbase has selected Citi’s Virtual Account Wallet to power Coinbase Virtual Accounts. Incoming traditional currency can be automatically converted into stablecoins.
Conversely, Citi’s corporate clients will be able to accept payments in stablecoins via the Spring by Citi payment platform and the Coinbase Payments infrastructure.
Coinbase accepts the digital payment and facilitates its conversion, after which Citi processes the settlement in traditional currency as a bank.
This is particularly important for corporate clients: the company gains the ability to accept stablecoins without having to build its own infrastructure for storing and managing crypto assets.
According to Citi, this solution potentially gives its corporate clients access to over 150 million stablecoin holders worldwide.
Thus, major banks are adopting different strategies.
British banks such as Barclays, HSBC, Lloyds, NatWest, and others are creating tokenized versions of their own deposit funds.
Citi, meanwhile, is developing a banking blockchain infrastructure and building a bridge between traditional money and existing stablecoins.
In the long run, these models may not displace one another but rather share the market.
Tokenized deposits have a natural advantage within the banking system—for payroll, corporate payments, mortgages, lending, and securities transactions.
Stablecoins are stronger in areas where round-the-clock cross-border transfers, interoperability between different platforms, and the ability to freely move digital money between blockchains are particularly important.
But for banks, this issue is becoming strategic. If they fail to migrate deposits and payments to a programmable digital infrastructure, a significant portion of the new market could go to Tether, Circle, Coinbase, and other companies in the crypto industry.
That is why competition between USDT, USDC, and tokenized bank deposits could become one of the key drivers of the global financial system’s development in the coming years.
Sources: UK Finance, Bank of England, Citi, Coinbase, CoinGecko.
DTEK and Dragon Capital have established an investment hub to attract funding for Ukraine’s energy sector, whose funding needs are estimated at $100 billion, the energy holding company announced.
“The hub brings together representatives from the public and private sectors to develop concrete and practical solutions that will help attract more investment into Ukraine’s energy sector,” commented DTEK CEO Maksym Timchenko, whose remarks were quoted in a statement posted by the energy holding company on its Telegram channel on Friday.
It is noted that more than $100 billion may be needed to rebuild Ukraine’s energy sector and create new facilities, and the Investment Hub is intended to facilitate the attraction of these funds.
“The main goal is to make Ukraine’s energy system more modern and resilient in order to strengthen the country’s energy security,” DTEK emphasized.
As previously reported, DTEK invested 101.7 billion hryvnias in Ukraine’s energy sector from 2022 to 2025.
In total, Rinat Akhmetov’s SCM Group, which includes DTEK, has invested over $4.3 billion in Ukraine since the start of the full-scale war, of which approximately $1 billion has gone toward rebuilding facilities destroyed by Russia.
SCM is currently launching a global initiative called “Invest in Ukraine,” calling on international businesses to invest in Ukraine today, without waiting for the war to end.
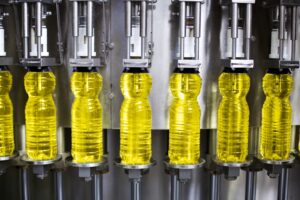
The agricultural trading company “A.V. Export Import” (Chortkiv, Ternopil Oblast) plans to commission the first phase of a new oil refining plant in the Chortkiv-West Industrial Park (Ternopil Oblast) by the end of this year; the investment in the project totaled 25 million UAH, according to Dmytro Kysilevsky, deputy head of the parliamentary committee on economic development.
“Installation of equipment for the first phase has been completed at the Chortkiv-West Industrial Park. Work is currently underway to install the building’s exterior elements and landscape the surrounding area. Production is scheduled to begin at the end of 2026,” he wrote on his Facebook page on Friday.
According to him, the first phase of the plant consists of an oil refining shop and a bottling shop. Production capacity is 50 metric tons of refined oil per day.
The second phase involves an investment of 50 million UAH in the construction of a facility for processing sunflower seeds into oil. The plant plans to employ 123 workers.
Kisilevsky noted that the project’s investor, the company “A.V. Export-Import,” became the first participant in the Chortkiv-West Industrial Park. In addition, negotiations regarding the relocation of two enterprises from the Zaporizhzhia and Kharkiv regions are currently in the final stages.
He also added that in 2026, the Chortkiv-West Industrial Park, with financial support from the Ukrainian-Swiss UCORD project, began construction of water supply networks, while the State Fund for Regional Development of Ukraine is financing the development of the park’s electrical networks.
Currently, the Chortkiv community is preparing an application to participate in the state program for co-financing the development of industrial park infrastructure. The funds are planned to be allocated for the construction of an access road and a road interchange within the industrial park.
The Chortkiv-West Industrial Park was registered in October 2019. It is located on a plot of land covering 87.7 hectares. The declared operating period is 30 years.
According to YouControl, “A.V. Export-Import” reported 1.5 million UAH in net profit and 178.4 million UAH in net revenue in the first quarter of 2026.
The company’s owners are Daria Lupashko-Gurevich, a Bulgarian citizen (50%); Andriy Snezhko, a resident of Kyiv (25%); and Valeriy Yureskul, a resident of the Mykolaiv region.
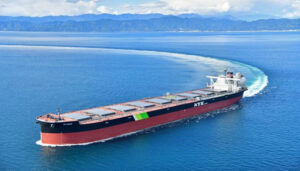
The Japanese government is considering a new package of sanctions against Russia, which could include restrictions on vessels belonging to the so-called “shadow fleet,” as well as further tightening of export controls.
This was reported on October 2 by the Japanese newspaper Yomiuri Shimbun, citing several government officials.
According to the publication, Tokyo is considering joining efforts to further intensify sanctions pressure on Russia amid new restrictions being imposed by European countries.
One of the main targets of the new package could be vessels of the Russian “shadow fleet,” which are used to transport oil and petroleum products in circumvention of Western sanctions.
The Japanese government is also considering expanding the list of goods whose export to Russia is prohibited or restricted, as well as further strengthening export control mechanisms.
The final composition of the new package and the date of its implementation have not yet been officially announced.
As of October 2, the new package has not yet been published in the Japanese Ministry of Finance’s official list of current sanctions. Nor has a corresponding decision been announced in the country’s Ministry of Foreign Affairs’ statements.
The last major package of additional Japanese sanctions related to the war in Ukraine was announced on September 12, 2025.
At that time, Japan imposed asset freezes on 47 Russian organizations and nine individuals. Restrictions were also imposed on five individuals and one organization that Japanese authorities link to the annexation of Crimea, the destabilization of eastern Ukraine, and the Russian occupation of Ukrainian territories.
In addition, three organizations from third countries were subject to the restrictions.
The package included not only asset freezes but also expanded export restrictions. Japan has banned supplies to certain Russian organizations and companies from third countries that, according to the Japanese authorities, are linked to the Russian military-industrial complex or help circumvent the restrictions.
Thus, if the new package is adopted, it will mark the first significant expansion of Japanese sanctions against Russia in over a year.
A focus on the “shadow fleet” will mean a further alignment of Japan’s sanctions regime with the approach taken by the EU, the United Kingdom, and other G7 countries, which in recent years have been actively imposing restrictions on vessels involved in the transport of Russian energy resources.
At the same time, Japan maintains a unique position regarding Russian energy resources. The country continues to import LNG from the “Sakhalin-2” project, viewing these supplies as a crucial element of its own energy security.
The official list of Japan’s current sanctions has been published by the country’s Ministry of Finance. The new restrictions will take effect after the government adopts a corresponding decision and publishes the documents required by Japanese law.
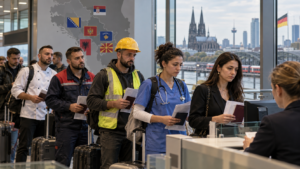
Germany will reduce the annual limit for admitting workers under the Westbalkanregelung programme from 50,000 to 25,000 people, which will affect citizens of six Western Balkan countries at once — Albania, Bosnia and Herzegovina, Kosovo, Montenegro, North Macedonia and Serbia, the Experts Club analytical center reports, citing data from the German government and the Federal Employment Agency.
The new limit is to take effect from 2027 and effectively means a return to the level that existed before June 2024, when Germany doubled the annual quota from 25,000 to 50,000 people.
Westbalkanregelung has been in force since 2016 and is a special mechanism providing citizens of the Western Balkans with access to the German labor market.
The main difference between the programme and many other channels of labor migration is that it applies not only to qualified specialists. A citizen of one of the six countries can obtain permission to work in Germany if they have a specific job offer from a German employer, while recognition of professional qualifications in Germany is generally not a mandatory requirement.
Regulated professions, such as doctors, remain an exception, as separate qualification recognition requirements apply to them.
It is precisely because of this that Westbalkanregelung has become one of the most accessible channels of legal labor migration from the region to Germany.
At the same time, there are no separate national quotas for Serbia, Albania, Bosnia and Herzegovina, Kosovo, Montenegro or North Macedonia. The limit is common to all six countries, so reducing it to 25,000 people will mean increased competition among applicants from across the region.
Demand for the programme already significantly exceeds supply.
According to Germany’s Federal Employment Agency, demand continued to grow after the quota was increased to 50,000 places. In December 2025 alone, the agency had to reject around 18,000 applications because the annual limit had already been exhausted.
At the same time, the scale of labor migration from the Western Balkans significantly exceeds the figures directly related to this programme.
The Federal Employment Agency notes that, among the relevant category of foreign workers, citizens of Albania, Bosnia and Herzegovina, Kosovo, Montenegro, North Macedonia and Serbia account for around a quarter of all employees in Germany covered by social insurance who have a residence permit or permanent residence based on employment.
Thus, over the past decade, the Western Balkans have become one of the important external sources of labor for the German economy.
“The German decision is interesting because it comes against the backdrop of two opposing trends. On the one hand, the German economy is experiencing a structural shortage of workers and is interested in attracting foreign labor. On the other hand, the state is tightening migration controls and reducing one of the most accessible employment channels for citizens of the Western Balkans,” said Maksym Urakin, founder of the Experts Club analytical center.
According to Experts Club, the most immediate consequence of the quota reduction may be increased competition for permits among citizens of the six countries.
If demand already exceeded supply with a limit of 50,000 places, halving the quota could potentially increase waiting times and the share of applicants who will not be able to use the programme in a particular calendar year.
At the same time, the Westbalkanregelung mechanism itself is not being closed. Citizens of the region will still be able to work in Germany through other labor migration channels provided for by law if they meet the established requirements.
Germany’s decision is also of particular interest from the demographic perspective of the Western Balkans themselves. Serbia, Bosnia and Herzegovina, North Macedonia, Albania, Montenegro and Kosovo have for many years been sources of labor migration to EU countries, primarily Germany, Austria and other Western European economies.
For the countries of the region, the mass outflow of the working-age population has a dual effect. Remittances from citizens working abroad support household incomes and domestic consumption, but at the same time emigration increases labor shortages within the Balkan economies themselves.
The outflow of medical personnel, construction workers, drivers, technical specialists, service-sector employees and other categories that are in demand both in Germany and in the domestic labor markets of the countries of the region remains particularly sensitive.
“For the Western Balkans, Germany’s decision may somewhat reduce one of the channels of labor outflow, but it is unlikely by itself to substantially change migration processes. The difference in wages and employment opportunities between Germany and most of the region remains the main economic driver of migration,” Urakin believes.
The reduction of Westbalkanregelung is part of a broader adjustment of the German government’s migration policy. Among its objectives, the cabinet lists reducing irregular migration, expanding the list of safe countries of origin, increasing the number of returns and introducing stricter regulation of migration flows.
At the same time, Berlin continues to emphasize the need for legal migration for the German labor market.
This creates a certain paradox: Germany is restricting one of the most in-demand regional channels of labor migration at precisely the moment when population ageing and staff shortages are forcing the German economy to search more actively for workers outside the country.
For the Western Balkans, the consequences are also ambiguous. The quota reduction potentially reduces opportunities for new labor emigration, but at the same time may somewhat reduce pressure on national labor markets, which themselves face worker shortages.
The key indicator of the effectiveness of the decision will be how quickly the new quota of 25,000 permits is exhausted after its introduction. If demand remains at its current level, Westbalkanregelung will effectively become a significantly more competitive channel of access to the German labor market.
The Westbalkanregelung programme has been in force in Germany since 2016 and applies to citizens of Albania, Bosnia and Herzegovina, Kosovo, Montenegro, North Macedonia and Serbia. In mid-2024, the annual limit was increased from 25,000 to 50,000 people. The German government has decided to limit it again to 25,000 permits per year.
Sources: Federal Government of Germany, Federal Employment Agency of Germany.
EMPLOYMENT, GERMANY, Labor market, MIGRATION, Western Balkans



