
According to Fixygen, Strategy remains the world’s largest corporate holder of bitcoin. As of August 23, the company held 840,447 BTC, or about 4% of the maximum possible supply of the first cryptocurrency.
At a BTC price of $77,004, its Bitcoin reserves were valued at $64.72 billion, while Strategy’s market capitalization stood at approximately $49.6 billion.
At first glance, it appears that investors value the entire company at less than the value of the Bitcoin it holds.
However, this comparison is incomplete. In addition to BTC, Strategy held $6.69 billion in dollar-denominated assets, but at the same time had approximately $6.75 billion in debt and $14.97 billion in preferred stock, which ranks higher than common shareholders in the capital structure.
After accounting for these liabilities, Strategy itself estimated the net value of its reserves at approximately $49.68 billion—nearly the same as its market capitalization.
This is precisely why the company’s mNAV ratio as of August 23 stood at around 1.01x. In other words, the huge premium that investors previously paid for the opportunity to gain indirect exposure to bitcoin through MSTR has virtually disappeared.
This is a fundamental shift in Sailor’s model: Strategy remains the world’s largest Bitcoin treasury, but its stock is increasingly valued as a financial entity with BTC, debt, and expensive preferred equity, rather than as “Bitcoin at a premium.”
The volume of capital investments in Ukraine from January through June 2026 increased by 9.9% compared to the same period in 2025—to 307.915 billion UAH, according to the State Statistics Service.
The agency specifies that 39.5% of the total value of capital investments made (or 121.5 billion UAH) was accounted for by industry, while 11.4% (35 billion UAH) went to agriculture, forestry, and fisheries.
The vast majority of investments were concentrated in tangible assets—94.5% of the total volume. In particular, the largest amounts were invested in machinery, equipment, and inventory (36.1%), engineering structures (22.4%), non-residential buildings (11.4%), and vehicles (10.7%).
According to the State Statistics Service, the main source of funding for capital investments in January–June of this year remains the own funds of enterprises and organizations—75.4% (232.114 billion UAH).
As previously reported, capital investments in Ukraine in 2025 increased by 20.3% compared to 2024, reaching 893.6 billion UAH.
agricultural sector, INDUSTRY, INVESTMENT, State Statistics Service, UKRAINE
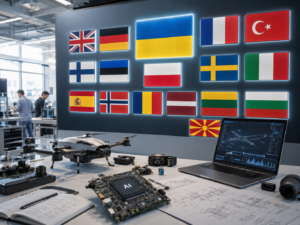
Ukraine has joined the group of Europe’s most dynamic defense-tech markets and ranked third among the European countries reviewed in terms of foreign direct investment attracted to the Space & Defence sector between January 2021 and November 2025, reports the Experts Club information and analytical center.
The findings are based on Colliers’ study Defence Deployment: How Europe’s military build-up and transformation reshapes property demand. Colliers divided Europe’s leading defense-tech markets into three groups. The United Kingdom, Germany, France and Turkey form the first tier; Sweden, Italy, Spain, Norway and Poland are included in the second; while Ukraine, Finland and Estonia are classified as fast-growing technology disruptors in the third tier.
Colliers does not assign individual rankings to countries within each tier. Ukraine is nevertheless singled out as one of Europe’s leading markets for technologies developing directly from battlefield experience, particularly drones, artificial intelligence, electronic warfare and autonomous systems.
Ukraine’s position is even stronger in foreign direct investment. According to fDi Markets data used by Colliers, Ukraine ranks third for Space & Defence FDI behind only the United Kingdom and Romania, while ahead of France, Latvia, Germany, Lithuania, North Macedonia, Poland and Bulgaria.
Colliers also identified 38 major geographical defense-tech clusters across Europe. Among the most significant are London and southeast England, the Paris region, Munich and Bavaria, Madrid, Rome, Milan, Stockholm, Oslo, Warsaw, Rzeszów, Upper Silesia, Helsinki-Espoo, Tampere, Oulu, Tallinn, Tartu, Ankara and Istanbul. No separate Ukrainian geographical cluster is marked on the Colliers map, although Ukraine is classified among the fastest-growing defense-tech markets.
The expansion of Ukraine’s ecosystem is also reflected in Brave1 data. By July 2026, the cluster had awarded developers almost 1,000 grants worth more than UAH 5.8 billion in total. At the European level, further growth is expected to be supported by ReArm Europe / Readiness 2030, whose potential mobilized defense spending Colliers estimates at up to EUR800 billion.
According to Experts.news, residential real estate and institutional leasing became one of the fastest-growing segments of the Central and Eastern European investment market in the first half of 2026.
The residential/living segment accounted for 19% of investments in commercial real estate in the CEE-6, compared to just 7% a year earlier, according to Colliers data.
Thus, its share nearly tripled in less than a year and approached the levels of the traditionally largest real estate classes—offices and retail properties.
One of the most telling examples was Poland, where the largest transaction in the history of the local PRS (institutional rental housing) market took place in the first half of the year.
Vantage Development acquired 18 completed Resi4Rent projects for 575 million euros. The portfolio includes 5,322 apartments in Warsaw, Kraków, Wrocław, Gdańsk, Łódź, and Poznań.
This transaction reflects growing interest among large investors in residential properties intended not for the resale of individual apartments, but for long-term professional leasing of entire portfolios.
This model is widespread in Western Europe, but in Central and Eastern Europe, the institutional rental market is much younger and has more room for growth.
Interest in the segment is driven by urbanization, high housing purchase costs, labor mobility, and growing demand for professionally managed rental housing in the region’s largest cities.
According to Colliers, with total investment in the CEE-6 region amounting to 5.8 billion euros, the market is gradually becoming more diversified, and residential/living has already become one of the top four investment sectors.
The Romanian commercial real estate market attracted approximately 300 million euros in investment in the first half of 2026, compared to about 400 million euros during the same period last year, according to the Colliers CEE Investment Scene H1 2026 report.
Romania accounted for 5.4% of total CEE-6 investment volume, despite the fact that the country accounts for about 18% of the aggregate GDP of the six economies under review. According to Colliers, this indicates significant potential for further growth in the Romanian investment market.
Offices accounted for about 60% of Romania’s investment volume in the first half of the year, marking the highest share for this segment since 2022.
However, the market structure may shift in the second half of the year due to large transactions in retail and other real estate sectors.
Romania continues to offer higher yields than many more mature markets in Central Europe. In Bucharest, the prime yield stands at about 7.5% for offices, 7.75% for industrial and logistics properties, and 7.25% for shopping centers.
By comparison, yields on high-quality properties in Warsaw, Prague, and other more liquid capitals in the region are at lower levels.
Colliers notes that the decline in transaction volume in the first half of the year does not necessarily indicate a deterioration in the market’s fundamentals. A number of large transactions were in the final stages of completion after the end of June.
In particular, the sale of the MAS retail real estate portfolio to AFI Europe was completed in the third quarter. If the deals currently in progress are finalized, Romania’s total investment volume for 2026 could approach 1 billion euros.
This would be only the second year since 2007 that the Romanian market has reached this level, notes Robert Miklo, Head of Capital Markets at Colliers Romania.
Colliers operates in more than 70 countries, employs approximately 28,000 professionals, and has roughly $110 billion in assets under management.
Office real estate regained the top spot among commercial real estate investment sectors in Central and Eastern Europe in the first half of 2026, according to data from Colliers.
Offices accounted for 29% of total investment in the CEE-6, up from 23% a year earlier. With a total market volume of EUR 5.8 billion, this corresponds to approximately EUR 1.7 billion in investments.
Retail real estate became the second-largest segment, with a 27% share, up from 21% in the first half of 2025.
Investor interest in residential and “living” properties grew even faster. Their combined share rose from 7% to 19%.
At the same time, industrial and logistics real estate—which was the largest market segment just a year ago—saw its share decline from 31% to 17%. This was due not only to changes in activity within the warehouse market itself but also to the rapid growth of transactions in other real estate classes.
Colliers notes that in the office segment, investors are primarily seeking modern buildings in prime locations with high energy efficiency and a stable stream of rental income.
The situation is becoming more challenging for outdated office buildings. They must either undergo modernization or be considered for repurposing.
Thus, the structure of the CEE market is gradually changing: after several years of logistics dominance, capital is once again flowing more actively into traditional offices and retail real estate, while institutional housing is emerging as a major investment segment in its own right.



