
The Inzhur Investment Group, which includes an asset management company with three investment funds, an investment firm, a securities broker, and a securities custodian, plans to increase its assets under management from the current 9.36 million UAH to 100 billion UAH over the next five years, said the group’s founder and head, Andriy Zhurzhii.
“100 billion is our dream and our plan. That’s for the next five years. In other words, we’ll end this year with more than 10 billion—10 to 11 billion in assets under management. And over the next five years, we’ll reach 100 billion based on today’s figures. In other words, if there are any devaluation processes, then, of course, we’ll get there faster,” he said during the “Forbes Business Breakfast with Fedorin” on Wednesday, adding that there was a day when the group managed to attract 500 million UAH at once.
According to him, the group has attracted 131,560 investors to its funds, with a minimum investment of 11 UAH.
“We’ve set ourselves the goal of reaching 1 million investors in ‘Inzhur’ by the end of 2028. We plan to end this year with 150,000–200,000 investors: we’re already on track for 170,000, and we’ll have to work hard to reach 200,000, but the team is doing its best,” noted Zhurzhii.
In his view, to increase the number of investors to 2–3 million, it is necessary to invest more in the community and in its education and experience; therefore, the group launched an educational program with Prometheus, which attracted 14,000 registrants in just one week.
The head of “Injur” also expressed the opinion that the Ukrainian market is not yet ready for stocks.
“We will still grow through some form of debt instruments—bonds or quasi-debt instruments, when we’re talking about funds. Stocks will be the next stage,” Zhurzhii believes.
asset, FUND, Injur, INVESTMENT, INVESTOR
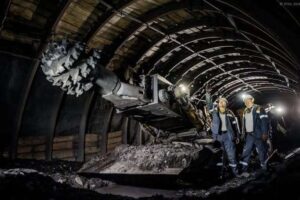
According to Interfax-Ukraine, the Ministry of Energy is working to prepare state-owned coal mining enterprises for transfer to the State Property Fund (SPF) and subsequent privatization, Deputy Minister of Energy Valentina Moskalenko said.
“The Ministry of Energy has indeed prepared our proposals for the government’s action plan, and we are indeed working to prepare all (coal) enterprises for transfer to the State Property Fund, with a view to their subsequent privatization and the search for an effective private investor for them,” Moskalenko said during an online meeting of the Verkhovna Rada’s Energy Committee on Monday.
She also added that the Ministry of Energy, together with the Ministry of Finance, has resolved the issue of compensation for wage arrears, unused vacation time, and all other payments required by law to employees of the two mines being liquidated: “Mine No. 9” (Volyn Oblast) and the “Nadiya” mine (Lviv Oblast).
“The draft plans for the liquidation of the mines are ready, funds are available to carry out the liquidation work, and everyone who wished to transfer to other enterprises has done so,” noted the deputy head of the Ministry of Energy.
At the same time, Moskalenko emphasized that the operations of the state-owned enterprise “Lvivvuhillia” have always been accompanied by debts, and this issue must be resolved.
“Lvivvuhillya has always had debts, with varying trends, and they have never gone away; now all the debts remain with the state-owned mines. We must do everything possible to restore the health of the state-owned coal mining sector,” Moskalenko emphasized.
COAL, INVESTOR, Mine, MINISTRY OF ENERGY, State Property Fund of Ukraine
Turkish authorities have begun the process of revoking the citizenship of 687 foreigners who, according to investigators, obtained Turkish passports through fictitious real estate transactions and forged property appraisal reports. The original source of this information was a statement by Turkish Justice Minister Akin Gürlek, published on August 4, 2026. The operation was coordinated by the Organized Crime Investigation Bureau of the Istanbul Chief Prosecutor’s Office. Investigative actions took place simultaneously in 16 provinces across the country.
According to the investigation, participants in the scheme purchased relatively inexpensive real estate and then, using forged expert reports, artificially inflated its value to the minimum threshold required to obtain Turkish citizenship. The transactions were accompanied by fictitious bank transfers designed to create the appearance of investment inflows.
As a result, Turkish authorities estimate that the country was deprived of approximately 2.5 billion Turkish lira—or roughly $52 million—that was supposed to have been invested by foreign applicants.
As part of the investigation, arrest warrants were issued for 90 people, and 72 suspects have already been detained. The government has placed seven companies that may have been linked to the scheme under its control. Additionally, 1,045 properties, a hotel in Bodrum, 15 vehicles, a yacht, and funds in ten bank accounts have been seized.
It is important to note that this does not yet involve the automatic and immediate revocation of passports, but rather the initiation of legal proceedings. Citizenship will be revoked once it is confirmed that a specific applicant obtained it based on fraudulent documents or a transaction that did not meet legal requirements.
Turkey’s investment citizenship program has been in effect since 2017. Currently, a foreigner can apply for a Turkish passport by purchasing real estate worth at least $400,000. The property cannot be sold for three years, its value must be verified by an authorized appraisal company, and payment must be made through the banking system. Alternative options include an investment or a bank deposit of at least $500,000.
The Ministry of Justice, the Istanbul Prosecutor’s Office, and the Turkish media have not yet disclosed the nationalities of the 687 individuals initially implicated. However, data on previous participants in the investment program and foreign buyers of Turkish real estate allow us to identify groups that potentially used such services more frequently.
Between 2018 and 2021, approximately 19,600 foreigners obtained Turkish citizenship through the investment program. Iran, Iraq, Afghanistan, and Russia were cited as the main countries of origin for applicants, and since 2022, Ukrainian and Russian citizens have significantly increased their purchases of Turkish real estate and have become the most prominent groups of applicants for investment-based citizenship.
According to official statistics from the Turkish Statistical Institute (TÜİK), in 2025, Russians purchased 3,649 residential properties in Turkey, Iranian citizens purchased 1,878, and Ukrainian citizens purchased 1,541. These three countries ranked first among foreign buyers of Turkish housing. This trend continued in 2026. In June, Russian citizens purchased 381 residential properties, while Ukrainians and Iranians each purchased 170 properties.
Based on this data, it is most likely that among the 687 investors under investigation are citizens of Russia, Iran, and Ukraine, who are simultaneously among the largest real estate buyers and the most active participants in the investment citizenship program. The list of those under investigation may also include individuals from Iraq and Afghanistan who participated in the program in previous years.
Additional risks may arise for the spouses and children of investors if they obtained citizenship as family members of the primary applicant. Turkish authorities have not yet clarified whether such relatives are included in the announced total of 687 people or whether their status will be reviewed automatically or through separate procedures. The investigation will likely lead to stricter scrutiny of appraisal companies, bank transfers, intermediaries, and the sources of funds. For new applicants, this may mean longer processing times and additional requirements, but it does not indicate that the investment citizenship program itself is being shut down.
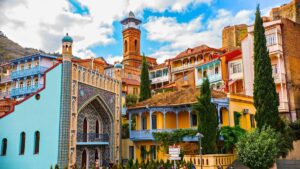
Following a sharp rise in prices caused by the influx of migrants in 2022–2023, Georgia’s residential real estate market is shifting toward more moderate growth, supported by domestic demand, urbanization, rising incomes, and investment in rental housing. In the second quarter of 2026, the price index for new residential real estate in Tbilisi rose by 4.9% compared to the same period last year and by 0.9% compared to the previous quarter. Compared to the 2020 average, housing prices have risen by 63.8%, the Georgian National Statistics Office reported on July 23.
Apartments in new buildings in Tbilisi have risen in price by 4.8% over the past year, while single-family homes have risen by 5.5%. The highest asking prices remain in the Mtatsminda district, where the median price of new apartments reached 6,730 lari per square meter. This is followed by Vake at 5,914 lari and Krtsanisi at 4,630 lari per square meter.
According to estimates by the investment banking firm Galt & Taggart, the period of 20–40% annual price increases for new construction has come to an end. In the coming years, prices in the primary market may grow by an average of 5–7% annually, reflecting a transition from migration-driven frenzy to more sustainable market development.
In the first quarter of 2026, 10,907 thousand apartment transactions were registered in Tbilisi—16% more than a year earlier. The total value of housing sold increased by 23.1% to $958 million.
Georgian citizens remain the primary buyers of housing in the Georgian capital. According to a Galt & Taggart study for the first quarter of 2026, they accounted for about 70% of sales in developers’ projects.
Among foreign buyers, Israeli citizens were the most active, accounting for 12% of all sales. Russian citizens accounted for about 3%, while buyers from other countries accounted for a combined 14%. The statistics for Tbilisi do not provide a separate figure for Ukrainian citizens.
The Batumi market remains significantly more dependent on foreign investors. In the first quarter of 2026, 4,049 thousand apartments were sold in the city—15.8% more than during the same period last year. The Galt & Taggart study covered more than 30 projects by major developers, accounting for about 40% of Batumi’s primary market. According to the results, Georgian citizens accounted for 37% of sales, while foreigners accounted for about 63%.
The largest foreign group consisted of buyers from European countries, who accounted for about 18% of transactions. Israeli citizens accounted for 16% of sales, while the combined share of buyers from Ukraine, Russia, and Belarus totaled 13%.
Turkish citizens purchased another 10% of the apartments, buyers from Arab countries accounted for 3%, and buyers from other countries accounted for about 4%. The data published by the Georgian authorities does not break down the shares of Ukraine, Russia, and Belarus, so it is impossible to determine which of these three countries’ citizens were the most active buyers.
The demand structure reveals a significant difference between the country’s two largest markets. In Tbilisi, sales are driven primarily by Georgian buyers purchasing homes for residential use or long-term rental. In Batumi, foreign investors play the leading role, focusing on resort real estate and renting apartments to tourists.
However, official Geostat statistics cover only prices for new housing in Tbilisi and do not provide a complete breakdown of buyers’ nationalities across Georgia. Data on citizenship is based on surveys of major developers such as Galt & Taggart; therefore, it primarily reflects the organized primary market rather than all real estate transactions in the country.
Kyivstar Group Ltd. (Nasdaq: KYIV), the parent company of Ukraine’s largest telecommunications operator Kyivstar, has announced the opening of its own office at Rockefeller Center in New York, marking an important stage in the company’s international development following its historic Nasdaq listing in August 2025.
“The opening of our New York office is an important milestone in the international development of Kyivstar Group Ltd.,” Kyivstar President and CEO Oleksandr Komarov was quoted as saying in the release.
According to him, a presence in one of the world’s key financial centers will help strengthen relations with investors and international partners, as well as expand cooperation.
The Kyivstar office is located at 1270 Avenue of the Americas. It is expected to support the company’s investor relations and corporate communications activities, as well as strengthen its presence in the United States.
“The opening of the office also creates additional opportunities to present Ukrainian business and its investment potential to the international community,” Kyivstar emphasized.
At the same time, the office will not perform commercial, contractual or operational functions on behalf of the Group, the press release said.
The company recalled that Kyivstar is celebrating the first anniversary of its Nasdaq listing this summer. During this period, the company continued to develop its portfolio of digital products and implement strategic initiatives, including the expansion of digital healthcare services, the development of the Uklon platform and the introduction of new telecommunications solutions, including Starlink Direct to Cell.
“In addition, the new office will become the New York base for the Invest In Ukraine NOW! initiative launched by VEON and Kyivstar in August 2025,” the company said.
As reported, Kyivstar increased EBITDA in the second quarter of 2026 by 21.1% to UAH 8.3 billion, while revenue rose by 27% to UAH 14.9 billion.
In 2025, the Group increased EBITDA by 30% to UAH 27 billion, while revenue grew by 30.3% to UAH 48.2 billion.
The number of inquiries from foreign clients regarding the purchase of luxury real estate in the U.S. during the first five months of 2026 doubled compared to the same period last year, according to an interim report by Coldwell Banker Global Luxury published on July 14.
The calculation is based on data from the international platform JamesEdition and reflects trends in buyer inquiries from January 1 through May 10, 2026, compared to the same period in 2025. Thus, this reflects a rise in interest among potential clients, rather than a doubling in the number of closed deals.
California accounted for the largest share of inquiries from foreign buyers. New York and Florida followed, with New York in particular showing the highest growth rate in interest from abroad. Foreign investors view American premium-class properties as a way to geographically diversify their assets and preserve capital over the long term.
Another trend has been the rise of so-called “landmaxxing”—the acquisition of neighboring homes and land parcels to expand one’s estate, enhance privacy, preserve the view from windows, or create multi-generational family estates. Demand for unique properties—including estates, historic buildings, branded residences, and private islands—has risen by 146%, while interest in land parcels has increased by 97%.
Nearly 40% of luxury real estate professionals surveyed reported that affluent buyers are willing to purchase homes in need of renovation if they are located in a prestigious neighborhood. At the same time, 63% of real estate agents noted an increase in the share of cash transactions among clients in the premium segment, compared to 51% a year earlier.
According to the latest study published by the National Association of Realtors, covering transactions from April 2024 through March 2025, foreigners purchased 78,100 U.S. residential properties with a total value of $56 billion. The number of purchases rose by 44%, and their total value increased by 33.2%. The median price of residential properties purchased by foreign buyers reached a record $494,400, with 47% of transactions paid for entirely in cash.
The top 10 countries of origin for foreign buyers included China with a 15% share, Canada with 14%, Mexico with 8%, India with 6%, the United Kingdom with 4%, as well as Brazil, Colombia, Nigeria, and the UAE, each with 3%. Israel ranked tenth with a 2% share. These figures apply to the entire U.S. residential real estate market, not just the luxury segment.
Among U.S. states, the top destinations for foreign buyers remained Florida, which accounted for 21% of transactions, California—15%, Texas—10%, New York—7%, and Arizona—5%.



