
In August 2026, central banks around the world increased their official gold reserves by a total of 39 metric tons in net terms, with the People’s Bank of China emerging as the largest buyer, according to an analysis by Experts Club based on data from the World Gold Council (WGC) published on October 6.
According to the WGC, the main buyers of gold in August were:
China — 20.2 metric tons
Poland — 7.8 metric tons
Uzbekistan — 7.8 metric tons
Kazakhstan — 7.4 metric tons
Turkey — 2.9 metric tons
Czech Republic — 1.7 metric tons
Bolivia—about 1 metric ton
Ghana—about 1 metric ton
China continued to purchase gold for the 22nd consecutive month. In August, the People’s Bank of China increased its gold reserves by approximately 20.2 metric tons—the largest monthly increase since October 2023.
From January through August, China purchased about 80 metric tons of gold. The country’s official gold reserves reached approximately 2,387 metric tons, accounting for about 9% of China’s total international reserves.
Despite China’s lead in August alone, Poland remains the largest buyer of gold since the beginning of 2026. The National Bank of Poland purchased about 7.8 metric tons in August and 98 metric tons since the start of the year. Poland’s gold reserves have grown to approximately 648 metric tons, approaching its stated target of 700 metric tons.
Uzbekistan increased its reserves by approximately 7.8 metric tons. Since the beginning of the year, the country has purchased about 50 metric tons of gold, bringing its total gold reserves to approximately 439 metric tons. Gold accounts for about 90% of Uzbekistan’s reserves.
Kazakhstan purchased about 7.4 metric tons of gold in August, bringing its total purchases since the beginning of the year to approximately 36 metric tons. The country’s gold reserves reached about 377 metric tons, or 79% of its international reserves.
Turkey returned to net purchases after three months of sales, acquiring about 2.9 metric tons. However, since the beginning of 2026, the country has remained a major net seller—the total reduction in reserves amounts to about 82 metric tons, with the bulk of sales occurring in the first quarter.
The Czech National Bank purchased about 1.7 metric tons, thereby extending its streak of net gold purchases to 42 consecutive months. Since the start of the year, the Czech Republic has added about 14 metric tons, increasing its reserves to 86 metric tons.
Overall, from January through August 2026, central banks worldwide reported net purchases of approximately 170 metric tons of gold.
The World Gold Council notes that the composition of the largest buyers remains relatively stable. This indicates that central banks are purchasing gold primarily as part of their long-term reserve management policies, while monthly fluctuations are linked to the timing of program implementation, market conditions, and individual countries’ liquidity needs.
For comparison: in July, central banks worldwide purchased 23 metric tons of gold on a net basis. Thus, in August, the volume of net purchases increased by approximately 70% month-over-month.
Official source: World Gold Council, Central Bank Gold Statistics, published on October 6, 2026.
On September 24, the U.S. Federal Reserve (Fed) unveiled two draft rules for issuers of payment stablecoins as part of the implementation of the previously enacted GENIUS Act.
Under the regulator’s proposal, issuers supervised by the Fed would be required to fully back issued stablecoins with eligible reserve assets. These include, in particular, short-term U.S. Treasury bonds and other high-quality, highly liquid assets.
At the same time, the proposal calls for establishing standardized capital requirements for issuers to cover credit and operational risks, risk management requirements, as well as specific rules for companies responsible for safeguarding stablecoin reserve assets.
The second document establishes a special procedure for banks under the Fed’s supervision that wish to issue their own payment stablecoins. Banks will be required to submit a business plan, financial information, and other documents.
Thus, following the legislative framework for the stablecoin market, U.S. regulators are moving toward creating a practical system for supervising issuers.
Federal Reserve Board Member Michael Barr separately emphasized the need to ensure that stablecoins can be reliably redeemed at par value even under conditions of market stress.
The public comment period for the proposals will last 60 days following their publication in the Federal Register.
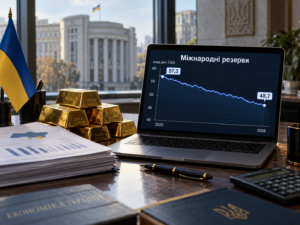
Ukraine’s international reserves amounted to $48.7 billion at the end of August 2026, which is approximately $8.6 billion, or 15%, less than at the beginning of the year, according to an analysis by the Experts Club information and analytical center.
As of January 1, reserves stood at a record level of $57.3 billion, and by the beginning of February they had risen to $57.7 billion. After that, they declined for four consecutive months: to $54.8 billion as of March 1, $52 billion as of April 1, $48.2 billion as of May 1, and $45.7 billion as of June 1.
The main factors behind the decline were significant foreign exchange interventions by the National Bank, government debt payments, and uneven inflows of international financial assistance.
The situation changed sharply in June, when Ukraine received large tranches of external financing. Reserves increased by 12.1% over the month — to $51.27 billion. About $11.3 billion was credited to the government’s foreign currency accounts, including $6.82 billion from the EU and almost $4.5 billion through the World Bank.
In July, reserves remained almost unchanged, but in August they again decreased by approximately $2.5 billion, or 5%, to $48.7 billion.
In August, the NBU sold about $4.82 billion on the foreign exchange market, while $927.3 million was credited to the government’s foreign currency accounts. Ukraine also directed $721.8 million toward servicing and repaying government debt in foreign currency and paid $258.2 million to the IMF.
Net international reserves declined even more sharply over the month — by 6.9%, to $33.8 billion.
At the same time, the current level of reserves remains approximately 5.8% higher than a year ago, when they stood at about $46 billion as of September 1, 2025.
Experts Club founder and economist Maksym Urakin previously emphasized that the absolute size of reserves should not be regarded as a guarantee of currency security.
“Reserves at the level of $51.2 billion remain a significant foreign exchange buffer, but the absolute figure itself should not create an impression of complete protection. The sustainability of reserves depends on the regularity of international financing, the volume of NBU interventions, debt payments, and the economy’s ability to increase export revenues,” Urakin noted.
According to the NBU, the current level of reserves remains sufficient and provides financing for approximately four months of future imports.
According to preliminary data, Ukraine’s international reserves decreased by $70.4 million, or 0.1%, to $51.2 billion in July, the National Bank of Ukraine (NBU) reported on Friday.
“This trend was driven by the National Bank’s foreign exchange interventions and the country’s debt payments in foreign currency,” the regulator noted on its website.
According to the published data, net international reserves in July decreased by $668.9 million, or 1.8%, compared to June, to $36.3 billion.
The share of dollar-denominated assets in international reserves as of August 1, 2026, decreased to 64.7% from 66.5% a month earlier, while the share of euro-denominated assets rose to 27.0% from 25.6%. A year ago, these figures stood at 73.5% and 17.5%, respectively.
The share of gold in international reserves as of early August stood at 7.0%, compared with 6.9% a month earlier and 6.8% a year earlier.
It is noted that $1.6 billion was credited to the government’s foreign currency accounts at the National Bank in July, including $683.3 million from the International Monetary Fund (IMF), $498.7 million through World Bank accounts, and $458.6 million from the placement of foreign currency government bonds.
In addition, Ukraine received $5.1 billion from the European Union (EU) as part of a defense tranche under the Ukraine Support Loan program; however, due to the earmarked nature of this funding, these funds do not directly enter the international reserves. In July, the government converted $3.4 billion of these funds into hryvnia, which correspondingly contributed to an increase in international reserves.
At the same time, the Ukrainian government paid $515.4 million for servicing and repaying public debt denominated in foreign currency, including $433.3 million for servicing and repaying foreign-currency government bonds, $58.7 million for servicing and repaying debt to the World Bank, $6.9 million for servicing debt to the EU, and $16.5 million for debt to other creditors.
In addition, Ukraine paid $174.2 million to the IMF.
The revaluation of financial instruments in July increased the value of reserves by $300.6 million.
The National Bank’s foreign exchange interventions totaled nearly $4.79 billion, which is $296.0 million less than in June.
“The current level of international reserves is sufficient to finance 4.2 months of future imports,” the National Bank added.
As previously reported, in its July macroeconomic forecast, the regulator raised its estimate of international reserves for the end of 2026 to $69.7 billion from $64.8 billion, for 2027 to $73.7 billion from $66.5 billion, and for 2028 to $70.0 billion from $61.1 billion.
According to Interfax-Ukraine, this article presents key macroeconomic indicators for Ukraine and the global economy as of the end of April 2026. The analysis is based on data from the State Statistics Service of Ukraine, the National Bank of Ukraine, the Ministry of Finance, the State Customs Service, the International Monetary Fund, Eurostat, BEA, BLS, NBS, ONS, TurkStat, IBGE, and other official institutions. Monthly and quarterly statistical data published after the end of the reporting period were used for April indicators.
Maksim Urakin, Ph.D. in Economics and founder of the information and analytical center Experts Club, presented an overview of the key trends that shaped the state of the Ukrainian and global economies in April and early May 2026.
Ukraine’s Macroeconomic Indicators
As of the end of April, the Ukrainian economy remained macro-financially stable, although inflationary, currency, and foreign trade risks had intensified. Compared to March, consumer inflation accelerated, international reserves declined for the third consecutive month, and the trade deficit continued to widen. At the same time, the government ensured funding for defense, social benefits, and critical budgetary needs, while the National Bank of Ukraine (NBU) maintained control over the foreign exchange market.
According to a preliminary estimate by the State Statistics Service, Ukraine’s real GDP in the first quarter of 2026 decreased by 0.6% compared to the first quarter of 2025. On a seasonally adjusted basis, the decline was 0.7% compared to the previous quarter.
Nominal GDP amounted to 2,047.2 billion UAH. This negative trend was attributed to electricity shortages, infrastructure damage, delays in external financing, weak investment activity, and adverse weather conditions at the beginning of the year. At the same time, private consumption remained relatively stable, while the manufacturing sector, trade, and certain service sectors showed growth.
In its April forecast, the National Bank revised downward its estimate for Ukraine’s real GDP growth in 2026 to 1.3%. The main reasons were further damage to energy and logistics infrastructure, a larger electricity shortage, high energy prices, and weaker first-quarter results. The NBU expected economic growth to be supported by consumer demand and investments in reconstruction and the defense-industrial complex, but did not forecast a rapid transition to a sustainable recovery.
“The first-quarter results confirmed that the Ukrainian economy remains extremely sensitive to energy, military, and fiscal shocks. Positive domestic demand and business resilience can no longer fully offset the losses from infrastructure destruction, electricity shortages, and weak exports. The 1.3% growth forecast implies actual stagnation on a per-capita basis. “Therefore, the main priority should be not only to maintain financial stability but also to restore production capacity,” Urakin noted.
The inflation situation worsened in April. Consumer inflation accelerated to 8.6% year-over-year, up from 7.9% in March. Prices rose by 1.4% over the month and by 4.9% since the beginning of the year. Core inflation rose to 7.6% year-over-year, inflation for services reached 13.3%, and the increase in fuel prices hit 36.1% year-over-year.
The main source of inflationary pressure was the rise in energy and fuel prices, which increased business costs for logistics, electricity, and production. Additional factors included wage increases, the pass-through of the hryvnia’s earlier depreciation to consumer prices, and rising costs of certain food products and transportation services. Bread, grains, sunflower oil, fish, restaurant services, and household services saw the fastest price increases.
The NBU’s April forecast projected that inflation would accelerate to 9.4% by the end of 2026. A return to a steady decline was expected in 2027, when inflation was projected to slow to 6.5%, and to reach the 5% target in 2028.
On April 30, the National Bank’s Board kept the policy rate at 15% per annum. The regulator explained the decision by the need to maintain the attractiveness of hryvnia-denominated assets, keep inflation expectations under control, and ensure the stability of the foreign exchange market. The NBU’s forecast called for keeping the rate at 15% at least until the second quarter of 2027. In the event of further intensification of price pressures, the regulator did not rule out the use of additional measures, including a rate hike.
“The acceleration of inflation to 8.6% and the sharp rise in fuel prices left the National Bank no room to continue its policy easing cycle. Under current conditions, the 15% rate is not so much a tool for curbing lending as it is a mechanism for safeguarding confidence in the hryvnia. The risk of a premature rate cut now significantly outweighs the potential short-term effect on economic activity,” Urakin emphasized.
The foreign exchange sector remained under control but required significant support from the regulator. As of May 1, 2026, Ukraine’s international reserves stood at $48.215 billion, having declined by 7.3% in April. This marked the third consecutive monthly decline in reserves.
In April, the NBU sold $3.577 billion on the foreign exchange market, while inflows into the government’s foreign currency accounts totaled only $377.9 million. $716.6 million was allocated to service and repay foreign-currency government debt, and Ukraine paid another $255.3 million to the IMF. The losses were partially offset by a positive revaluation of financial instruments amounting to $378 million. Despite the decline, the reserves were sufficient to finance 4.9 months of future imports.
“The decline in reserves from nearly $52 billion to $48.2 billion in a single month is significant, but not yet critical. Far more important is the underlying cause: the private foreign exchange market remains structurally in deficit, and international inflows do not always coincide with the timing of intervention needs and debt payments. Therefore, the stability of the hryvnia will continue to depend on the regularity of external financing and Ukraine’s ability to narrow the trade gap,” Urakin believes.
According to the State Customs Service, Ukraine’s trade turnover in January–April 2026 amounted to $46.1 billion. Imports reached $32.2 billion, while exports totaled $13.9 billion. Thus, the trade deficit for the four-month period was approximately $18.3 billion, with imports exceeding exports by a factor of 2.3.
Ukraine imported the most goods from China—$8.7 billion—followed by Poland—$3.1 billion—and Turkey—$2.2 billion. The main destinations for Ukrainian exports were Poland—$1.5 billion—Turkey—$1.2 billion—and Italy—$857 million.
In the import structure, machinery, equipment, and transportation accounted for $13.3 billion; fuel and energy products—$5.3 billion; and chemical industry products—$4.6 billion. Exports were primarily driven by food products at $8.5 billion, metals and metal products at $1.3 billion, and machinery, equipment, and transportation at $1.2 billion.
“The increase in the trade deficit to $18.3 billion in just four months is one of the main macroeconomic challenges. A significant portion of imports is objectively necessary—these include energy resources, equipment, transportation, and defense products. However, the export base remains too narrow and reliant on raw materials. Without the development of processing, machine building, the defense industry, and service exports, Ukraine will continue to offset the trade deficit with international aid and reserves,” Urakin emphasized.
The budgetary situation remained tense but under control. From January through April, the general fund of the state budget received 1.04 trillion UAH. Total cash expenditures from the general fund amounted to 1.35 trillion UAH, which is 13.8% more than during the same period in 2025. In April alone, General Fund revenues totaled 302.6 billion hryvnias, while expenditures amounted to 433.1 billion hryvnias.
Expenditures on security and defense over the four-month period reached 854.1 billion hryvnias, or 63.3% of all General Fund expenditures. In April, 283.1 billion hryvnias were allocated for these purposes. UAH 555.5 billion was spent on public sector wages and related benefits, UAH 235 billion on social security, UAH 205.4 billion on subsidies and transfers to enterprises, UAH 151.4 billion on goods and services, and UAH 103.2 billion on servicing the national debt.
International grants for January–April totaled 228.2 billion hryvnias, with 55.1 billion hryvnias received in April alone. In total, 1.43 trillion hryvnias flowed into the general and special funds of the state budget over the four-month period, while state budget cash expenditures amounted to 1.7 trillion hryvnias.
“The budget remains functional, but its structure is entirely dictated by the war. When nearly two-thirds of the general fund’s expenditures are directed toward defense and security, the capacity to finance long-term development remains limited. Under these conditions, it is particularly important that international aid cover the budget’s civilian needs, while domestic resources are directed as effectively as possible toward defense, energy, and industrial recovery,” Urakin noted.
The Global Economy
As of the end of April 2026, the global economy remained resilient, but the geopolitical and inflationary environment had deteriorated significantly. The war in the Middle East caused energy prices to rise, heightened inflationary expectations, and forced major central banks to postpone further monetary easing.
In its April World Economic Outlook, the International Monetary Fund projected global economic growth of 3.1% in 2026 and 3.2% in 2027, assuming the conflict would be limited in duration and scope. The IMF warned that a longer war, deepening geopolitical fragmentation, new trade disputes, and high public debt could significantly worsen the outlook.
The U.S. economy maintained positive momentum. According to the BEA’s revised estimate, real GDP in the first quarter of 2026 grew by 2.1% on an annualized basis compared with the previous quarter. Growth was driven by investment, exports, and government and consumer spending.
At the same time, inflation in the U.S. continued to accelerate. In April, the CPI rose by 3.8% year-over-year, following a 3.3% increase in March. Core inflation stood at 2.8%, while energy inflation reached 17.9%. In just one month, energy prices rose by 3.8%, and gasoline prices by 5.4%.
On April 29, the Federal Reserve kept the federal funds rate target range at 3.5–3.75%. The Fed cited elevated inflation, rising global energy prices, and high uncertainty surrounding events in the Middle East.
The eurozone showed significantly weaker economic momentum. According to a preliminary Eurostat estimate released on April 30, eurozone GDP in the first quarter grew by only 0.1% compared to the previous quarter and by 0.8% year-over-year. This indicated that the region’s economy was effectively stagnating.
Annual inflation in the eurozone accelerated to 3.0% in April, up from 2.6% in March. In the European Union, it rose to 3.2%. Services, energy, and food made the largest contributions to the rise in prices.
On April 30, the European Central Bank kept its deposit rate at 2.0%, its main refinancing rate at 2.15%, and its marginal lending rate at 2.40%. The ECB emphasized that risks of rising inflation and a slowdown in economic growth had intensified due to the energy shock.
In the United Kingdom, by contrast, inflation slowed to 2.8% year-over-year in April, down from 3.3% in March. Core CPI fell to 2.5%, and services inflation to 3.2%. At the same time, motor fuel prices rose significantly due to the external energy shock.
On April 30, the Bank of England kept its base rate at 3.75%. Eight members of the Monetary Policy Committee supported this decision, while one voted to raise the rate to 4%.
“April showed that the global cycle of rapid interest rate cuts has effectively been put on hold. The U.S. faced accelerating inflation to 3.8%, the eurozone to 3%, and central banks were once again forced to focus on energy risks. For Ukraine, this means more expensive global capital, more challenging conditions for exports, and additional pressure due to fuel prices,” Urakin noted.
China’s economy grew by 5.0% year-over-year in the first quarter of 2026. Nominal GDP reached 33.419 trillion yuan. Industrial production increased by 6.1%, the services sector by 5.2%, and foreign trade in goods by 15%. At the same time, real estate investment fell by 11.2%, indicating that structural problems persist. In April, China’s CPI rose by 1.2% year-over-year and by 0.3% month-over-month. Average inflation for January–April stood at 0.9%. Meanwhile, retail sales in April grew by only 0.2% year-over-year, indicating weakness in domestic consumer demand.
India maintained the highest growth rates among major economies. Following the transition to a new statistical base, the official estimate for real GDP growth in fiscal year 2025/26 was raised to 7.6%, and nominal GDP growth to 8.6%. The main drivers remained the services sector, domestic consumption, construction, and government investment.
Turkey again faced a sharp spike in inflation in April. Consumer prices rose by 4.18% month-over-month and by 32.37% year-over-year. Year-to-date inflation stood at 14.64%. The figure exceeded March’s level of 30.87%, indicating the instability of the disinflation process. At the same time, Turkey’s GDP grew by approximately 3.6% in 2025, confirming the economy’s ability to sustain business activity even amid high price pressures.
Brazil showed more balanced dynamics, although inflation also accelerated. The country’s GDP grew by 2.3% in 2025, reaching 12.7 trillion reais at current prices. In April 2026, the IPCA index rose by 0.67% month-over-month, and annual inflation reached 4.39%, up from 4.14% in March. The largest contributions came from food, medical goods, and services.
“China, India, Turkey, and Brazil demonstrate four distinct development models. China maintains high growth rates thanks to industry and exports, but still faces challenges with domestic demand and real estate. India relies on demographics, services, and investment. Turkey sustains growth at the cost of very high inflation. Brazil is moving more slowly but is trying to strike a balance between economic activity and price stability. “For Ukraine, the main conclusion is that long-term growth is impossible without its own manufacturing, technological, and export base,” Urakin believes.
Conclusions
As of the end of April 2026, Ukraine maintained macrofinancial stability, but key indicators pointed to increasing risks. Real GDP contracted by 0.6% year-over-year in the first quarter; inflation accelerated to 8.6% in April, with core inflation rising to 7.6%, while the policy rate remained at 15%.
International reserves fell to $48.2 billion, a decrease of 7.3% over the month. The trade deficit for January–April reached $18.3 billion. Revenues to the general fund of the state budget totaled 1.04 trillion UAH, while expenditures amounted to 1.35 trillion UAH. UAH 854.1 billion, or 63.3% of all general fund expenditures, was allocated to security and defense.
Positive factors included substantial reserves, a controlled exchange rate policy, international financing, steady consumer demand, business adaptability, and the development of defense production. The main risks were the continuation of the war, the destruction of energy infrastructure, rising fuel prices, labor shortages, weak exports, and the budget’s dependence on foreign aid.
The global economy also entered a more challenging period. The IMF projected global growth of 3.1% in 2026 but warned that downside risks predominated. Inflation in the U.S. accelerated to 3.8%, and in the eurozone to 3.0%, while the central banks of the U.S., the eurozone, and the United Kingdom kept interest rates unchanged. China grew by 5% in the first quarter, India maintained a growth rate of over 7%, while Turkey once again faced inflation exceeding 32%.
“April 2026 showed that Ukraine’s stabilization model remains viable, but its financial buffer is shrinking. The simultaneous acceleration of inflation, depletion of reserves, and widening of the trade deficit signal that external aid cannot be the sole foundation of economic stability. Ukraine needs to transition from financing its immediate survival to creating a new production model. This model should be based on energy self-sufficiency, the defense-industrial complex, agricultural processing, machine building, logistics, digital technologies, and exports of high-value-added products. “Only such a transition can transform macrofinancial stability from a temporary safety net into the foundation for long-term development,” concluded Maksym Urakin.
The average level of reserves in underground storage facilities in Europe fell to 29.99% at the end of the gas day on February 27, according to data from Gas Infrastructure Europe. This is 16 percentage points lower than the average for the last five years.
The fill rate of underground storage facilities in Germany and France, Europe’s leading economies, is significantly lower than the European average — 20.6% and 21.4%, respectively, and 10.7% in the Netherlands.
The spot price of gas with “day ahead” delivery on the benchmark European TTF hub closed at $387 per 1,000 cubic meters on Friday.
Since the beginning of 2025, the transit of Russian gas through Ukraine has ceased. Europe is trying to compensate for the shortage of Gazprom’s pipeline gas supplies by importing liquefied natural gas. At the end of 2025, countries in the region purchased 109 million tons of LNG (142 billion cubic meters after regasification), which is 28% more than in 2024. In February 2026, liquefied gas imports reached 9 million tons, which is 9% higher than a year earlier.
Despite high demand, there remains a large unused capacity reserve—on February 27, terminals were operating at 64% of their throughput capacity.
Europe entered the current heating season with incomplete underground gas storage facilities. The need to replenish the reserves used up during this period will be an additional factor driving demand on the global market throughout the coming year.
Given not only technical but also realistic and economic constraints that will limit the European injection campaign in the summer of 2026, the question of how much Europe will be able to fill its UGS facilities by next winter and how risky the 2026/27 heating season will be will be relevant.



