
Georgia has the highest balance of positive and negative attitudes among Ukrainians among the countries of the Caucasus and Central Asia included in the study—48.5 percentage points. Azerbaijan scored 40.1 percentage points, while Uzbekistan’s score was 11.1 percentage points. These findings come from the third wave of the study “Ukrainians’ Attitudes Toward Countries Around the World,” conducted by Active Group in collaboration with Experts Club, according to the Experts Club Information and Analytical Center.
57.3% of Ukrainians surveyed view Georgia positively, 32.1% neutrally, 8.8% negatively, and another 1.8% were undecided. The balance of positive and negative assessments stands at 48.5 percentage points and has gradually increased over the three waves of the survey: from 45.6 percentage points in August 2025 to 47.5 percentage points in March 2026 and 48.5 percentage points in August of this year. The current figures for positive attitudes and the balance are confirmed by the published survey data.
A positive attitude toward Azerbaijan was expressed by 48.7% of respondents, a neutral one by 39.5%, a negative one by 8.6%, and another 3.1% chose the “difficult to answer” option. The balance stands at 40.1 percentage points. Compared to March 2026, it has risen from 37.8 percentage points, but remains lower than the August 2025 level of 51 percentage points. In terms of the share of positive assessments, Azerbaijan ranks second in this regional group after Georgia.
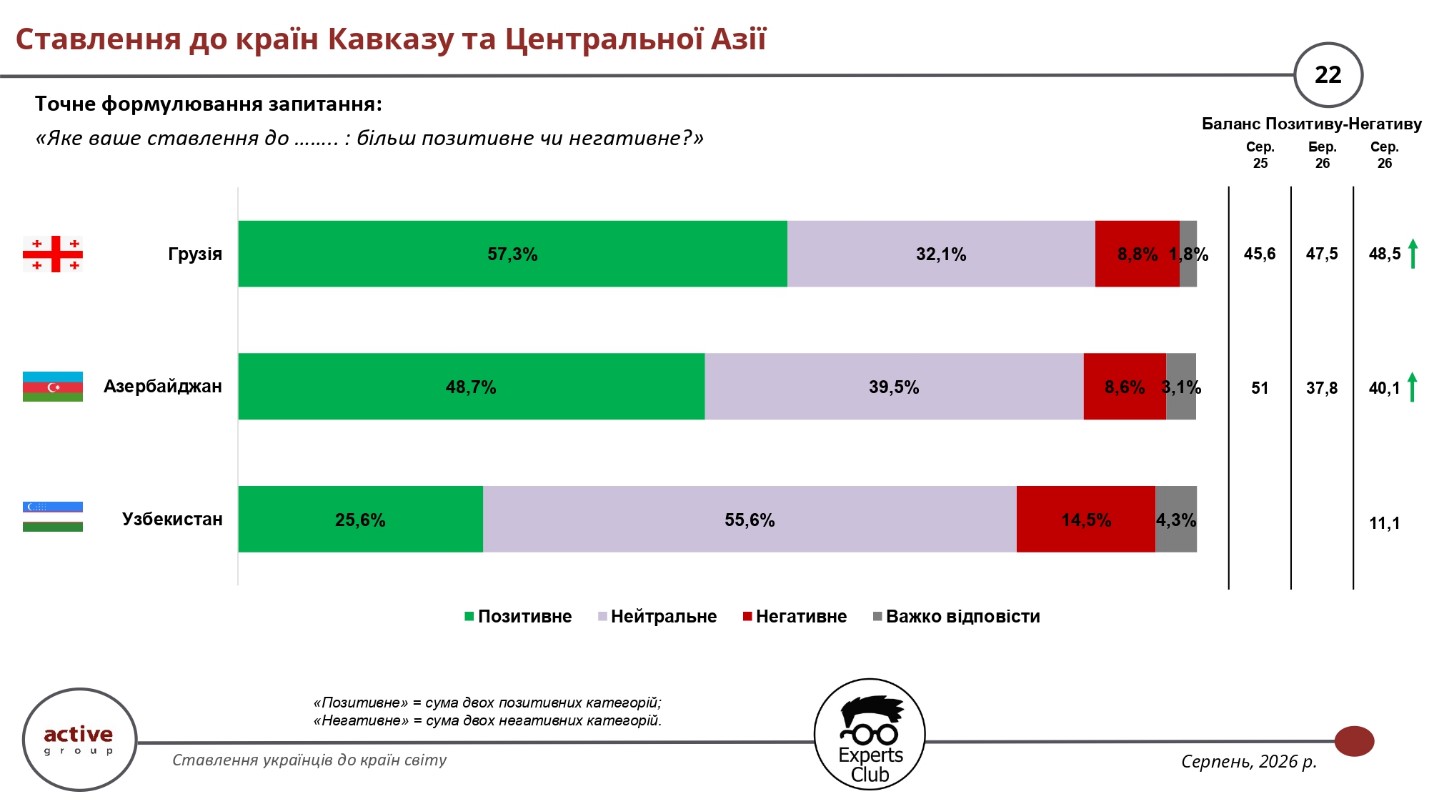
Attitudes toward Uzbekistan are characterized primarily by a high proportion of neutral assessments. 25.6% of respondents view the country positively, 55.6% neutrally, 14.5% negatively, and another 4.3% are undecided. The balance between positive and negative responses is 11.1 percentage points. In the study’s analytical materials, the high proportion of neutral responses is noted as a characteristic feature of perceptions of countries in the region that receive less media attention from the Ukrainian audience.
Thus, the balance remains positive for all three countries surveyed, but the structure of the assessments differs significantly. In the case of Georgia, the overwhelming majority of respondents express a positive attitude; positive assessments also prevail regarding Azerbaijan, while a neutral stance dominates in assessments of Uzbekistan.
Maksym Urakin, founder of the Experts Club Information and Analytical Center, deputy director of the Interfax-Ukraine news agency, and candidate of economic sciences, emphasized the importance of systematic communication between foreign partners and Ukrainian society.
“Second, we must be open to questions and inquiries from the media and the public. We also need to make use of our sociological data,” Urakin noted. According to him, it is important for embassies to regularly inform the Ukrainian audience about specific results of cooperation and to maintain full-fledged communication in the Ukrainian language.
Oleksandr Pozniy, director of the research company Active Group, drew attention to the need to develop the practical component of international economic cooperation.
“We should focus not only on raising general awareness. We need to expand cooperation with countries where we can achieve a positive trade balance,” Pozniy noted. He also highlighted the role of business associations, the Ministry of Economy, and the Ministry of Foreign Affairs in developing bilateral relations.
The survey was conducted in August 2026 using self-administered online questionnaires via the SunFlowerSociology panel. A total of 800 Ukrainian citizens aged 18 and older were surveyed. According to the organizers, the sample is representative in terms of age, gender, and region, and the maximum theoretical margin of error for indicators at the 50% confidence level is ±3.5 percentage points. This is the third wave of the survey, following surveys conducted in August 2025 and March 2026.
ACTIVE GROUP, AZERBAIJAN, Central Asia, EXPERTS CLUB, GEORGIA, international relations, Pozniy, SOCIOLOGY, the Caucasus, UKRAINE, URAKIN, UZBEKISTAN
The Czech Republic and Moldova have the highest net sentiment—the balance of positive and negative attitudes—among Ukrainians among the Central and Eastern European countries included in the study—56.2 and 48.2 percentage points, respectively. At the same time, the balance of attitudes toward Poland turned negative in August 2026, while assessments of Slovakia and Hungary improved significantly compared to previous waves. This is evidenced by the results of the third wave of the study “Ukrainians’ Attitudes Toward Countries Around the World,” conducted by Active Group in collaboration with Experts Club, according to the Experts Club Information and Analytical Center.
The Czech Republic received the highest share of positive assessments in this group—61.3%. 32.1% of respondents have a neutral attitude toward it, 5.1% have a negative attitude, and another 1.6% were undecided. The balance of positive and negative attitudes stands at 56.2 percentage points, compared to 64.4 percentage points in March 2026 and 58.7 percentage points in August 2025.
Regarding Moldova, 55.4% of respondents have a positive attitude, 35.6% are neutral, and 7.2% have a negative attitude. The balance stands at 48.2 percentage points, which is lower than the 54.7 percentage points recorded in March but higher than the 46.6 percentage points recorded in August of last year.
Regarding Romania, 45.2% of respondents expressed a positive attitude, 42.3% were neutral, and 9.8% were negative. The balance fell to 35.4 percentage points from 41.7 percentage points in March. In Bulgaria, positive assessments accounted for 42.7%, neutral ones for 47.6%, and negative ones for 7.4%, with the balance standing at 35.3 percentage points, compared to 51.5 percentage points in March.
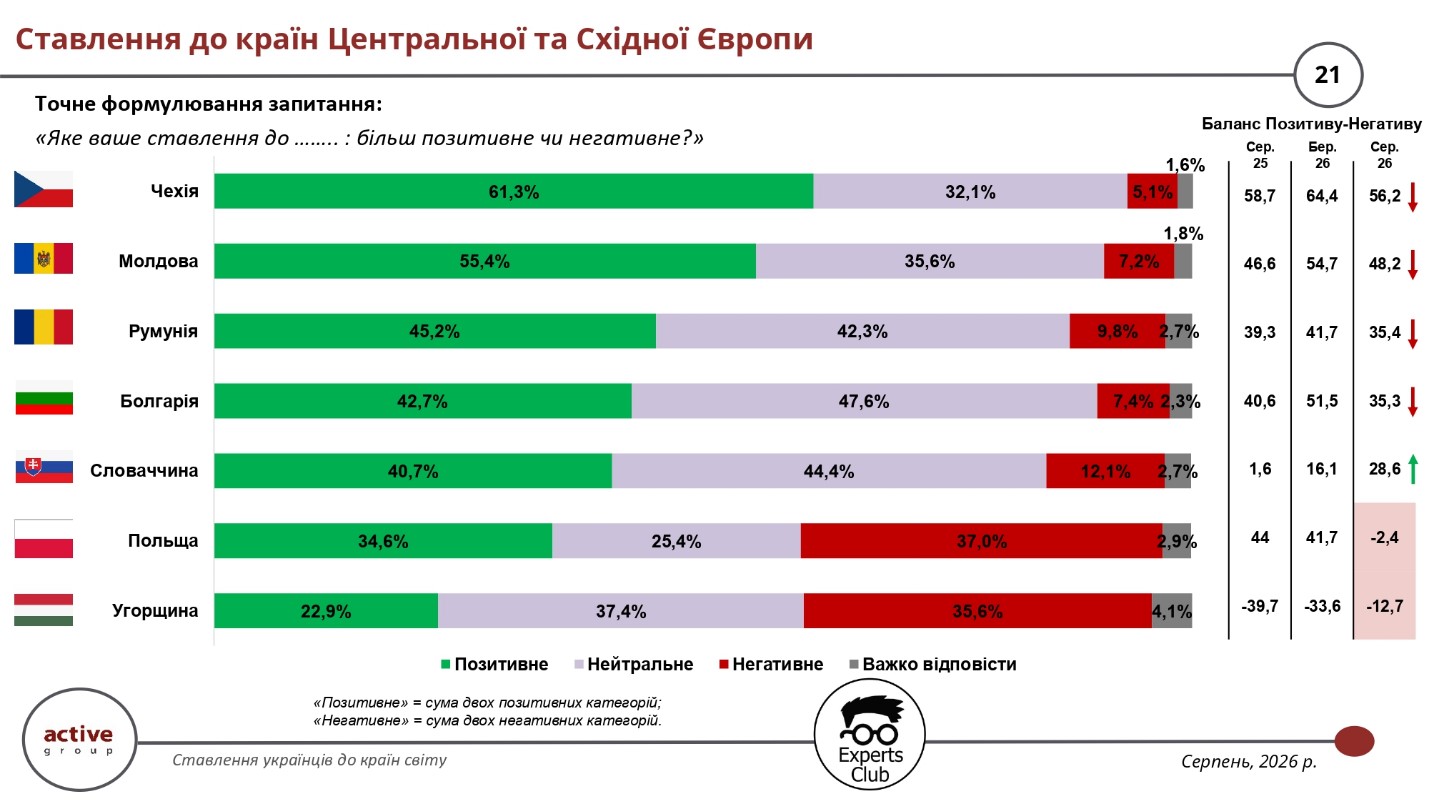
Unlike most countries in the group, attitudes toward Slovakia showed a noticeable improvement. It is viewed positively by 40.7% of respondents, negatively by 12.1%, and neutrally by 44.4%. The balance rose to 28.6 percentage points from 16.1 percentage points in March 2026 and just 1.6 percentage points in August 2025.
The sharpest negative trend was recorded regarding Poland. 34.6% of Ukrainians view it positively, 37% negatively, and 25.4% neutrally. As a result, the net balance stands at minus 2.4 percentage points, whereas in March 2026 it was plus 41.7 percentage points, and in August 2025—plus 44 percentage points. The deterioration in attitudes toward Poland was one of the most notable shifts in the third wave of the survey.
Hungary remains in the negative zone: 22.9% of respondents expressed a positive attitude, 35.6% a negative one, and 37.4% a neutral one. At the same time, its balance improved to minus 12.7 percentage points compared to minus 33.6 percentage points in March and minus 39.7 percentage points in August 2025.
Maksym Urakin, founder of the Experts Club Information and Analytical Center, deputy director of the Interfax-Ukraine news agency, and candidate of economic sciences, emphasized that public perception of countries must be analyzed in parallel with Ukraine’s actual economic ties.
“That is why it is very important for us to analyze our main partners. The first recommendation is to regularly showcase concrete projects, specific actions, and the presence here of foundations, embassies, teams, and diplomats in the humanitarian sphere and in science. We also need to use our sociological data to draw conclusions and strengthen our relations, particularly trade relations,” Urakin noted.
Oleksandr Pozniy, director of the research firm Active Group, highlighted the practical significance of the study’s findings for economic and diplomatic policy.
“We should focus on developing more than just general awareness. First and foremost, business associations, the Ministry of Economy, and the Ministry of Foreign Affairs need to work to develop bilateral relations and improve the balance of trade. We must expand cooperation with countries where we can achieve a positive trade balance,” Pozniy noted.
The survey was conducted in August 2026 using self-administered online questionnaires in the SunFlowerSociology panel among 800 Ukrainian citizens aged 18 and older. According to the organizers, the sample is representative by age, gender, and region, with a maximum theoretical margin of error of 3.5%. This is the third wave of the study, following surveys conducted in August 2025 and March 2026.
ACTIVE GROUP, BULGARIA, Central Europe, CZECH REPUBLIC, EASTERN EUROPE, EXPERTS CLUB, HUNGARY, MOLDOVA, POLAND, Pozniy, ROMANIA, SLOVAKIA, SOCIOLOGY, UKRAINE, URAKIN
Canada ranked first among countries with the highest net positive sentiment among Ukrainians—in August 2026, this figure stood at 73.8 percentage points. The top ten also included mainly countries from Northern and Western Europe, according to the results of the third wave of the study “Ukrainians’ Attitudes Toward Countries Around the World,” conducted by Active Group in collaboration with Experts Club, reports the Experts Club Information and Analytical Center.
Sweden took second place in terms of the balance of trust and distrust with a score of 70.6 percentage points, while the Netherlands came in third with 69.7 percentage points. Finland and Norway each scored 69.3 points, France scored 69.1 points, Italy scored 67.1 points, and Lithuania scored 65.9 points. Rounding out the top ten are Switzerland and the United Kingdom, which both scored 65.6 percentage points.
The sentiment score is calculated as the difference between the proportion of positive and negative ratings. Specifically, 76.3% of respondents view Canada positively, 2.5% negatively, and 19.2% neutrally. Thus, Canada’s high score is due not only to a significant proportion of favorable ratings but also to a minimal level of negative sentiment.
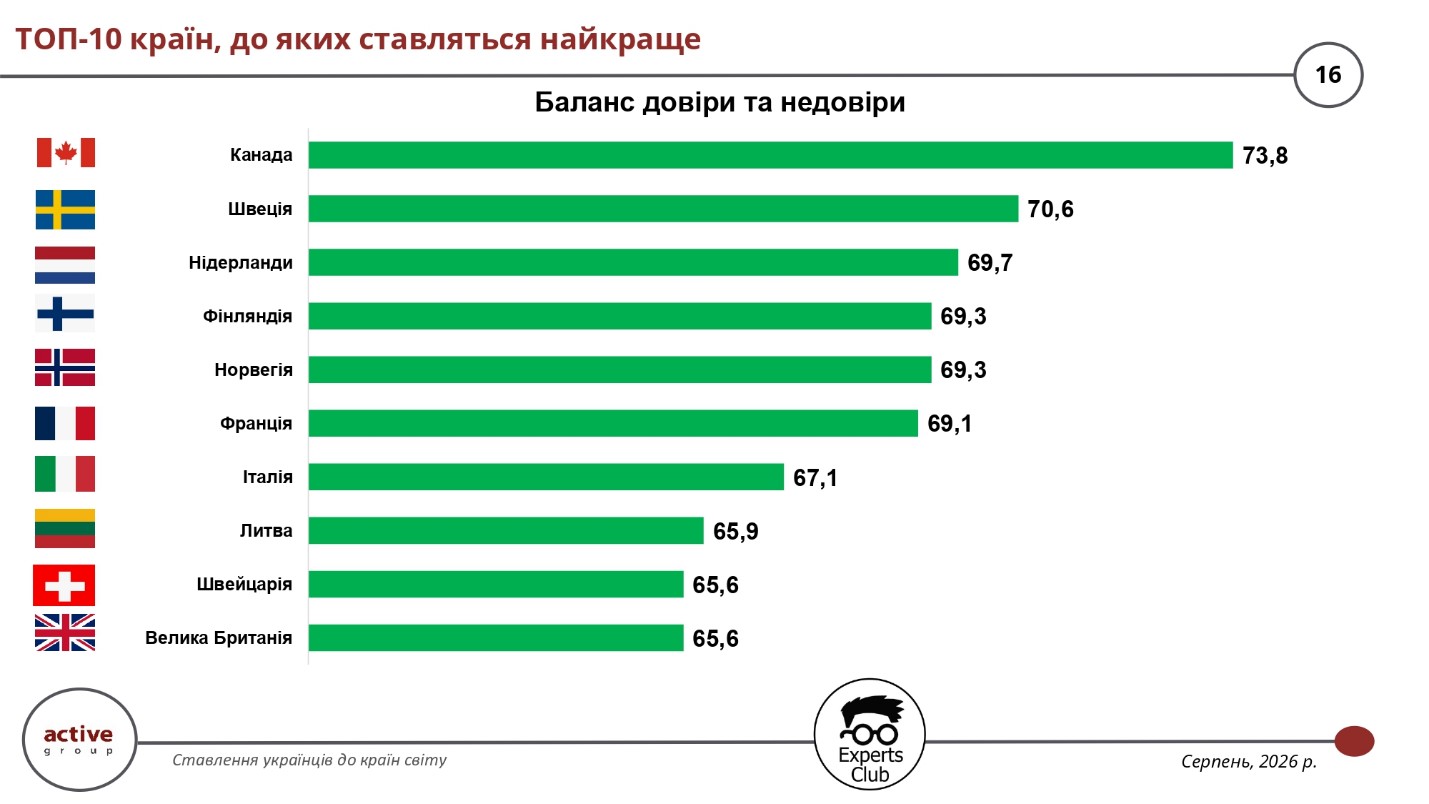
The survey results show that the top ten countries with the most favorable balance of attitudes consist almost entirely of countries in Northern and Western Europe, along with Canada. At the same time, the level of public favor does not always directly correspond to the scale of Ukraine’s trade and economic ties with a specific country. For example, China was Ukraine’s largest trading partner in the first half of 2026, yet it received the lowest balance of positive and negative assessments—minus 25.4 percentage points.
Maksym Urakin, founder of Experts Club, deputy director of the Interfax-Ukraine news agency, and candidate of economic sciences, emphasized that studies of public perception should be considered alongside actual foreign trade indicators.
“That is why it is very important for us to analyze our main partners. We must be open to questions and inquiries from the media and the public,” Urakin noted. According to him, the results of sociological surveys can be used to assess international relations and their further development.
Alexander Pozniy, Director of Active Group, drew attention to the need to combine the creation of a positive image of countries with the practical development of bilateral economic ties.
“We should focus on developing more than just general awareness. We need to expand cooperation with countries where we can achieve a positive balance,” Pozniy noted. According to him, both government agencies and business associations should be involved in this process.
The survey was conducted in August 2026 using self-administered online questionnaires via the SunFlowerSociology panel. A total of 800 Ukrainian citizens aged 18 and older were surveyed. According to the organizers, the sample is representative in terms of age, gender, and region; the maximum theoretical statistical margin of error at a 95% confidence level is 3.5%. This is the third wave of the survey, following surveys conducted in August 2025 and March 2026.
ACTIVE GROUP, CANADA, EXPERTS CLUB, FINLAND, international relations, NORWAY, SOCIOLOGY, SWEDEN, THE NETHERLANDS, UKRAINE, URAKIN
According to Interfax-Ukraine, Ukraine’s economy showed the first signs of emerging from a recession in the first half of 2026, however, the high foreign trade deficit, inflationary pressures, and the dependence of public finances on international aid remain key macroeconomic risks, according to the latest issue of “Economic Monitoring.”
As noted by Maksym Urakin, Ph.D. in Economics and founder of the Experts Club information and analytical center, after real GDP fell by 0.6% year-over-year in the first quarter, the economy returned to growth in April–June.
In the second quarter, Ukraine’s real GDP increased by 0.4% compared with the same period last year and by 0.3% compared with the previous quarter. At the same time, the National Bank’s forecast projected growth of the Ukrainian economy at only 1.3% for the full year of 2026.
“Positive factors in the first half of the year included the resumption of at least minimal GDP growth, the return of international reserves to above $50 billion, stability in the foreign exchange market, more consistent international financing, and the adaptability of Ukrainian businesses. The main risks remain the war, the state of the energy sector, high production costs, a labor shortage, weak commodity exports, and a growing trade imbalance. Ukraine has a significant supply of external liquidity, but it cannot replace domestic economic growth,” Urakin noted.
Consumer inflation slowed to 7.2% in June, while core inflation accelerated to 8.1%. The NBU’s discount rate remained at 15%.
At the same time, after four months of decline, Ukraine’s international reserves increased by 12.1% in June—to $51.27 billion. The NBU’s foreign exchange interventions remained substantial.
Foreign trade remains one of the main structural risks to the Ukrainian economy. From January through June 2026, merchandise imports totaled approximately $49.3 billion, while exports amounted to about $21 billion. Thus, the merchandise trade deficit reached approximately $28.3 billion.
Public finances also remain under significant strain. Revenues to the General Fund of the state budget for the first half of the year totaled nearly 1.9 trillion UAH, while expenditures amounted to approximately 2.23 trillion UAH.
Approximately 1.4 trillion UAH, or about 63% of all General Fund expenditures, was allocated to the security and defense sector. The volume of international grants totaled 569.6 billion hryvnia.
According to Urakin, one of the main objectives of economic policy should be to transform significant imports of equipment, international funding, and defense spending into a foundation for creating new domestic production capacity.
“The next phase of economic policy should consist not only of maintaining financial stability, but also of transforming imported equipment, international funds, and defense spending into new production assets. The foundation for long-term development should be energy self-sufficiency, the defense-industrial complex, agricultural processing, machine building, production localization, logistics, digital technologies, and exports of high-value-added products,” says the founder of Experts Club.
At the same time, the first half of the year revealed significant differences between the world’s largest economies and emerging markets.
The Chinese economy grew by 4.7% in the first six months of 2026, while India posted a growth rate of about 7.8% in April–June.
Turkey continued to combine economic growth with extremely high inflation. In the second quarter, its GDP increased by 2.3% year-over-year and by 1.1% compared to the previous quarter, while annual inflation in June remained near 32%.
Brazil showed more moderate growth: its GDP in the second quarter increased by 2% year-over-year and by 0.5% compared to the previous quarter. In the first half of the year, the country’s economy grew by 1.9%, and annual inflation in June slowed to 4.64%.
“Key emerging economies ended the first half of the year with very different growth patterns. China grew by 4.7%, but its second quarter was weaker than the first, and domestic consumption lags significantly behind industrial output and exports. India continues to grow by nearly 8%, driven by the size of its domestic market and investment. Turkey remains an example of how inflation exceeding 30% limits the quality of economic growth, while Brazil is showing more moderate growth with gradual control of inflation. For Ukraine, the main conclusion remains the same: long-term growth requires its own industrial, technological, and export base,” Urakin emphasized.
In his assessment, the first half of the year confirmed the viability of Ukraine’s macrofinancial stabilization model, but at the same time revealed its limitations.
“The return of GDP to modest growth and the replenishment of reserves are positive signs; however, the $28.3 billion merchandise trade deficit, high underlying inflationary pressures, and the budget’s dependence on external financing reveal the limits of this model. Only by developing its own production and export base will Ukraine be able to transition from an economy of wartime stabilization to a model of sustainable postwar growth,” concluded Maksym Urakin.
“Economic Monitoring” is a monthly analytical and statistical publication led by Maksym Urakin, Ph.D. in Economics. The publication analyzes the main macroeconomic indicators of Ukraine and the world’s leading economies, as well as trends in GDP, inflation, public finances, international reserves, foreign trade, and key risks to economic development.
The expansion of Ukrainian companies into foreign markets increases the importance of conducting preliminary checks on potential buyers and distributors. The risks are particularly high when working with a new counterparty on deferred payment terms, Dun & Bradstreet analysts note.
One of the tools for such checks is Dun & Bradstreet’s (D&B) international business information databases, which make it possible to identify a company, verify its registration data, ownership structure, financial indicators, operating history and associated risks.
When entering a new market, Ukrainian companies often focus primarily on finding a buyer and agreeing on commercial terms, while checking the buyer’s solvency remains a secondary task.
“Receiving an order does not yet mean receiving the money. For an exporter, a situation is particularly dangerous when the first large shipment is made to a new partner with deferred payment. Before signing such a contract, it is necessary to understand whether the company actually exists, how long it has been operating, what its financial indicators are, who its owner is and how high the credit risk associated with this counterparty is,” said Maksym Urakin, Director of Development and Marketing at Interfax-Ukraine, Head of the D&B-Interfax-Ukraine business unit, PhD in Economics.
Dun & Bradstreet has a global database containing information on hundreds of millions of companies. A unique nine-digit D-U-N-S Number is used to identify businesses, making it possible to distinguish between legal entities with similar names and link companies within corporate groups.
For a Ukrainian exporter, such a check is particularly relevant when working with companies that are offering a large contract for the first time, requesting a significant payment deferral or acting as intermediaries between the manufacturer and the end buyer.
Depending on the country and the availability of information, a D&B business report may contain registration details, information about executives and owners, financial statements, information on corporate relationships, credit ratings and other indicators used for risk assessment.
“The cost of a check is almost always incomparable with the potential loss from a single unpaid export shipment. International business information should be viewed not as an additional reference, but as one of the elements of the decision-making procedure regarding the credit limit, the amount of prepayment and the terms of the contract,” Maksym Urakin believes.
At the same time, negative information about a potential partner does not necessarily mean that the transaction should be rejected. It may serve as a basis for changing its terms — increasing the prepayment, reducing the size of the first shipment, using a bank guarantee, trade credit insurance or shortening the deferred payment period.
Dun & Bradstreet is an international provider of business data and analytical solutions whose history began in 1841. The company provides tools for business identification, counterparty verification, assessment of credit and commercial risks, compliance, supply chain management and work with corporate data.
The official representative of Dun & Bradstreet in Ukraine is the Interfax-Ukraine news agency. The specialized D&B-Interfax-Ukraine unit helps Ukrainian companies work with international business data, verify foreign partners and obtain a D-U-N-S Number.
Questions can be submitted through the specialized D&B resource — dnb.ua, by email at Urakin@interfax.kyiv.ua or by phone at +38 (044) 270-65-74.
COUNTERPARTY, D&B, DUN & BRADSTREET, EXPORT, UKRAINE, URAKIN
The US Senate on Friday approved the Lindsey O. Graham Sanctioning Russia and Iran Act of 2026, which significantly expands sanctions pressure on the Russian energy sector and gives the US president the authority to impose tariffs of up to 500% on imports of Russian goods.
The bill was supported by 86 senators, with 11 voting against it, the New York Post reports. The bill must now pass the House of Representatives, which will return from its summer recess on August 31, after which it must be signed by the US president. Until then, the new sanctions and tariffs will not take effect.
The bill is a revised version of a sanctions initiative that Congress has been discussing since 2025. The original version did indeed provide for 500% tariffs for virtually all countries purchasing Russian oil, gas and uranium. In the final Senate version, this mechanism was significantly narrowed.
500% — Directly on Russian Goods
If the law takes effect, the US president will be required within 30 days to receive the authority to raise tariffs on all goods of Russian origin imported into the United States to 500% of their value.
The text specifically lists oil, natural gas, LNG, petroleum products, petrochemical products, coal and other Russian goods.
Moreover, these tariffs will be imposed in addition to existing US tariffs, anti-dumping duties and other charges.
In practice, a 500% tariff effectively makes most direct Russian exports to the United States commercially meaningless.
For example, with a customs value of $1 million, the additional tariff could theoretically reach $5 million.
However, the significance of this mechanism for Russian exports is limited by the fact that direct trade between Russia and the United States has already declined substantially following the introduction of previous sanctions.
The second mechanism — the so-called secondary tariffs — could prove considerably more significant for global trade.
The president will be able to impose tariffs of up to 100% on all goods imported into the United States from countries that rank among the five largest purchasers of Russian oil or natural gas.
For a country to fall under this mechanism, it must continue making new purchases of Russian commodities 30 days after the law takes effect and simultaneously rank among the top five importers by volume over the previous 12 months.
China and India are primarily at potential risk. Reuters notes that, depending on the structure of supplies, certain European countries and Japan could also be included in the relevant list. The law itself does not name specific countries in advance.
This means that the tariff would not apply to the Russian oil purchased, for example, by India, but potentially to all Indian exports to the United States.
This is precisely why the mechanism is a significantly more serious instrument of pressure than conventional sanctions against Russian companies.
In simple terms, a country is given a choice — continue large-scale purchases of Russian energy and risk access for its goods to the US market, or reduce imports from Russia.
Separately, the law allows tariffs of up to 100% to be imposed against the five largest countries that, according to the US assessment, facilitate the circumvention of sanctions on Russian oil.
Thus, the sanctions mechanism applies not only to buyers of Russian commodities, but also to countries through which schemes involving their resale, transportation or concealment of origin may operate.
In addition, the bill provides for additional sanctions against Russia’s “shadow fleet” — tankers and companies associated with them that are used to transport Russian energy resources in circumvention of Western restrictions.
US authorities will be required to review the list of the largest buyers and potential violators every 180 days, meaning that the composition of countries at risk may change along with trade flows.
The bill includes a provision for countries importing Russian natural gas.
Tariffs may not be applied if the respective country accounts for less than 15% of Russia’s total natural gas exports and simultaneously takes substantial steps to reduce its dependence on Russian gas.
This provision is particularly important for European countries that still receive some Russian gas but are gradually reducing their purchases.
The widely circulated claim about additional 100% tariffs on the largest buyers of Russian uranium does not correspond to the current version of the bill. In the original version, uranium did indeed feature in the mechanism of 500% secondary tariffs. However, following negotiations with the White House, this mechanism was changed.
In the current document, Russian uranium is regulated separately.
The law requires the implementation of restrictions on imports of Russian uranium into the United States and provides for sanctions against the leadership, management and controlling shareholders of Rosatom and entities associated with it.
Tariffs Are Only One Part of the Package
The law provides for mandatory sanctions against Russia’s top political and military leadership, a number of major Russian financial institutions, state-owned companies and foreign persons supporting the Russian military-industrial complex.
The official overview of the bill specifically names the Central Bank of the Russian Federation, Sberbank and Gazprombank.
The sanctions also apply to major energy projects, including Yamal LNG, Arctic LNG 1, Arctic LNG 2 and Arctic LNG 3, as well as future Russian projects in the Arctic.
US persons will be prohibited from making new investments in Russia and the Russian energy sector, purchasing Russian sovereign debt, making certain financial transfers to the Russian state, as well as exporting US energy products to Russia.
Another important feature of the law is that the president will have the ability to adjust the intensity of secondary tariffs.
The rate may range from zero to 100%, depending on the behavior of a particular country and the volume of its purchases of Russian energy.
If a country reduces its purchases, the US Trade Representative will be able to lower the tariff. If imports increase, the pressure may be intensified.
The president will also have the right to temporarily waive the application of certain sanctions or tariffs if he formally certifies to Congress that such a step is in the national interests of the United States.
Thus, the new law is not an automatic trade blockade of China, India or other buyers of Russian oil, but rather an instrument that the White House will be able to use to exert pressure in negotiations.
The Iranian part of the bill is somewhat different in nature.
The package includes a five-year extension of existing US sanctions authorities against Iran’s energy and weapons sectors, which were due to expire at the end of 2026.
Therefore, the claim that Russia and Iran will face an entirely identical regime of “500% sanctions” is incorrect.
The main new tariff mechanism is specifically directed against Russia and the largest buyers of Russian energy resources, while the Iranian part primarily preserves the United States’ existing sanctions authorities.
Why the New Mechanism Is Considered Particularly Tough
The key idea of the law is to exert pressure not only directly on the Russian economy but also on buyers of Russian commodities.
After 2022, Russia redirected a significant portion of its oil exports from Europe to Asia. Therefore, restricting only the US or European market does not stop oil revenues from flowing into the Russian budget.
The new mechanism attempts to change this situation through access to the US market.
For major exporters such as China and India, a potential tariff of up to 100% on goods supplied to the United States could carry far greater economic weight than the benefit obtained from purchasing discounted Russian oil.
This is why the authors of the bill expect to confront the largest buyers with an economic choice between trading with Russia and maintaining full access to the US market.
At the same time, the consequences of such a mechanism could also be significant for the US economy itself. Reuters reported that some Democrats and Republicans are concerned about rising import costs, retaliatory trade measures and an excessive expansion of the president’s tariff powers.
EXPERTS CLUB, SANCTIONS AGAINST RUSSIA, SECONDARY TARIFFS, URAKIN, US SANCTIONS



