
Ukraine’s European integration could become one of the key factors in attracting investment in the restoration of infrastructure and the construction industry through access to specialized European Union development funds. At the same time, the state must already create conditions for Ukrainian building materials manufacturers and construction companies to participate in international reconstruction projects.
This was stated by Andriy Ozeychuk, director of the engineering and construction company Rauta, during the Infrastructure Forum, the company’s press service reported.
According to Ozeychuk, the main potential sources of financing for large-scale reconstruction projects in Ukraine are assistance from international partners, private investment and possible future reparations from Russia.
“Ukraine’s future European integration will become a powerful incentive for financing construction. It will open access to specialized EU development funds similar to those that transformed the infrastructure of Central and Eastern European countries after they joined the Union,” the Rauta director emphasized.
In his opinion, Ukraine’s integration into the European economic area will create additional opportunities for modernizing transport, energy, industrial and social infrastructure. At the same time, the effectiveness of using future financing will largely depend on the readiness of Ukrainian enterprises to compete with European companies.
Ozeychuk noted that, to increase the competitiveness of the domestic construction sector, it is necessary, first and foremost, to ensure access to long-term lending for investment projects and affordable financial resources for modernizing production facilities.
He also identified accelerating the implementation of European technical standards in construction and facilitating Ukrainian companies’ access to international financing programs as equally important tasks.
According to the Rauta executive, such mechanisms will enable Ukrainian building materials manufacturers and contractors to compete on equal terms with foreign participants in the implementation of reconstruction projects.
In particular, affordable financing for production modernization can contribute to upgrading equipment, increasing enterprise productivity and expanding the range of products needed to restore destroyed infrastructure.
The implementation of European standards, in turn, is an important prerequisite for Ukrainian manufacturers’ participation in international construction projects and the supply of products to the EU market.
The Infrastructure Forum, held on October 14, brought together industry representatives to discuss the development and modernization of Ukraine’s infrastructure. Issues of financing reconstruction and involving Ukrainian businesses in the implementation of major projects were discussed, in particular, during the event’s third session.
Rauta is a Ukrainian engineering and construction company specializing in the design and construction of industrial, commercial and residential facilities, as well as the supply of sandwich panels, steel frames, facade systems and prefabricated buildings. The company is the exclusive supplier to Ukraine of commercial construction products manufactured by the Finnish group Ruukki. Rauta director Andriy Ozeychuk also chairs the board of directors of the Ukrainian Steel Construction Center association.
CONSTRUCTION, INFRASTRUCTURE, INVESTMENT, RECONSTRUCTION, UKRAINE
S1 REIT, an investment company that is part of S1 Group, has begun selling certificates for its new S1 Poznyaki investment fund with a minimum initial investment of 1,000 UAH and the option to make additional contributions starting at 100 UAH. The total issue volume of the certificates is 250 million UAH, the company reported in a press release published on November 2, 2026.
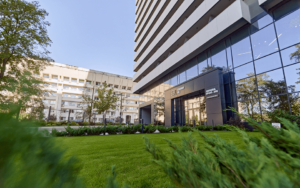
According to the announcement, the fund will invest in 80 apartments with a total area of 2,828 thousand square meters in the 24-story S1 Poznyaki residential building, which is under construction near Lake Sribny Kil in the Darnytskyi district of Kyiv, approximately two minutes from the “Poznyaki” metro station.
The total area of the building will be 29,500 square meters. Construction is scheduled to be completed and the property commissioned by the end of 2028.
The fund’s projected annual return is 9% in U.S. dollars; however, the company emphasizes that this figure is based on the project’s financial model and does not guarantee future profits.
The investment model envisages two stages of income generation. During construction, the expected increase in property value should be reflected in the price of investment certificates, while dividend payments are not anticipated at this stage.
Once the building is commissioned and apartments begin to be rented out, rental income is expected to become the source of dividends for certificate holders.
In addition, investors will be able to gradually accumulate certificates with the option of exchanging them for completed apartments in accordance with the fund’s terms.
“You don’t have to wait until you’ve saved up enough for an entire property. You can start with 1,000 UAH and buy additional certificates when you have the opportunity. Then you can choose your own path: remain a fund investor to receive future rental income or gradually work toward owning your own apartment,” said Viktor Boichuk, Commercial Director of S1 REIT.
According to Igor Gifes, CEO of S1 REIT, the launch of the fund allows investors to invest in real estate during the construction phase and count on potential appreciation in value upon project completion.
The S1 Poznyaki building is being developed as a “Build-to-Rent” project—real estate designed to be leased out.
The project includes approximately 1,500 square meters of internal infrastructure, including a coworking space, a gym, a movie theater, a children’s playroom, recreation areas, and a fully equipped shelter. Another approximately 7,000 square meters on the ground floors is allocated for commercial spaces and service facilities.
Once the building is commissioned, S1 Property will manage the property.
The sale of investment certificates is organized through online applications on the S1 REIT website.
The company specifically highlights the risks associated with investing, particularly those related to military actions, construction timelines, and market conditions. The projected return does not guarantee the preservation of the invested capital.
S1 REIT is part of S1 Group and specializes in collective investments in income-generating real estate in Kyiv. The group also includes the developer Standard One and the property management company S1 Property.
Source: S1 REIT press release dated November 2, 2026, published by Interfax-Ukraine.
CONSTRUCTION, INVESTMENT, KYIV, REAL ESTATE, RENTAL, S1 REIT
The business confidence index in Ukraine’s construction market fell by 1.9 percentage points (pp) in the fourth quarter of 2026 compared to the third quarter, reaching “minus” 23.4%, according to the State Statistics Service (SSS).
According to a survey of construction companies conducted by the agency, the assessment of current order volumes worsened by 2 p.p. to “minus” 37.2%. Specifically, 59% of the surveyed companies rated their current order volumes as normal for the season, while 40% rated them as insufficient.
Sixty-two percent of respondents expect to raise prices for their services by the end of the fourth quarter of this year. Five percent of respondents forecast a decrease in the cost of construction work, while 33% do not expect any changes in pricing policy.
According to data from the State Statistics Service, the companies participating in the survey have an average of six months’ worth of orders, which corresponds to the pre-war level at the beginning of 2022.
The statistical agency notes that in the fourth quarter of 2026, construction will be negatively impacted by labor shortages (53.9%), financial constraints (50.8%), insufficient demand (20.8%), and other factors (44.7%).
About 28% of the surveyed companies expect a reduction in their workforce in October–December, while 58% believe their workforce will remain unchanged, and 13% forecast an expansion of their staff.
According to the State Statistics Service, 36% of respondents reported an increase in the volume of construction work completed in the past quarter, while 27% reported a decrease.
The survey showed that 99% of Ukrainian construction companies find it quite difficult to predict future business developments.
The statistical data does not include territories temporarily occupied by the Russian Federation or parts of territories where hostilities are (or were) taking place.
Source: https://stat.gov.ua
The Cyprus Property Developers Association (CPDA) has spoken out against proposed restrictions on real estate purchases by citizens of countries outside the European Union, stating that foreign buyers are not the main cause of rising housing prices on the island.
Developers consider the main problems in the market to be an insufficient supply of affordable housing, a shortage of construction workers, and high construction costs, according to a report by the Cypriot publication Philenews on October 27, 2026.
According to the association’s estimates, foreign buyers account for about 20% of housing sales in Cyprus, so it is unreasonable to place the primary blame for rising prices on them.
Representatives of the construction industry also pointed out the lack of reliable, unified statistics on housing that is actually available for sale. According to them, government agencies rely on data regarding issued building permits, which do not reflect the actual number of properties remaining on the market.
In particular, a significant portion of apartments may be sold while still in the design phase or while permit documentation is being obtained.
The association provides a hypothetical example: if permits have been issued for the construction of 10,000 properties, but 5,000 of them have already been sold, the actual supply available to new buyers is only half of the stated number.
As a result, using building permit statistics without accounting for pre-sales can create an inflated perception of the supply volume and lead to misguided decisions in housing policy.
An additional problem remains the shortage of construction workers. According to developers’ estimates, the labor shortage limits the industry’s potential and extends project completion times, even when all necessary permits have already been obtained.
The association has called on the authorities to conduct a comprehensive analysis of the existing housing stock, the actual supply, and the structure of demand before imposing additional restrictions on buyers from third countries.
At the same time, data from Cyprus’s Department of Lands and Surveys (DLS) indicate the significant role of foreign demand in the real estate market.
From January through September 2026, 14,969 real estate purchase agreements were registered in Cyprus, which is 13.6% more than during the same period in 2025.
Of this total, 6,267 agreements, or approximately 41.9%, were concluded by foreign buyers. Citizens of non-EU countries made 4,173 purchases, while buyers from EU countries concluded 2,094 contracts.
Thus, third-country nationals accounted for about 27.9% of all registered real estate purchase and sale contracts and approximately two-thirds of foreign purchases.
The discrepancy between developers’ estimates of 20% and the statistics on registered contracts is explained, in part, by the use of different metrics. A real estate purchase and sale contract may be registered before construction is completed, while the actual transfer of ownership occurs later.
According to DLS data for January–July 2026, 2,683 properties were transferred to foreign buyers, or about 20.9% of all properties for which the registration of the transfer of ownership was completed.
Therefore, the figures for contracts signed and transactions completed cannot be directly compared as identical statistical categories.
The highest concentration of foreign demand is observed in coastal areas. From January through September 2026, foreign buyers signed 2,117 contracts in Paphos, 1,814 in Limassol, and 1,543 in Larnaca.
At the same time, the share of foreign buyers in the total number of purchase and sale contracts in Paphos reached approximately 71%, in Larnaca—47%, while in Nicosia it stood at about 16%.
This indicates significant regional differences in the structure of demand and explains why a potential tightening of rules governing real estate purchases by foreigners could have a stronger impact on coastal markets.
The debate surrounding foreign demand has intensified following the introduction of legislative initiatives in the Cypriot Parliament aimed at restricting real estate purchases by citizens of non-EU countries and foreign-controlled companies.
In particular, representatives of the AKEL party proposed limiting such citizens to the purchase of no more than one residential property with an area of up to 200 square meters, as well as restricting the purchase of certain categories of commercial real estate.
Additional proposals call for stricter oversight of the ultimate beneficiaries of companies purchasing real estate and restrictions on the acquisition of properties near strategic infrastructure.
Supporters of the changes attribute the need for additional regulation to rising housing costs and declining affordability for the local population.
However, the developers’ association believes that the legislative proposals are not sufficiently supported by statistical research.
According to developers, there is no data confirming the mass purchase of more than two residential properties by a single foreign buyer. Therefore, limiting the number of purchases may have a limited impact on real estate prices.
At the same time, growing foreign demand is one of the factors influencing the market. The Central Bank of Cyprus has previously noted that the rise in housing prices is driven by a combination of stable demand—particularly from foreign buyers—and rising construction costs.
According to the regulator, in the first quarter of 2026, residential real estate prices rose by 7.5% year-over-year; specifically, apartment prices increased by 10.8%, while single-family home prices rose by 3%.
Foreign demand for real estate in Cyprus is traditionally driven by several large groups of buyers, including citizens of the United Kingdom, Russia, Greece, Israel, and Lebanon.
According to data from the Cypriot Ministry of the Interior presented to Parliament in January 2025, foreign buyers purchased more than 37,000 properties between 2021 and 2024. During the same period, Cypriot citizens purchased more than 200,000 properties.
British citizens accounted for the largest number of purchases by foreigners during this period. They were followed by large groups of buyers from Russia, Israel, Greece, and Lebanon.
According to previously published estimates by Open4Business based on data from the Cypriot Ministry of the Interior, British buyers were associated with approximately 11,800 properties, Russians with 4,900, Greek citizens with 4,700, Israeli citizens with 3,900, and Lebanese citizens with 2,100 properties.
At the same time, the structure of foreign demand varies significantly by region.
In Limassol, Russians led the way from 2021 to 2024, purchasing 2,561 properties, followed by British buyers with 1,840 properties and Israelis with 1,154.
In Paphos, the main foreign buyers were citizens of the United Kingdom with 4,483 properties, Russia with 1,563, and Israel with 1,291.
In Larnaca, the largest groups were British buyers with 2,743 properties, citizens of Lebanon with 1,744, and Israel with 1,406.
In Nicosia, Greek citizens ranked first among foreign buyers, purchasing 1,626 properties, followed by British citizens with 1,584 and Australians with 545.
The latest data from the Cypriot Ministry of the Interior for the period from September 2024 to September 2025 indicates growing interest among Israeli buyers in Larnaca and Paphos.
Specifically, during this period, Israelis purchased 850 properties in Larnaca and 683 in Paphos. In Limassol, Russians remained the largest group with 846 purchases, while in Paphos, British buyers led the way with 890 properties.
Ukrainian citizens are also among the notable participants in the Cypriot real estate market. In previously published rankings for 2021–2024, Ukraine appeared in the top ten countries of origin for foreign buyers, ranking ninth.
According to market participants, Ukrainian buyers are most interested in real estate in Limassol and Paphos, particularly apartments for permanent residence and investment properties.
At the same time, the latest DLS statistics for 2026 categorize foreign buyers primarily as EU citizens and third-country nationals, without providing a complete, publicly available breakdown by specific nationalities. Therefore, it is impossible to reliably determine the current number of purchases made by Russians, Ukrainians, or Israelis from January through September 2026 based on this data.
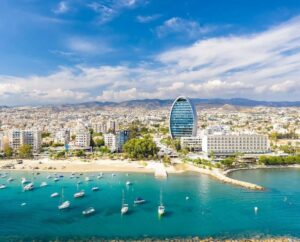
The Republic of Cyprus has been a member of the European Union since 2004. The main centers of the country’s residential real estate market remain Limassol, Paphos, Larnaca, and Nicosia. Foreign demand is particularly noticeable in coastal areas, where a significant portion of new construction is geared toward international buyers and investors.
CONSTRUCTION, CYPRUS, foreign buyer, INVESTMENTS, REAL ESTATE
Prices for construction and installation work in Ukraine rose by 25.4% in August 2026 compared to August 2025, according to the State Statistics Service (State Statistics Service).
According to the statistics agency, prices rose across all segments of construction from August 2026 to August 2025: in residential construction by 21.5% (up 1.3% from the previous month), in non-residential construction by 26.4% (2%), and in civil engineering by 26.1% (1.6%).
From January through August of this year compared to the same period last year, construction material and equipment prices rose by 18%; specifically, in the residential sector by 15.5%, in the non-residential sector by 18.7%, and in civil engineering by 18.4%.
As previously reported, in 2025, construction material prices rose by 5.8% compared to the previous year; in 2024, by 7.9%; and in 2023, by 15.8%.
CONSTRUCTION, CONSTRUCTION MATERIALS, PRICE, State Statistics Service, UKRAINE
The volume of construction work completed in Ukraine from January through August 2026 decreased by 9.9% compared to January through August 2025, according to data from the State Statistics Service (Derzhstat).
According to the statistical agency, the volume of construction output in January–August totaled 156.5 billion hryvnias.
According to the State Statistics Service, over the eight-month period, the volume of residential construction decreased by 3.8% compared to January–August of last year, nonresidential construction by 6.3%, and civil engineering structures by 13.7%.
In August 2026, compared to August 2025, construction volumes decreased by 3.7%, including residential construction by 2.3% and civil engineering structures by 12.2%. At the same time, construction volumes for non-residential buildings increased by 9.8%.
In August 2026, compared with the previous month, construction volumes increased by 12.9%; specifically, in the residential category by 0.2%, in nonresidential buildings by 25.3%, and in civil engineering structures by 8.8%.
According to the agency’s seasonally adjusted data, construction output indices in August 2026 stood at 62% for residential construction, 155% for nonresidential construction, and in civil engineering at 112%; taking into account the calendar-day effect, the figures were 63.1%, 156.5%, and 115.4%, respectively.
The share of new construction in the total volume of construction work completed in July was 44.6%, repairs—30.3%, and reconstruction and other work—25.1%.
CONSTRUCTION, INFRASTRUCTURE, REAL ESTATE, State Statistics Service, UKRAINE



