
Pharmacy sales in Ukraine from January to June 2026 increased by 15% in monetary terms compared to the same period in 2025—reaching nearly 121 billion hryvnia—while in volume terms, they decreased by 5.8%—to approximately 533.955 million packages.
The company “Business Credit” reported this to the Interfax-Ukraine news agency, citing the results of a study it conducted.
The weighted average price of items in the pharmacy basket for the first half of the year was 226.65 UAH per package, which is 22.15% higher than in January–June 2025.
Thus, the growth of the pharmacy market in monetary terms occurred against the backdrop of a decline in the total number of packages sold and a significant increase in the average cost of pharmacy products.
At the same time, the market’s growth rate in monetary terms accelerated compared to the first quarter. In January–March, pharmacy sales increased by 11.13%—to 60.245 billion UAH—while the volume of sales decreased by 4.8%, to approximately 270.958 million packages.
At the end of 2025, pharmacy sales in Ukraine totaled over 220.287 billion UAH, which is 14.23% more than in 2024. In volume terms, they declined by 2.25% during that period.
The weighted average price of dietary supplements in Ukrainian pharmacies from January through June 2026 rose by 36.36% compared to the same period last year—to 321.79 UAH per unit. This was reported to the Interfax-Ukraine news agency by Business Credit, citing the results of a pharmacy market study.
Sales of dietary supplements in monetary terms for the first half of the year increased by 15.77%—to nearly 13.516 billion UAH.
At the same time, in volume terms, sales decreased by 15.1%—to 42 million packages.
Thus, the increase in the monetary value of the dietary supplement market was accompanied by a sharp decline in the volume of goods sold and a significant rise in their average price.
By comparison, the average price of the total pharmacy shopping basket during this period rose by 22.15%—to 226.65 UAH per package—while the average price of prescription drugs increased by 13.96%, to 233.85 UAH. Thus, dietary supplements became one of the segments of the pharmacy market with the most noticeable increase in average retail price.
Ukraine exported $14.1 billion worth of food products in January–July 2026, according to data from the State Customs Service. Based on calculations using State Customs Service statistics, food products accounted for about 58.5% of Ukraine’s total merchandise exports, which amounted to $24.1 billion over the seven-month period.
Metals and metal products ranked second among export categories at $2.5 billion, or slightly more than 10% of total exports.
Machinery, equipment, and transportation vehicles were exported in the amount of $2.1 billion, corresponding to approximately 8.7% of total exports.
Thus, food products, metal products, and machinery collectively accounted for about 77.6% of Ukraine’s merchandise exports.
Poland remained the largest market for Ukrainian goods over the seven-month period, with $2.8 billion worth of products shipped there. Exports to Turkey totaled $2 billion, and to Germany—$1.5 billion.
Overall, Ukrainian exports in January–July 2026 grew by 3.8% compared to the same period last year—rising to $24.1 billion from $23.2 billion.
At the same time, imports grew much faster—by 26.6%, to $58.1 billion.
An investigating judge of the High Anti-Corruption Court (HACC) partially granted the motion filed by the defense team of Andriy Yermak, former head of the Office of the President, and eased his pretrial restrictions, allowing him to travel from Kyiv and the Kyiv region to a number of other regions, according to a press release from the Special Anti-Corruption Prosecutor’s Office (SAPO).
“On August 10, 2026, the investigating judge partially granted the motion filed by the defense attorneys of the former head of the Office of the President of Ukraine—who is suspected of laundering assets obtained through criminal means during the construction of a private cottage community near Kyiv—and modified the procedural obligations previously imposed on him,” the SAP stated in a Telegram post on Monday.
Yermak was permitted to travel outside Kyiv and the Kyiv region to the Dnipropetrovsk, Donetsk, Zaporizhzhia, Mykolaiv, Sumy, Kharkiv, and Kherson regions, with the option of transit. “Thus, the obligation not to leave Kyiv and the Kyiv region without the permission of a detective, prosecutor, or court has been replaced with the obligation not to leave the boundaries of Kyiv, the Kyiv, Dnipropetrovsk, Donetsk, Zaporizhzhia, Mykolaiv, Sumy, Kharkiv, and Kherson regions without such permission, with the possibility of transiting through other regions,” the SAPO stated in its announcement.
The defense explained that the trips to these regions were related to the suspect’s participation in a project providing legal assistance to military personnel. The defense’s decision to file this motion with the court was prompted by the simultaneous receipt by the SAPO and NABU of a series of letters with similar content from military unit commanders on behalf of the suspect.
The court denied the defense’s motion to remove Andriy Yermak’s electronic ankle monitor (a monitoring device).
As previously reported, on May 11, NABU and the SAP announced the exposure of an organized group suspected of laundering 460 million hryvnias through an elite construction project near Kyiv—one of the participants in the scheme was former Presidential Office head Yermak, who was formally charged. On May 12, anti-corruption authorities announced that six more members of the organized group had been charged in this case, including a former deputy prime minister and a businessman (one of the leaders of the criminal organization exposed in November 2025 as part of the “Midas” special operation). These are likely businessman Timur Mindich and former Deputy Prime Minister of Ukraine Oleksiy Chernyshov.
According to the investigation, between 2021 and 2025, the suspects “laundered” over 460 million hryvnias through the construction of a cottage community in Kozin, Kyiv Oblast. The project involved the construction of four private residences with auxiliary buildings and structures, as well as a spa area (the so-called “Dynasty Cooperative”), on land plots with a total area of approximately 8 hectares.
On May 14, the High Anti-Corruption Court imposed a pretrial detention order on Yermak, with the right to post bail in the amount of 140 million hryvnias. On May 18, the full bail amount was posted for Yermak, and he was released from pretrial detention.
COURT, High Anti-Corruption Court, pretrial detention, Specialized Anti-Corruption Prosecutor’s Office, ЄРМАК
According to Fixygen, the cryptocurrency market ended last week mostly on an uptrend: Bitcoin rebounded from its early August decline and once again tested the $65,000 mark, while Ethereum and most of the major altcoins also gained ground. The exception among the leading cryptocurrencies was XRP, which lost about 5% over the week.
As of the morning of August 10, Bitcoin was trading at around $65,200 and had risen by approximately 3.7% over the past seven days, according to CoinDesk data. On Monday, the price fell back below $65,000—to around $64,500–$64,700. As of August 7, BTC was up 3.1% for the week, heading toward its first weekly gain in three weeks.
Ethereum was trading around $1,900 at the start of the new week and also ended the week with gains. BNB and Solana were in positive territory, while XRP lagged behind the broader market recovery and lost about 5%.
One of the main supporting factors was the return of institutional demand. U.S. spot Bitcoin ETFs saw $853.54 million in net inflows last week, marking the strongest weekly result since mid-April. A significant portion of the funds went to BlackRock’s IBIT fund.
The combined net inflow into U.S. spot Bitcoin and Ethereum ETFs for the week is estimated at approximately $1.1 billion. Back in early August, the situation was the opposite: Bitcoin ETFs had ended the previous week with a small net outflow, so the return of major buyers became one of the key shifts in the market landscape.
U.S. macroeconomic data provided additional support for cryptocurrencies. Weak U.S. labor market data eased concerns about a possible further increase in the Fed’s interest rates and bolstered demand for risky assets. Following the release of the data, Bitcoin rose to $65,000, while U.S. stock indices finished the week on a strong note.
However, it is still too early to speak of a full-fledged return to a sustained bullish trend. Bitcoin remains near the $62,000–$65,000 range, where it has spent much of the past few weeks. Analysts note that a sustained market recovery would require a break above the $65,000 level.
Another sign of caution is the extremely low realized volatility. Last Saturday, BTC’s trading range was only about $350—the narrowest Saturday range since November 2023. At the same time, the options market continues to see elevated demand for downside protection around the $62,000–$63,000 range, indicating ongoing concerns among market participants.
News of the sale of bitcoins by Strategy, the largest corporate holder, also acted as a restraining factor. The company reported on August 10 that it had sold 1,690 BTC for approximately $108.6 million the previous week, using the proceeds, in part, to repurchase preferred shares. Its holdings have decreased to 840,447 BTC.
Regulatory factors, on the other hand, are likely to take a back seat by the end of August. The U.S. Senate failed to pass the CLARITY Act before Congress’s August recess began. Lawmakers are not expected to resume consideration of comprehensive regulations for the digital asset market until at least mid-September.
What Will Drive the Market Through the End of August
The first major test will be U.S. inflation data. The U.S. Consumer Price Index for July is scheduled for release on August 12, the Producer Price Index on August 13, and retail sales data on August 14. Following weak employment data, inflation figures could shape expectations regarding the Fed’s future policy and, consequently, the direction of Bitcoin and other risky assets.
The next key date will be August 19, when the Federal Reserve releases the minutes of the July 28–29 FOMC meeting. Investors will be looking for additional signals in the minutes regarding the extent to which the central bank is concerned about the combination of rising inflation and a softening labor market.
The last week of August will be even more eventful. On August 26, the U.S. will simultaneously release the second estimate of second-quarter GDP and July statistics on personal income and spending, including the PCE price index—one of the Fed’s key inflation benchmarks.
From August 27 to 29, the Kansas City Federal Reserve Bank will hold its annual symposium in Jackson Hole. In 2026, the symposium’s theme is directly related to financial markets: “Financial Innovation: Implications for Payments and Policy.” Therefore, statements by central bank leaders may be of particular significance for the cryptocurrency sector as well.
Two main scenarios can be identified for the market through the end of August. Assuming continued capital inflows into ETFs, more moderate inflation in the U.S., and sustained expectations of a neutral or more dovish Fed policy, Bitcoin will have the opportunity to consolidate above $65,000 and attempt to return to July’s levels above $66,000. This is a conclusion based on the current market structure, not a guaranteed price forecast.
The negative scenario is primarily linked to an unexpected acceleration of inflation in the U.S., rising bond yields, and a renewed escalation of geopolitical risks surrounding the Middle East and the Strait of Hormuz. In that case, market attention will shift back to the $62,000–$63,000 range, where options traders are currently actively hedging against a decline.
Thus, the crypto market is entering the second half of August in a stronger position than at the beginning of the month: institutional inflows have resumed, Bitcoin has recouped a significant portion of its recent losses, and most of the largest altcoins have turned bullish. However, low volatility and the concentration of several key macroeconomic events in the second half of the month set the stage for a noticeable increase in price fluctuations by the end of August.
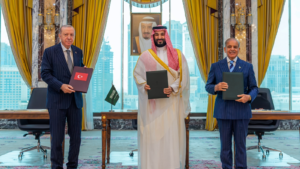
The signing of the “Mecca Joint Defence Agreement” by Saudi Arabia, Türkiye and Pakistan could become one of the most significant changes to the security architecture of the Middle East and South Asia in recent years, Experts Club analysts believe.
The agreement was signed on August 7, 2026, by Saudi Crown Prince Mohammed bin Salman, Turkish President Recep Tayyip Erdoğan and Pakistani Prime Minister Shehbaz Sharif after almost a year of negotiations.
The document’s main principle effectively replicates the basic logic of NATO’s collective defence: an armed attack against one participant must be regarded as an attack against all three.
On August 8, Turkish Foreign Minister Hakan Fidan directly compared this mechanism with Article 5 of the North Atlantic Treaty. At the same time, he stressed that the agreement was not directed against Iran or any other specific country.
However, the political geography of the three participants makes it possible to identify several areas that may have influenced the creation of the new security mechanism.
Iran is the most immediate factor behind the formation of the alliance.
Saudi Arabia and Iran have competed for influence in the Middle East for decades, despite the restoration of diplomatic relations mediated by China. Following a new escalation of the regional conflict in 2026, the security of Saudi Arabia, the oil infrastructure of the Persian Gulf and maritime routes once again became a central concern for Riyadh.
Reuters links the signing of the agreement specifically to growing regional instability and threats to the Persian Gulf states. At the same time, Iran has already reacted rather critically to the creation of the new mechanism.
According to Experts Club, deterring a possible expansion of the regional conflict surrounding Iran should be regarded as the first function of the new agreement.
However, this does not mean the creation of a classic “anti-Iranian NATO.” Pakistan maintains its own relations with Tehran and shares a border with Iran, while Türkiye is interested in preserving economic and political channels of interaction with it.
It is therefore more advantageous for all three states to formulate the agreement as a universal system of collective protection without naming an adversary.
The second area is connected with Israel.
Israel’s growing military autonomy and the expansion of its operations in the region are causing concern not only in Iran but also among a number of Arab and Muslim states.
Reuters notes that the participating countries are concerned both about Iran’s actions and Israel’s military policy.
At the same time, the participants’ relations with Israel differ substantially.
Pakistan officially has no diplomatic relations with Israel. Turkish-Israeli relations have repeatedly gone through periods of sharp deterioration in recent years. Saudi Arabia, by contrast, had long considered the possibility of normalising relations with Israel, although regional wars have significantly complicated this process.
The issue is therefore less about preparing an anti-Israeli military alliance than about attempting to create an independent centre of power capable of limiting the unilateral dominance of any regional player.
The third area is considerably more complicated — India.
For Pakistan, India remains its principal long-term strategic adversary. Both countries possess nuclear weapons, and another serious armed clash between them occurred in 2025. SIPRI specifically notes that the India-Pakistan confrontation remains one of the factors contributing to global nuclear risk.
Türkiye traditionally maintains close political and defence relations with Pakistan, while disagreements between Ankara and New Delhi have repeatedly intensified because of Türkiye’s position on Kashmir.
However, it would be an exaggeration to regard the new trilateral agreement as being directly aimed against India.
Saudi Arabia is simultaneously developing a strategic partnership with New Delhi. India is a major consumer of Saudi oil, while cooperation between the two countries encompasses investment, energy, security and defence contacts.
Riyadh is therefore unlikely to be interested in turning the agreement into an automatic Pakistani instrument against India. It is more likely that the treaty gives Islamabad additional political weight and potential support from its partners, but the application of the collective defence principle in the event of a new India-Pakistan crisis will become one of the main tests of the agreement’s actual substance.
The principal distinguishing feature of the new triangle is that one of its countries is a nuclear power.
Pakistan possesses nuclear weapons. According to estimates by Western research centres, its arsenal comprises approximately 170 nuclear warheads. SIPRI classifies Pakistan among the world’s nine nuclear-armed states and notes the continued modernisation of its nuclear capabilities.
However, the text of the agreement does not indicate that Pakistan is providing Saudi Arabia or Türkiye with a so-called nuclear umbrella. This is fundamentally important.
The very participation of a nuclear power increases the political value of the deterrence mechanism, but no automatic obligations to use nuclear capabilities in the interests of the partners have been publicly announced.
In this sense, the agreement creates strategic ambiguity rather than a formal system of extended nuclear deterrence.
The situation is additionally noteworthy because India also possesses nuclear weapons, while Israel, according to SIPRI, is classified as a nuclear-armed state, although it does not officially confirm the existence of a nuclear arsenal. Iran is not included in this SIPRI group.
Another indication of the new format’s long-term ambitions is the possibility of its expansion.
Fidan said that other states could join the agreement in the future. Egypt is mentioned first among the potential participants. To implement the treaty, it is planned to establish a permanent secretariat in Saudi Arabia and a mechanism for regular meetings of foreign and defence ministers.
Pakistani Defence Minister Khawaja Asif has already stated that such an association should not become a “closed club,” effectively allowing for the formation of a broader collective security system of Muslim states.
If Egypt and other major states actually begin joining the agreement, it may gradually become not merely a trilateral treaty but a new regional security architecture.
The creation of the new format does not mean that its participants are breaking with Washington. Saudi Arabia maintains extremely close military cooperation with the United States, Türkiye is a member of NATO, and Pakistan has a long history of cooperation with both the United States and China.
However, the new treaty demonstrates another trend: the region’s leading countries are seeking to create their own security guarantees that are not entirely dependent on decisions made in Washington. This is particularly evident against the background of simultaneously rising military expenditure, the crisis surrounding Iran, threats to the Persian Gulf’s energy infrastructure and instability along maritime routes.
The three countries bring together very different resources.
Saudi Arabia provides primarily the financial and economic component. According to SIPRI, its military expenditure reached approximately $83.2 billion in 2025, placing the kingdom eighth among the world’s largest military budgets. The strength of its armed forces and National Guard is estimated at approximately 250,000 personnel. The Saudi army is largely equipped with imported hardware and is closely integrated into the system of military cooperation with the United States and other Western countries.
Türkiye has the largest army by personnel among the three participants when regular armed forces are taken into account — approximately 495,000 military personnel, according to the World Factbook. Its military expenditure amounted to approximately $30 billion in 2025. Türkiye’s main distinguishing features are its large domestic defence industry and NATO membership, which give Ankara substantial institutional and technological resources.
Pakistan has the largest armed forces within the new association, with approximately 660,000 active military personnel. SIPRI estimated its military expenditure in 2025 at approximately $11.9 billion. Financially, Pakistan is significantly behind Saudi Arabia and Türkiye, but compensates for this with the scale of its armed forces and the possession of nuclear weapons.
Together, the three states have approximately 1.4 million active military personnel, while their combined military expenditure, according to 2025 data, exceeds $125 billion. However, the arithmetic addition of these figures does not yet turn the agreement into a unified military organisation. The parties have no joint command modelled on NATO, unified armed forces or publicly defined mechanism for automatically entering a war.
The main question is therefore not the quantity of resources possessed by the three states, but how far they are genuinely prepared to go to protect one another in a real crisis.
According to Maksym Urakin, founder of the Experts Club analytical centre: “The emergence of the Saudi Arabia–Türkiye–Pakistan triangle primarily indicates the formation of a more multipolar security system extending from the Eastern Mediterranean and the Persian Gulf to South Asia. Iran and Israel are the most obvious regional factors behind its emergence, while India is becoming an important indirect factor because of Pakistan’s participation.”
At the same time, the official absence of a designated adversary enables the three countries to strengthen deterrence while maintaining economic relations with states that may potentially perceive the agreement as being directed against them.



