
The article presents key macroeconomic indicators of Ukraine and the global economy as of the end of March 2026. The analysis was prepared on the basis of current data from the State Statistics Service of Ukraine (SSSU), the National Bank of Ukraine (NBU), the International Monetary Fund (IMF), the World Bank, as well as leading national statistical agencies (Eurostat, BEA, NBS, ONS, TurkStat, IBGE). Maksym Urakin, PhD in Economics and founder of the Experts Club information and analytical center, presented an overview of current macroeconomic trends that determined the situation in Ukraine and the world at the beginning of 2026.
Macroeconomic indicators of Ukraine
As of the end of March 2026, the Ukrainian economy remained in a mode of managed macrofinancial stabilization, but the first quarter showed a noticeable deterioration in the balance of risks compared with the beginning of the year. After a relatively favorable January, when inflation was declining, reserves were at a historically high level, and the NBU began cautious easing of interest rate policy, the situation became more complicated in February-March. Inflation accelerated again, international reserves declined for the second month in a row, the foreign exchange market required significant interventions by the regulator, and the first quarterly GDP estimate showed a decline.
According to the preliminary estimate of the State Statistics Service, Ukraine’s real GDP in Q1 2026 decreased by 0.6% compared with Q1 2025, and by 0.7% compared with the previous quarter, taking into account the seasonal factor. Nominal GDP amounted to UAH 2,047.2 billion. This became an important signal that economic recovery remains unstable and highly sensitive to energy, military and foreign trade shocks.
In its April Inflation Report, the National Bank worsened its forecast for Ukraine’s real GDP growth in 2026 to 1.3%, taking into account further destruction of infrastructure, larger electricity deficits and the effects of a significant increase in energy prices. This means that even if international support is maintained and the situation on the foreign exchange market remains controlled, the economy is entering 2026 on a lower growth trajectory than previously expected.
“The first quarter of 2026 showed that the Ukrainian economy has still not moved into a classic recovery phase. We have a stabilization model that works thanks to international financial support, budget expenditures, business adaptation and NBU policy. But the decline in GDP in the first quarter indicates that the margin of safety remains limited. Energy destruction, labor shortages, weak exports and military risks are quickly affecting the real sector. Therefore, the main task for 2026 is to gradually restore the productive base of the economy,” Urakin noted.
Inflation dynamics in March also became less favorable. According to the State Statistics Service, as commented on by the NBU, consumer inflation accelerated to 7.9% year-on-year in March 2026. Month-on-month, prices rose by 1.7%. After the January slowdown to 7.4% and the February acceleration to 7.6%, the March figure confirmed that the disinflationary trend had become less stable.
The NBU explained the March acceleration primarily by the increase in prices for raw food products, fuel and certain services. Additional pressure was created by energy risks, rising business costs, the impact of external energy prices and increasing geopolitical tension. At the same time, core inflation remained closer to the forecast trajectory, which allowed the regulator not to move to a sharp tightening of policy, but at the same time limited the room for a further rapid reduction in the rate.
At the end of March, the NBU key policy rate remained at 15.0%. On March 20, the Board of the National Bank decided to keep it unchanged after the January reduction from 15.5% to 15.0%. The regulator explained this by the need to maintain the attractiveness of hryvnia assets, preserve the stability of the foreign exchange market and control inflation expectations.
“March effectively paused the discussion about rapid monetary policy easing. Inflation accelerated, the foreign exchange market remained tense, and external risks increased. Under such conditions, keeping the rate at 15% was a logical decision. Ukraine cannot afford to stimulate the economy at the cost of losing confidence in the hryvnia. In a wartime economy, the stability of expectations is often more important than a short-term reduction in the cost of credit,” Urakin emphasized.
The foreign exchange sector remained controlled but required significant support from the NBU. As of April 1, 2026, Ukraine’s international reserves amounted to almost $52.0 billion. In March, they decreased by 5.0%. This dynamic was caused by the National Bank’s foreign exchange interventions and the country’s debt payments in foreign currency, which were only partially compensated by inflows from international partners and the placement of foreign currency domestic government bonds.
Despite the decline, reserves remained high by historical standards and continued to serve as the main financial safety cushion. At the same time, the very need for large interventions indicated that the private foreign exchange market continued to have a structural currency deficit. Ukraine imports significantly more than it exports, and therefore exchange rate stability is largely supported by external financing and the NBU’s reserves.
Foreign trade in the first quarter confirmed this problem. According to the State Customs Service, Ukraine’s trade turnover in January-March 2026 amounted to $33.5 billion. Imports reached $23.4 billion, while exports amounted to $10.1 billion. Thus, the goods deficit over three months amounted to about $13.3 billion, and imports were more than twice as high as exports.
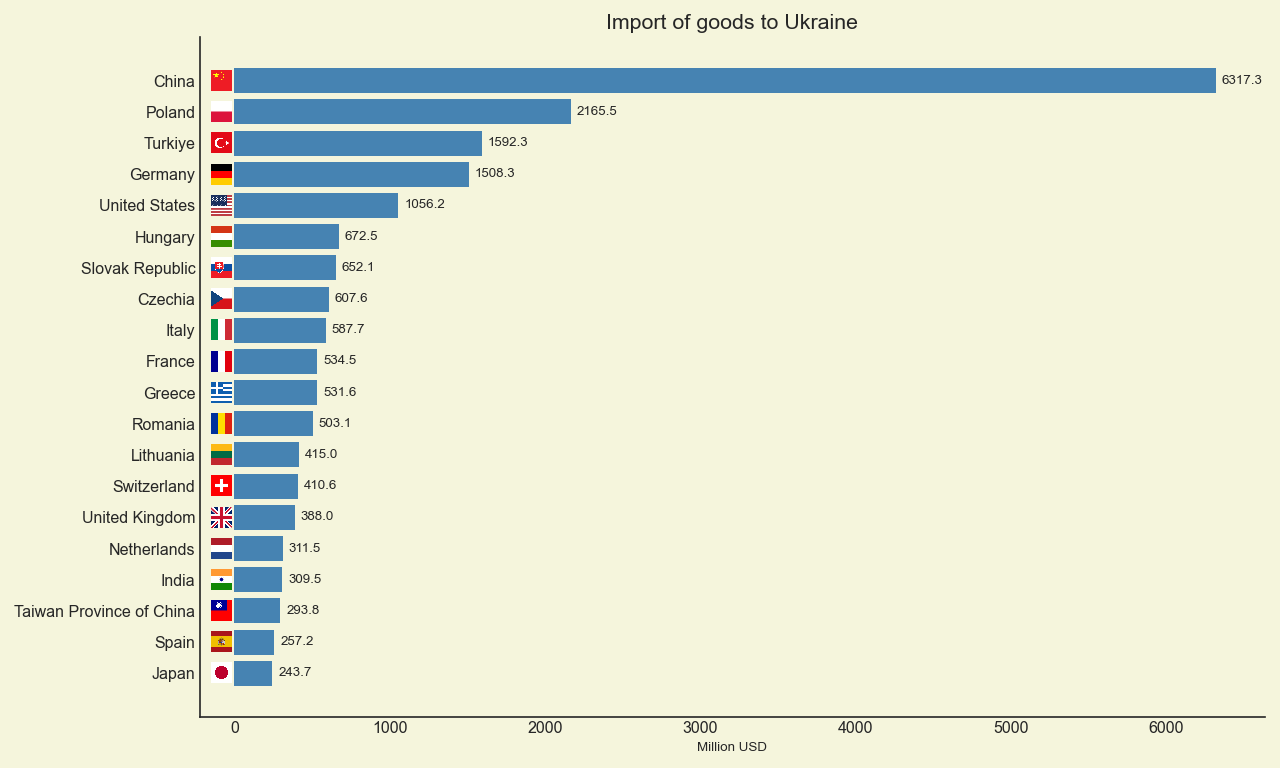
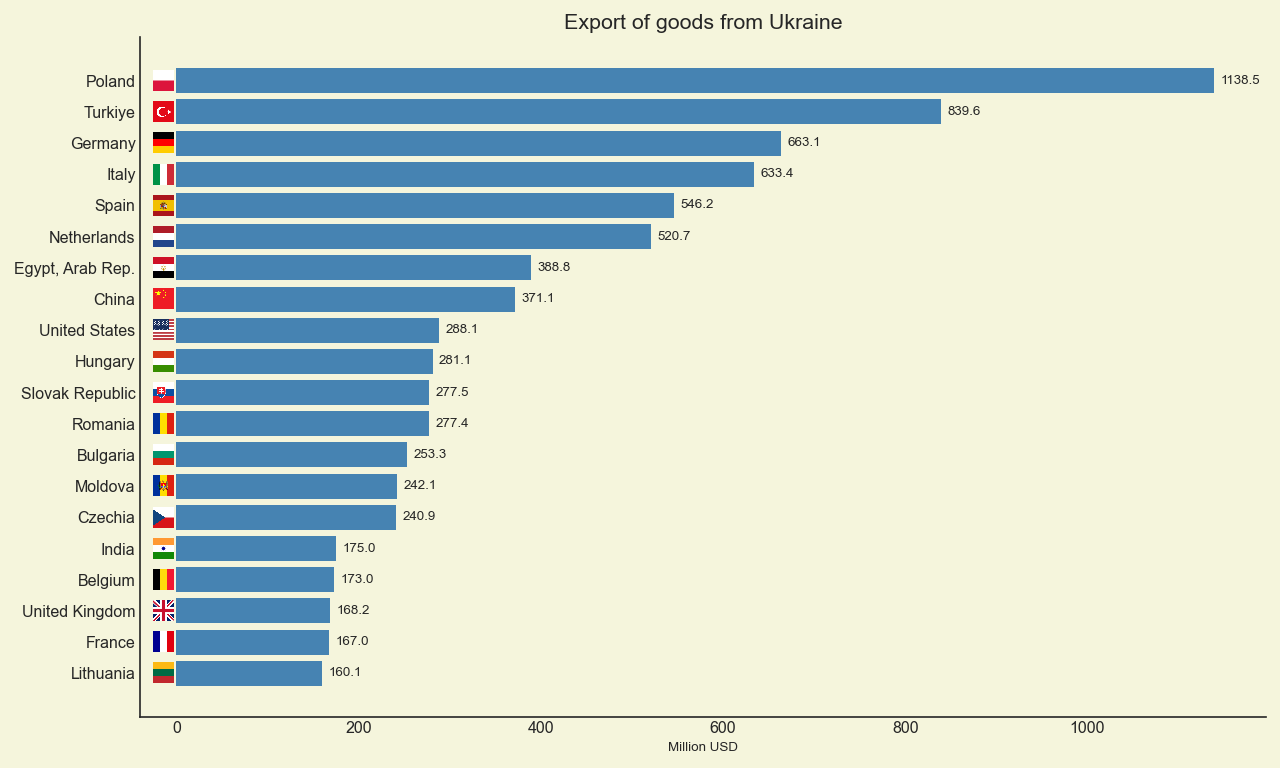
In the import structure, machinery, equipment, transport, fuel and energy goods, and chemical industry products played a key role. China, Poland and Turkey remained the largest import trading partners. The export base remained significantly narrower: the main positions were food products, agricultural products, metals and certain machinery products. The main export destinations remained EU countries and Turkey.
“The trade deficit of the first quarter is one of the most important indicators of the vulnerability of the Ukrainian economy. Reserves and external assistance make it possible to pass through this period without a currency crisis, but they do not replace the country’s own export capacity. When imports are more than twice as high as exports, it means that the country is financing a significant part of its needs through external resources. In wartime conditions this is inevitable, but strategically such a model cannot be permanent. Ukraine must increase exports of products with higher added value, develop processing, logistics, energy autonomy and the defense-industrial complex,” Urakin stressed.
The budget situation following the results of the first quarter also remained tense. According to the Ministry of Finance, UAH 734.6 billion was received by the general fund of the state budget in January-March 2026. At the same time, cash expenditures of the general fund for this period amounted to UAH 916.4 billion, which is 7.1% more than in the corresponding period of the previous year. In March, expenditures amounted to UAH 369.1 billion.
Expenditures on security and defense in January-March amounted to UAH 570.9 billion, or 62.3% of all expenditures of the general fund. This confirms that the state budget in 2026 remains primarily a war budget. The largest areas of expenditure included remuneration in the budget sector with accruals, social security, subsidies and transfers to enterprises, payment for goods and services, servicing of public debt and transfers to local budgets.
“The budget of the first quarter of 2026 shows that the state maintains financial manageability, but the price of this manageability is very high. More than 60% of general fund expenditures are directed to security and defense, and this is absolutely understandable in wartime conditions. But such a structure means that the room for classic investment in development is limited. Therefore, international support, the domestic government bond market and the government’s ability to expand its own tax base through the restoration of economic activity remain critically important,” Urakin noted.
Global economy
As of the end of March 2026, the global economy remained resilient, but less predictable than at the beginning of the year. While in January the IMF’s baseline scenario projected global economic growth of 3.3% in 2026, in the April World Economic Outlook the Fund revised its estimates amid new geopolitical tensions in the Middle East. Under the baseline assumption of a limited conflict, the IMF forecast global growth of 3.1% in 2026 and 3.2% in 2027.
The IMF noted that the global economy had once again faced a shock related to war, rising commodity prices, stronger inflation expectations and tighter financial conditions. This meant that the global environment for Ukraine became less favorable: energy prices, risks to trade and the cost of capital again began to play a greater role.
The United States remained one of the main centers of global resilience. In the first quarter of 2026, U.S. real GDP grew by 2.1% year-on-year, according to the BEA estimate. Growth was supported by investment, exports, government spending and consumer spending. At the same time, inflation in the United States accelerated noticeably in March: the consumer price index rose by 3.3% year-on-year after 2.4% in February, while core CPI stood at 2.6%.
The Federal Reserve in March kept the target range for the federal funds rate at 3.5–3.75%. This meant that U.S. monetary policy remained restrictive, while expectations of a rapid rate cut were postponed. For countries with elevated risk, including Ukraine, this meant the preservation of a relatively high cost of global capital.
The eurozone was in a more difficult position. Its economic growth remained weak, while inflation again rose above the ECB’s target. According to Eurostat’s preliminary estimate, annual inflation in the eurozone in March 2026 stood at 2.5%, while the final estimate later showed 2.6%. In February, the figure was 1.9%, meaning that March brought a noticeable acceleration of price pressure. The main factor was energy, while core inflation remained more moderate.
The European Central Bank in March kept key rates unchanged: the deposit rate at 2.0%, the main refinancing operations rate at 2.15%, and the marginal lending facility rate at 2.40%. For Ukraine, the eurozone remains the most important external economic environment due to trade, financial assistance, EU integration, migration flows and logistics corridors. However, the weak growth rate in Europe limits the potential for a rapid increase in Ukrainian exports.
The United Kingdom also entered 2026 with a combination of moderate growth and an elevated inflation background. In March, the British CPI rose to 3.3% year-on-year after 3.0% in February. The Bank of England kept the Bank Rate at 3.75%, reflecting the regulator’s caution in the face of the risk of a new inflation acceleration. For the European region as a whole, this meant that the cycle of rapid monetary easing had not begun.
“The global economy did not enter a recession in the first quarter of 2026, but it became noticeably more nervous. The United States maintains stable growth, but is facing a new inflation acceleration. The eurozone has a weaker economic impulse and again sees inflation above the target. The United Kingdom also remains in a mode of cautious monetary policy. For Ukraine, this means that the external world does not create a catastrophic background, but also does not provide an easy impulse for recovery. Under such conditions, it is impossible to rely only on external demand,” Urakin noted.
The Chinese economy maintained relatively strong dynamics in the first quarter of 2026. According to the National Bureau of Statistics of China, China’s GDP grew by 5.0% year-on-year in Q1, and by 1.3% quarter-on-quarter. Nominal GDP amounted to about 33.4 trillion yuan. At the same time, inflation remained moderate: CPI rose by 1.0% year-on-year in March, and averaged 0.9% in January-March.
China continued to demonstrate a strong manufacturing base and export potential, but structural problems — weaker domestic demand, the real estate market, debt burden and dependence on external markets — remained important constraints. For Ukraine, China remained a key source of imports, primarily machinery, equipment, electronics and industrial goods.
India retained its status as one of the main drivers of global growth. According to the government’s first advance estimate, India’s real GDP in the 2025/26 fiscal year was expected to grow by 7.4%, while nominal GDP was expected to grow by 8.0%. The main driver remained the services sector, as well as domestic demand and public investment. The Indian economy remained one of the most convincing examples of combining high growth with relatively controlled inflation.
Turkey remained an example of an economy with relatively high business activity, but a very difficult inflationary legacy. According to official TurkStat data, in March 2026 consumer prices rose by 1.94% month-on-month and by 30.87% year-on-year. This was lower than in February, when annual inflation was 31.53%, but still remained an extremely high level. At the same time, the Turkish economy grew by 3.6% in 2025, which indicated the preservation of domestic demand despite inflationary risks.
Brazil looked more balanced among large emerging economies. According to IBGE, Brazil’s GDP in 2025 grew by 2.3%, to 12.7 trillion reais at current prices. Growth was observed in the agricultural sector, industry and the services sector. According to the preliminary IPCA-15 indicator, inflation in March 2026 amounted to 0.44% for the month and 3.90% over the last 12 months. This confirmed that Brazil maintained a relatively controlled inflation background, although its economy also felt the impact of high rates and external uncertainty.
“China, India, Turkey and Brazil show different development models of large emerging economies. China maintains scale and manufacturing strength, but has structural imbalances. India demonstrates the highest dynamics among major economies and relies on domestic demand and the services sector. Turkey is growing, but pays for it with high inflation. Brazil is moving more slowly, but more balanced. For Ukraine, it is important to look at these examples practically: in global competition, those countries win that can simultaneously maintain macro-stability, production, exports and domestic investment demand,” Urakin believes.
Conclusions
As of the end of March 2026, Ukraine maintained macrofinancial manageability, but the first quarter demonstrated the fragility of economic stabilization. Real GDP in Q1 decreased by 0.6% year-on-year, inflation accelerated to 7.9% in March, the key policy rate remained at 15.0%, international reserves declined to about $52.0 billion, and the goods deficit in January-March exceeded $13 billion. The budget remained functional, but its structure was fully subordinated to wartime needs: more than 60% of general fund expenditures were directed to security and defense.
The main risks for Ukraine remained wartime losses, destruction of energy infrastructure, weak exports, labor shortages, high budget dependence on external financing and the structural foreign exchange deficit of the private sector. Positive factors included a significant level of international reserves, the NBU’s controlled policy, continued international support, business adaptability and the state’s ability to fulfill key budget obligations.
The global economy in the first quarter of 2026 remained relatively resilient, but less stable than at the beginning of the year. The IMF forecast global growth of 3.1% in 2026, provided that the conflict in the Middle East remained limited. The United States maintained positive dynamics but faced a new inflationary impulse; the eurozone remained weak in terms of growth rates and again saw inflation above the target; China demonstrated 5% growth; India remained the main driver among large economies; Turkey struggled with high inflation; Brazil maintained moderate, more balanced dynamics.
“March 2026 became a moment for Ukraine to test the real strength of its stabilization model. High reserves, international assistance and the NBU’s controlled policy allow the system to be kept in working condition. But the decline in GDP in the first quarter, accelerating inflation and a large trade deficit show that financial stability alone is not enough. The next stage must be the transition from a survival model to a model of productive recovery. This means investment in energy, the defense-industrial complex, processing, logistics, export production, technologies and human capital. Without this, even significant reserves and external assistance will remain only a safety cushion, not a source of long-term development,” Maksym Urakin concluded.
The monthly analytical and statistical product “Economic Monitoring” is available to clients of Interfax-Ukraine.
Head of the “Economic Monitoring” project, PhD in Economics Maksym Urakin
According to Experts.news, the gap between what buyers most often want to purchase and what sellers are offering is widening in the Ukrainian housing market, as noted in the NBU’s June Financial Stability Report.
According to the regulator, the average size of a purchased apartment remains at 48 square meters, and that of a house at about 70 square meters. At the same time, the supply continues to be dominated by more spacious apartments: their average size exceeds 65 square meters.
The discrepancy is also evident in the age of the properties. Buyers more often choose older and, consequently, more affordable apartments. In Kyiv, the median age of purchased apartments has risen to 33 years, and in the western regions, to 39 years. In real estate listings, by contrast, nearly two-thirds of apartments are offered in buildings constructed less than 15 years ago.
The NBU notes that such discrepancies between supply and demand are holding back market activity. Buyers are more interested in smaller and cheaper housing, while sellers and developers more often offer newer and more spacious properties.
This trend is also significant for developers. In the western regions and the suburbs of Kyiv, budget-friendly projects are more common, while business-class projects predominate in the capital. However, demand during wartime indicates that the average buyer is more often looking for a compact and more affordable option.
In the second half of 2025, residential construction picked up: in most regions, the planned floor area of apartment buildings where construction had begun increased significantly. Across Ukraine as a whole, this figure rose by one and a half times over the year, and in Kyiv—by more than double.
However, the NBU notes that developers continue to finance the completion of existing complexes and new projects largely with their own funds. Banks are reluctant to lend to the construction sector due to high risks.
The main takeaway for the market: further recovery in sales will depend not only on household income but also on how closely supply aligns with actual demand—in terms of square footage, price, age of the property, and level of risk for the buyer.
Ukrainian fintech company Activitis plans to raise $85 million for its WEAGRO, eDilo, and WEAGROBANK digital financial ecosystem development project, in addition to its own $15 million contribution, and estimates the project’s internal rate of return (IRR) at 48.3%.
According to a correspondent for the “Interfax-Ukraine” news agency, the company presented its project at the event “From Recovery to Competitive Advantage: Why Ukraine’s ICT and Telecommunications Sector Is Attractive for Investment,” organized by BDO Ukraine on the sidelines of the Ukraine Recovery Conference (URC 2026) in Gdańsk last week.
It is noted that the project is already in the implementation phase and is included in the list of projects on the investment portal prepared by the Kyiv School of Economics in cooperation with the Ministry of Economy, Ecology, and Agriculture, with support from UK International Development.
According to the presentation, over the next three years, Activitis plans to provide financing to suppliers and buyers using the B2B Buy Now Pay Later (BNPL) model, attract 3,000 active users of its digital banking service for farmers, issue over 10,000 business cards for micro, small, and medium-sized enterprises, and increase the share of cross-border supply chain financing to 20% of its loan portfolio.
The company identifies approximately 1 million micro, small, and medium-sized enterprises in Ukraine as the project’s target audience.
During the presentation, an Activitis representative expressed the belief that the recovery of the Ukrainian economy will largely depend on the availability of rapid financing for small and medium-sized businesses, which traditionally have limited access to credit resources.
“Ukraine’s true recovery will not begin with ten large deals. It will begin with millions of small ones,” he noted.
According to the company representative, its primary target clients are businesses that face difficulties accessing traditional credit due to a lack of sufficient collateral or the complexity of banking procedures; the company aims to streamline the financing decision-making process as much as possible and conduct it online without paper-based documentation.
As previously reported, the WEAGRO platform was launched in March 2024 as an agricultural financing service for farms with land holdings of 50–750 hectares and suppliers of material and technical resources. It enables farmers to purchase seeds, crop protection products, fertilizers, equipment, and other resources with deferred payment, while suppliers receive payment immediately upon closing the deal.
The eDilo service was launched in March 2024 and is positioned as Ukraine’s first B2B “Buy Now Pay Later” (BNPL) service for small and medium-sized businesses. It allows companies to pay for goods and services in installments, while the supplier receives payment immediately upon conclusion of the agreement. The service works with companies across various industries, including retail, construction, healthcare, HoReCa, and manufacturing.
In October 2025, Activitis and Piraeus Bank announced the creation of WEAGROBANK—a digital banking service for farmers that operates on Piraeus Bank’s banking infrastructure.
Activitis was founded in 2013 and specializes in lending and factoring services. The company reports that its loan portfolio totals $115 million, its equity is $28 million, and more than 5,000 businesses have used its services.
According to Experts.new, following a period of relative calm, housing prices in Ukraine have begun to rise again, as stated in the National Bank of Ukraine’s June Financial Stability Report.
According to the NBU, housing prices have risen over the past six months. In the primary market, advertised prices increased roughly in proportion to the hryvnia’s devaluation, as real estate prices in Ukraine are traditionally quoted in U.S. dollars. In the secondary market, the increase was faster—5–10 percentage points higher than the devaluation.
An additional factor was the sharp rise in the cost of construction due to a surge in fuel prices. This intensified upward pressure on prices for new construction and limited developers’ ability to keep prices at previous levels.
At the same time, the NBU notes that housing prices remain historically low relative to household incomes. In the first quarter of 2026, the housing price-to-income ratio stood at 8.7x for the primary market and 8.6x for the secondary market.
The situation is different in the rental market. Due to winter attacks on energy infrastructure and the associated risks, the growth in rental rates has slowed. In Kyiv, the south, and the center of the country, rental costs have remained virtually unchanged since last fall. Price increases continued mainly in the western regions.
The price-to-rent ratio for secondary housing rose slightly in the first quarter to 10.4x, but still did not exceed the long-term average.
For buyers, this means that housing remains relatively affordable by historical standards, but uncertainty, security concerns, and the state of the energy infrastructure continue to limit demand. For investors, the situation is less clear-cut: rising purchase prices coupled with nearly stable rents reduce the short-term appeal of buying housing for rental purposes, especially in Kyiv and the central regions.
In the medium term, market dynamics will depend on the hryvnia exchange rate, the cost of construction, security, the state of the energy sector, and the resumption of mortgage lending.
HOUSING, NBU, PRICE, REAL ESTATE, rent
According to Fixygen, shareholders of PJSC “Zhytomyrmoloko” will hold an extraordinary general meeting on July 3, 2026, at which they will consider the sale of 100% of the corporate rights of State Enterprise “Novograd-Volynskyi Cheese Plant” to LLC “Favorit Company.”
The agenda also includes a proposal to increase the subsidiary’s authorized capital by 80.1 million UAH prior to the sale by offsetting the debt owed by “Novograd-Volynskyi Cheese Plant” to “KOMO Ukraine” LLC. The cheese plant’s authorized capital may be increased from 0.23 million UAH to 80.37 million UAH.
Shareholders will also consider the issue of the free-of-charge transfer of “Zhytomyrmoloko” real estate to the cheese plant, specifically production buildings with a total area of 22.6 thousand square meters and wastewater treatment facilities in the village of Natalivka, Zhytomyr Oblast.
PJSC “Zhytomyrmoloko” is part of the “KOMO” group of companies. According to the NSSMC’s disclosure system, 94.9755% of the company’s shares are owned by the Cypriot company WMG West Milk Limited.
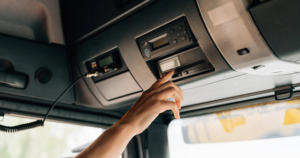
In Ukraine, a requirement takes effect on July 1 stipulating that all freight vehicles registered for the first time for international transport must be equipped with second-generation smart tachographs (G2v2).
According to a statement from the Ministry of Community and Territorial Development, this requirement is part of Ukraine’s obligations under the Agreement on the Liberalization of Freight Transport with the EU.
“We are consistently harmonizing our legislation with EU standards so that Ukrainian companies can operate under the same rules as their European counterparts,” Deputy Minister of Community and Territorial Development Serhiy Derkach is quoted as saying in the press release.
The ministry explained that second-generation smart tachographs will automatically record drivers’ work and rest periods, as well as determine the vehicle’s location.
However, the ministry emphasized that this requirement applies only to trucks that are registered in Ukraine for the first time on or after July 1, 2026, for the purpose of international transport.
It is noted that there are currently over 100 centers operating in Ukraine that issue and service cards for smart tachographs. As a result, more than 29,000 such cards have already been issued.
Training is also underway for inspectors of the State Service of Ukraine for Transport Safety on how to use the new devices, which will enable them to effectively inspect both Ukrainian and foreign vehicles, the press release added.
EU, Ministry of Development, tachograph, TRANSPORTATION, TRUCK



