
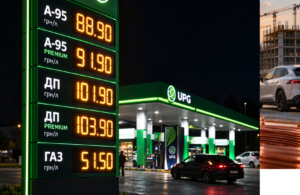
Prices for both types of diesel fuel, as well as autogas, continue to rise, according to monitoring of a number of filling station chains conducted since February 2026 by the Energoreforma internet portal.
According to the monitoring data, as of October 20, compared with October 16, the price of diesel fuel and diesel fuel+ increased by UAH 1–3 per liter, while autogas rose in price by UAH 1.6–3.5 per liter. At the same time, the price of regular diesel at state-owned UKRNAFTA reached UAH 99.9 per liter.
Gasoline prices have remained largely stable for several weeks.
Fuel prices (average) as of 10:00 a.m. on October 20 compared with October 16 (based on Energoreforma’s monitoring of filling station chains’ websites and applications)
| Chain | 95 (UAH/l) | Premium 95 (UAH/l) | Diesel fuel (UAH/l) | Premium diesel fuel (UAH/l) | Gas (UAH/l) |
|---|---|---|---|---|---|
| UKRNAFTA | 88.90 (88.90) | 91.90 (91.90) | 99.90 (98.90) | 101.90 (100.90) | 49.90 (47.90) |
| UPG | 88.90 (88.90) | 91.90 (91.90) | 101.90 (99.90) | 103.90 (101.90) | 51.50 (49.90) |
| OKKO | 92.90 (92.90) | 95.90 (95.90) | 104.90 (101.90) | 107.90 (104.90) | 51.90 (49.90) |
| WOG | 92.90 (92.90) | 95.90 (95.90) | 104.50 (102.50) | 107.50 (105.50) | 52.50 (50.50) |
| SOCAR | 94.90 (94.90) | 97.90 (97.90) | 105.00 (105.00) | 108.00 (106.00) | 54.40 (50.90) |
As reported, on September 21, SOCAR was the first filling station chain to “release” the price of diesel fuel, raising it to UAH 103 per liter and UAH 104 per liter for regular diesel and diesel+, respectively.
On September 25, WOG and OKKO raised the price of premium diesel above UAH 100 per liter, from UAH 99.9 per liter to UAH 102.9 per liter, while the price of regular diesel fuel remained at UAH 99.9 per liter.
Dmytro Leushkin, founder and CEO of Prime Group, explained at the time that diesel fuel prices should already have exceeded UAH 100 per liter several days earlier, but there was an unofficial request from the government to restrain them.
On October 15, a number of filling station chains exceeded the UAH 100 per liter mark for regular diesel fuel, whose price had long been kept at UAH 99.9 per liter. A distinctive feature of that day was that the state-owned UKRNAFTA chain, which serves as a kind of “price restraint mechanism,” set the price of diesel fuel+ at UAH 100.9 per liter.
At the same time, autogas became more expensive again at almost all the chains monitored, increasing by between UAH 0.6 and UAH 2 per liter.
Several days earlier, Serhiy Kuyun, director of the A-95 consulting group, had forecast that autogas prices would rise by approximately 10% over the following 7–10 days due to an increase in global prices.
At that time, he also drew attention to the rise in diesel fuel quotations on London’s ICE exchange to $1,483 per tonne (an increase of more than $100 per tonne), noting that such a jump had dashed hopes of stabilizing prices for this type of fuel.
Kuyun also emphasized that retail prices for regular diesel at filling station chains were lower than wholesale prices, which, in particular, stood at UAH 101 per liter in the central part of the country. According to him, at such wholesale prices, the price at the pump should be at least UAH 105–106 per liter. At the same time, he pointed out that there was no fuel shortage in Ukraine.
autogas, DIESEL FUEL, FILLING STATIONS, FUEL, FUEL PRICES, UKRAINE
In January–September 2026, Poland increased its diesel fuel shipments to Ukraine by 44% compared to the same period last year—to over 2 million metric tons, according to data from the A-95 Consulting Group and its analysis by the Experts Club think tank.
In September, 202,600 metric tons of diesel fuel were supplied from Poland, which is virtually the same as the September 2025 level of 202,000 metric tons.
Romania remained the second-largest supplier in September, with 156,700 metric tons, compared to 158,600 metric tons a year earlier. Supplies from Lithuania increased by 7% to 65.9 thousand metric tons.
At the same time, imports from Southern Europe fell significantly. Supplies from Greece dropped by 70% to 40.8 thousand metric tons, and from Turkey by 88% to 6.1 thousand metric tons.
Overall, the volume of imports from southern Europe in September fell by 38%—to 220,000 metric tons—and its share of total imports decreased from 52% to 41%.
“Due to the war in Iran, southern European supplies are significantly more expensive this year than northern ones, and this is the main reason for the decline in volumes,” notes “A-95”.
Over the first nine months, diesel fuel imports from Lithuania rose by 33%—to over 560,000 metric tons. At the same time, shipments from Hungary fell by 49%—to 266,000 metric tons.
According to Serhiy Kuyun, director of the “A-95” Consulting Group, this shift in the geography of supplies indicates the Ukrainian fuel market’s continued adaptation to changes in price conditions and logistical risks.
The “A-95” Consulting Group conducts research on the motor fuel market, monitors prices and logistics, and analyzes the supply of resources to the Ukrainian market.
In September 2026, Ukrnafta became the largest importer of diesel fuel to Ukraine for the first time, supplying 105.3 thousand metric tons of the fuel, according to data from the A-95 Consulting Group and its analysis by the Experts Club.
The company’s import volume was 3.3 times higher than in September of last year.
OKKO took second place among the largest importers with 57,500 metric tons, while UPG came in third with 47,000 metric tons.
The top five also included AT Energo Trade with 44,000 metric tons and WOG with 42,500 metric tons.
Next came ZPEK with 29,400 metric tons, “Paid” with 28,900 metric tons, D.Trading with 26,500 metric tons, “Martin Trade” with 18,100 metric tons, and “Gaztrim” with 12,000 metric tons.
Among the largest players, the ZPEK Group showed the most significant growth compared to last year. Over the first nine months of 2026, its imports rose by 228% and approached 250,000 metric tons.
Total diesel fuel imports into Ukraine in September amounted to 537,000 metric tons, which is 21% less than a year earlier.
According to Serhiy Kuyun, director of the A-95 Consulting Group, changes among the largest importers are occurring against the backdrop of logistics transformation, high volatility in global prices, and the need for companies to establish more stable supply channels.
“The fuel market continues to face unprecedented challenges caused by Russian attacks. Importers are actively developing new logistics channels and expanding their vehicle fleets,” notes “A-95”.
The A-95 consulting group has been researching the Ukrainian motor fuel market for over two decades and monitors prices, supplies, and market infrastructure.
The Polish oil refining group ORLEN S.A. supplied 1.3 million metric tons of diesel fuel to Ukraine from January through September 2026, which is 33% more than during the same period in 2025, according to data from the A-95 Consulting Group.
Compared to the first nine months of 2024, shipments increased by 68%.
ORLEN remains the largest corporate supplier of diesel fuel to the Ukrainian market.
In September, the company shipped a total of approximately 110,000 metric tons of diesel fuel from refineries in Poland and Lithuania. This is 30% less than in September of last year.
The decline in monthly shipments occurred against the backdrop of an overall reduction in Ukrainian diesel fuel imports. In September, the volume of imports amounted to 537,000 metric tons, which is 21% less than a year earlier.
At the same time, Poland retained its status as the largest supplier of diesel fuel to Ukraine. Over the first nine months, shipments from Poland rose by 44% and exceeded 2 million metric tons.
According to Serhiy Kuyun, director of the “A-95” Consulting Group, the role of the northern route in supplying the Ukrainian market has strengthened due to the higher cost of shipments from Southern Europe.
“A-95” notes that due to the significant rise in the price of Southern European supplies, Ukrainian companies are increasingly turning to supplies from Poland and Lithuania.
The “A-95” Consulting Group specializes in research and monitoring of the Ukrainian petroleum products market. The company’s director is Serhiy Kuyun.
In September 2026, Ukraine imported 537,000 metric tons of diesel fuel, which is 21% less than in the same month of 2025 and 9% lower than in August, according to data from the A-95 Consulting Group.
Since the beginning of the year, diesel fuel imports have reached 4.7 million metric tons, which is 3% higher than the January–September figure from last year.
The main feature of September was unusually weak demand. A-95 attributes this, in particular, to massive attacks on industrial enterprises, as well as to problems with the export of agricultural products from the new harvest, including disruptions in maritime logistics.
“We do not yet have precise data, but there are all signs that retail sales of diesel fuel have also declined due to record prices caused by unprecedented global market rates,” note analysts at “A-95”.
The decline in demand is also confirmed by supply trends in the third quarter. During this period, approximately 1.7 million metric tons of diesel fuel were imported into Ukraine, which is about 10% less than a year earlier.
According to Serhiy Kuyun, director of the A-95 Consulting Group, the Ukrainian fuel market continues to operate amid unprecedented logistical and pricing challenges related to the war.
“The fuel market continues to face unprecedented difficulties caused by Russian attacks. Importers are actively developing new logistics channels and expanding their fleets, particularly of gasoline tankers,” the company notes.
The “A-95” consulting group specializes in research on the Ukrainian petroleum products market, price monitoring, logistics, and resource supply for the fuel market. Its director is Serhiy Kuyun.
Ukrainian gas station chains are not yet fully passing on the increased costs resulting from Russian attacks to consumers, instead offsetting them by reducing their own profitability; however, the ability to keep prices in check in this way is limited, according to Serhiy Kuyun, director of the A-95 Consulting Group.
As the expert reported on his Facebook page, “A-95” specialists compared retail prices for gasoline and diesel fuel with their customs value over the past three years.
The resulting difference includes gas stations’ logistics and operating costs, as well as operators’ profits. According to “A-95” calculations, in 2026 this markup did not increase but actually decreased slightly compared to the previous year, despite a significant rise in fuel companies’ expenses.
Among the additional costs, Kuyun cites the restoration of damaged gas stations and the strengthening of their security. According to him, installing an anti-drone protective structure over a single gas station can cost about €100,000, while building a temporary shelter can cost 1–1.2 million UAH.
At the same time, personnel costs are rising. According to data from the State Tax Service cited by the expert, the official salaries of employees at the 40 largest gas station chains have increased by 20% over the past year. Additional expenses arise from the need to organize work schedules and staff rotations in frontline regions.
“In other words, the stability of the markup was achieved by reducing profits,” Kuyun noted.
According to his assessment, the most difficult economic situation has developed in the left-bank region of Ukraine. The cost of delivering fuel there is higher than in the western and southern border regions, while there is virtually no significant regional variation in retail prices.
National chains can partially offset the low profitability of such gas stations through more efficient stations in other regions. For small local operators in the east of the country, this option is often unavailable.
According to Kuyun, some local gas stations are currently operating with zero or negative profitability. The expert attributes this to why some gas stations damaged by Russian drones are not being rebuilt: investments in repairs may not pay off given the current economic situation.
A further negative factor is the decline in fuel sales. Kuyun attributes this both to the impact of attacks on Ukrainian industry and the resulting drop in consumption, as well as to the high cost of petroleum products on the global market.
According to the expert, for now, fuel retailers are effectively absorbing part of the rising costs using their own revenues, rather than passing them on entirely to the final price of gasoline and diesel fuel.
However, this situation cannot last indefinitely.
“It’s hard to say how much longer fuel retailers will be able to absorb these price increases using their own revenues. I think it won’t be long,” Kuyun noted.
Thus, future price trends at Ukrainian gas stations will depend not only on global oil and petroleum product prices and the exchange rate, but also on operators’ ability to offset rising costs related to logistics, security, infrastructure restoration, and personnel.
Source: Serhiy Kuyun — Facebook post.



