
According to Interfax-Ukraine, Ukraine’s economy showed the first signs of emerging from a recession in the first half of 2026, however, the high foreign trade deficit, inflationary pressures, and the dependence of public finances on international aid remain key macroeconomic risks, according to the latest issue of “Economic Monitoring.”
As noted by Maksym Urakin, Ph.D. in Economics and founder of the Experts Club information and analytical center, after real GDP fell by 0.6% year-over-year in the first quarter, the economy returned to growth in April–June.
In the second quarter, Ukraine’s real GDP increased by 0.4% compared with the same period last year and by 0.3% compared with the previous quarter. At the same time, the National Bank’s forecast projected growth of the Ukrainian economy at only 1.3% for the full year of 2026.
“Positive factors in the first half of the year included the resumption of at least minimal GDP growth, the return of international reserves to above $50 billion, stability in the foreign exchange market, more consistent international financing, and the adaptability of Ukrainian businesses. The main risks remain the war, the state of the energy sector, high production costs, a labor shortage, weak commodity exports, and a growing trade imbalance. Ukraine has a significant supply of external liquidity, but it cannot replace domestic economic growth,” Urakin noted.
Consumer inflation slowed to 7.2% in June, while core inflation accelerated to 8.1%. The NBU’s discount rate remained at 15%.
At the same time, after four months of decline, Ukraine’s international reserves increased by 12.1% in June—to $51.27 billion. The NBU’s foreign exchange interventions remained substantial.
Foreign trade remains one of the main structural risks to the Ukrainian economy. From January through June 2026, merchandise imports totaled approximately $49.3 billion, while exports amounted to about $21 billion. Thus, the merchandise trade deficit reached approximately $28.3 billion.
Public finances also remain under significant strain. Revenues to the General Fund of the state budget for the first half of the year totaled nearly 1.9 trillion UAH, while expenditures amounted to approximately 2.23 trillion UAH.
Approximately 1.4 trillion UAH, or about 63% of all General Fund expenditures, was allocated to the security and defense sector. The volume of international grants totaled 569.6 billion hryvnia.
According to Urakin, one of the main objectives of economic policy should be to transform significant imports of equipment, international funding, and defense spending into a foundation for creating new domestic production capacity.
“The next phase of economic policy should consist not only of maintaining financial stability, but also of transforming imported equipment, international funds, and defense spending into new production assets. The foundation for long-term development should be energy self-sufficiency, the defense-industrial complex, agricultural processing, machine building, production localization, logistics, digital technologies, and exports of high-value-added products,” says the founder of Experts Club.
At the same time, the first half of the year revealed significant differences between the world’s largest economies and emerging markets.
The Chinese economy grew by 4.7% in the first six months of 2026, while India posted a growth rate of about 7.8% in April–June.
Turkey continued to combine economic growth with extremely high inflation. In the second quarter, its GDP increased by 2.3% year-over-year and by 1.1% compared to the previous quarter, while annual inflation in June remained near 32%.
Brazil showed more moderate growth: its GDP in the second quarter increased by 2% year-over-year and by 0.5% compared to the previous quarter. In the first half of the year, the country’s economy grew by 1.9%, and annual inflation in June slowed to 4.64%.
“Key emerging economies ended the first half of the year with very different growth patterns. China grew by 4.7%, but its second quarter was weaker than the first, and domestic consumption lags significantly behind industrial output and exports. India continues to grow by nearly 8%, driven by the size of its domestic market and investment. Turkey remains an example of how inflation exceeding 30% limits the quality of economic growth, while Brazil is showing more moderate growth with gradual control of inflation. For Ukraine, the main conclusion remains the same: long-term growth requires its own industrial, technological, and export base,” Urakin emphasized.
In his assessment, the first half of the year confirmed the viability of Ukraine’s macrofinancial stabilization model, but at the same time revealed its limitations.
“The return of GDP to modest growth and the replenishment of reserves are positive signs; however, the $28.3 billion merchandise trade deficit, high underlying inflationary pressures, and the budget’s dependence on external financing reveal the limits of this model. Only by developing its own production and export base will Ukraine be able to transition from an economy of wartime stabilization to a model of sustainable postwar growth,” concluded Maksym Urakin.
“Economic Monitoring” is a monthly analytical and statistical publication led by Maksym Urakin, Ph.D. in Economics. The publication analyzes the main macroeconomic indicators of Ukraine and the world’s leading economies, as well as trends in GDP, inflation, public finances, international reserves, foreign trade, and key risks to economic development.
Ukraine and Honduras have signed a “roadmap” for deepening bilateral cooperation for 2026–2029, Ukrainian Foreign Minister Andriy Sibiga announced.
“The signing of a ‘roadmap’ to deepen cooperation between Ukraine and Honduras for 2026–2029 was an important step in strengthening our relations,” he wrote on social media platform X.
Sibiga reported that he had met with Honduran Foreign Minister Mirey Agüero de Corrales following her visit to Kyiv as part of the Honduran president’s delegation.
According to him, the parties agreed on the importance of expanding economic and business ties.
Sibiga thanked Agüero de Corrales for her attention to Ukraine and noted that her visit to Kyiv allowed her to see the consequences of the Russian war firsthand and strengthen mutual understanding between the two countries.
He specifically emphasized Honduras’s position on the illegal activities of the “shadow fleet,” particularly the need to end the practice of registering ships under the Honduran flag.
The parties also discussed the need to restore freedom of navigation in the Black Sea, the protection of Ukrainian ports, global food security, and the unimpeded export of Ukrainian agricultural products.
Sibiga briefed his counterpart on efforts to establish an International Commission for the Settlement of Claims and other international initiatives aimed at ensuring accountability and justice.
The ministers also discussed cooperation on the return to Ukraine of children abducted and deported by Russia, as well as practical steps to intensify these efforts.
According to Sibiga, Ukraine counts on Honduras’ continued support in its efforts to achieve a comprehensive and lasting peace.
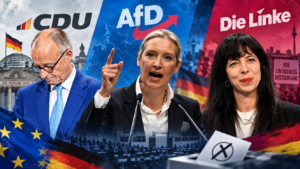
Regional elections in Germany on September 20 demonstrated the weakening positions of traditional parties and the further fragmentation of the German electorate: Alternative for Germany (AfD) won in Mecklenburg-Vorpommern, while in Berlin the Left took first place, according to an analysis by the Experts Club analytical center.
In Mecklenburg-Vorpommern, AfD received 38.2% of the vote, compared with 16.7% in the previous elections in 2021. The Social Democratic Party of Germany received 35.5%, the Left — 6.5%, and the Greens — 5.7%. Chancellor Friedrich Merz’s Christian Democratic Union received 4.9% and, for the first time in history, failed to cross the five-percent threshold in a state election.
The CDU received 13.3% in the previous election in this state, meaning it lost more than 8 percentage points of support. According to the preliminary distribution of seats, AfD receives 32 seats, the SPD — 29, while the Left and the Greens receive five each. Since the other parliamentary forces rule out a coalition with AfD, the voting result alone does not determine the composition of the future state government.
In Berlin, the results demonstrated a different political configuration. The Left received 25.7% of the vote, compared with 12.2% in the previous election. The CDU came second with 18.8%, AfD received 16.3%, the Greens — 14.3%, and the SPD — 12.1%. The incumbent coalition of the CDU and the Social Democrats lost its parliamentary majority.
Experts Club points out that the September 20 results continued a trend that emerged at the beginning of the month. On September 6, AfD took first place in the election in Saxony-Anhalt with 43.8%, while the CDU received 17.2%. In 2021, the CDU had 37.1% in this state, while AfD had 20.8%.
Thus, according to Experts Club, the results of the September elections should not be reduced exclusively to a movement of the German electorate in a single ideological direction. In two eastern states, AfD received the greatest support, while in Berlin the Left strengthened significantly. This indicates that some voters of traditional parties are shifting toward different alternative political forces depending on the region and the structure of local problems.
According to Infratest dimap, in Mecklenburg-Vorpommern AfD managed to mobilize around 66,000 citizens who had previously not voted, as well as attract around 48,000 former SPD voters and approximately 32,000 former CDU supporters.
At the same time, the SPD’s result in this state is largely associated with the personal support enjoyed by Minister-President Manuela Schwesig. Almost half of Social Democratic voters surveyed after the election said that they would not have supported the party without her. This demonstrates the importance of the personal ratings of state-level politicians even when their parties have weaker positions at the federal level.
A separate problem for the CDU was voters’ perception of the party’s economic competence. Only 13% of respondents in Mecklenburg-Vorpommern named the CDU as the political force best able to solve economic problems. Some 89% of respondents also agreed with the statement that before the federal election the party had promised a great deal but delivered little. These results characterize one specific federal state and cannot automatically be applied to Germany as a whole.
In Berlin, one of the central factors of the campaign was the housing issue. The Left focused attention on rental costs, the shortage of affordable housing and regulation of the activities of large property owners. At the same time, migration and security remained among the important issues for AfD voters.
“These elections show not a linear movement of German society in one ideological direction, but a fragmentation of the electorate. In Mecklenburg-Vorpommern, protest is concentrated around AfD, while in Berlin the Left became the main recipient of the protest vote and the vote of young urban residents. In other words, the common denominator is not ideology, but the declining ability of traditional parties to keep different groups of voters within the former model of the political center,” said sociologist and co-founder of the research company Active Group Oleksandr Poznii.
According to him, the mobilization of citizens who had not previously participated in elections is particularly illustrative. This may indicate not only a redistribution of the already established electorate, but also an expansion of the base of individual political forces.
Poznii also drew attention to the decline in confidence among some voters in the CDU’s traditional economic competence. In his view, for centrist parties the coming months will be associated primarily with the need to restore the confidence of different groups of voters, rather than only with personnel discussions.
Federal dynamics also demonstrate changes in party support. In the September ARD-DeutschlandTrend conducted by Infratest dimap from August 31 to September 2 among 1,319 voters, AfD was supported by 27% of respondents, the CDU/CSU by 21%, the Greens by 15%, the SPD by 13%, and the Left by 12%.
At the same time, state elections do not directly change the composition of Germany’s federal government or Berlin’s foreign policy. However, they influence the domestic political debate on the economy, budget spending, energy, migration and other issues.
The preliminary results of the elections in Mecklenburg-Vorpommern and Berlin were released on the night of September 21. The final results are to be approved after the electoral records are checked.
The material was prepared on the basis of a study by the Experts Club analytical center, “AfD won in Mecklenburg, the Left in Berlin: regional elections increased pressure on Germany’s traditional parties,” published on September 21, 2026. Experts Club study on Experts.news
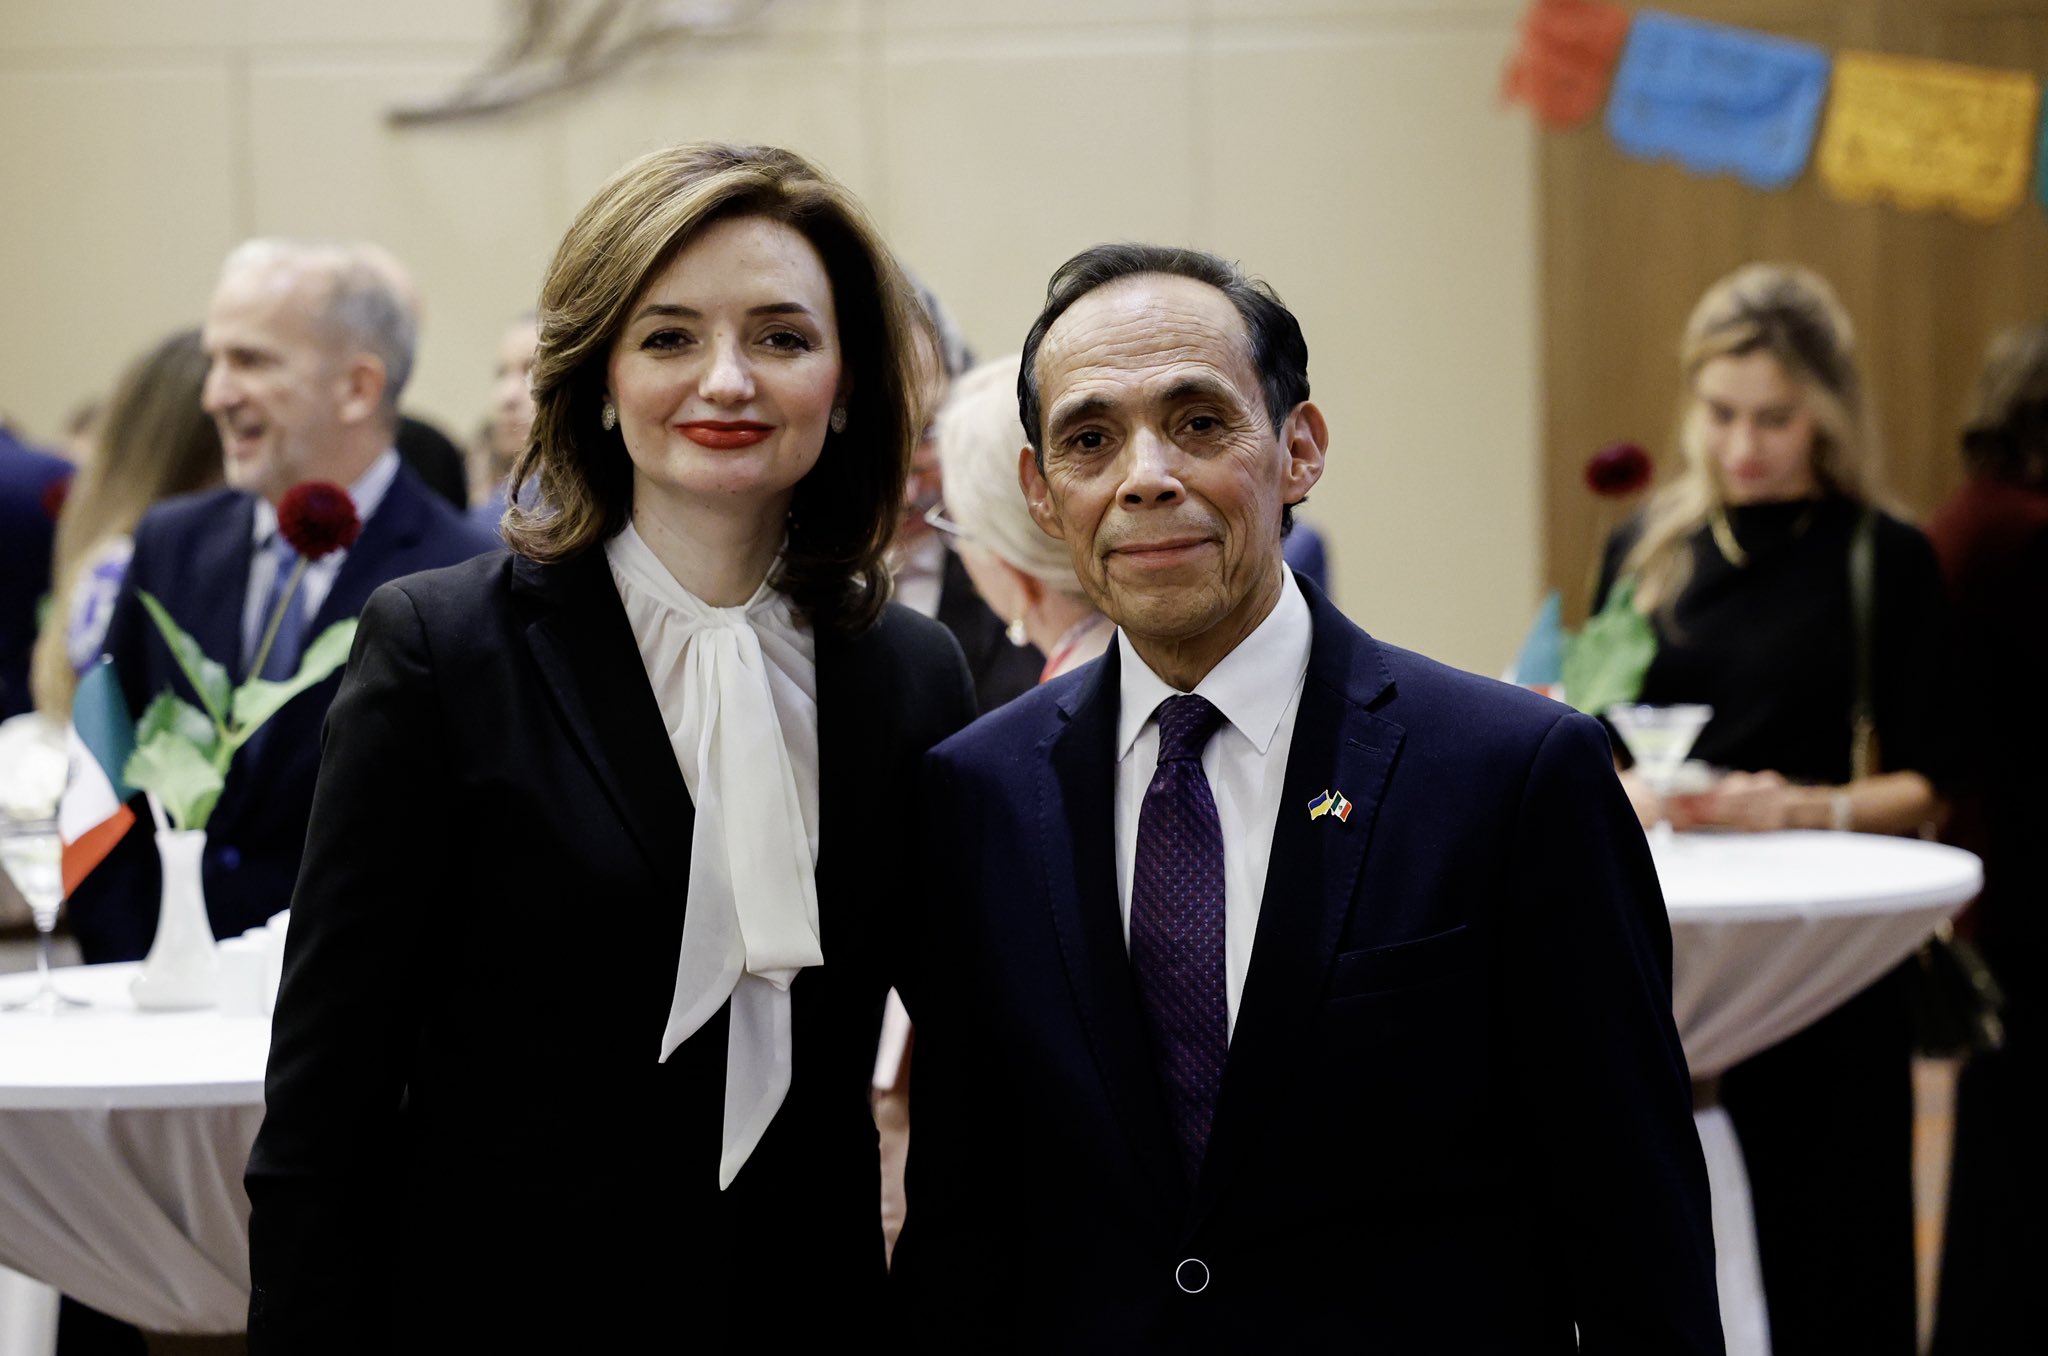
Mexico and Ukraine have significant potential for further expanding bilateral relations in the political, economic, scientific, and academic spheres, said Audencio Contreras González, Mexico’s Ambassador Extraordinary and Plenipotentiary to Ukraine.
“I am convinced that Mexico and Ukraine have significant potential for further strengthening bilateral relations. Our countries deserve broader, deeper, and more dynamic relations—ranging from open political dialogue based on mutual respect to mutually beneficial scientific, academic, and economic cooperation,” the ambassador said at a diplomatic reception in Kyiv marking the 216th anniversary of the start of Mexico’s struggle for independence.
The event was attended by Ukraine’s Deputy Minister of Foreign Affairs Mariana Betsa, as well as representatives of government agencies, the diplomatic corps, academic and business circles, civil society, and the Mexican community.
Contreras González noted that celebrating Mexico’s national holiday in Ukraine holds special significance.
“We celebrate it together with a people whom we sincerely admire and who, under extremely difficult circumstances, deeply value their identity, their sovereignty, and their right to independently determine their own future as an independent state living in peace, just as the Mexican people do,” the diplomat emphasized.
According to him, Mexico’s foreign policy is based on the constitutional principles of non-interference, the peaceful settlement of disputes, and the rejection of the use of force in international relations.
“It is precisely these principles that define our clear position on condemning the invasion of Ukraine, upholding international law, and promoting dialogue to achieve a just and lasting peace,” the ambassador stated.
He also emphasized the importance of cultural diplomacy and closer ties between the societies of the two countries, despite the significant geographical distance.
“Strengthening bilateral relations begins with our societies—which are geographically distant but share common values and traits, as well as a centuries-old history of statehood—getting to know one another better,” noted Contreras González.
During the reception, guests were introduced to elements of Mexican culture and national traditions, including music, cuisine, and the traditional decorative art of papel picado.
The ambassador expressed hope for the swiftest possible establishment of a just and lasting peace in Ukraine and the further strengthening of Ukrainian-Mexican cooperation.
Mexico recognized Ukraine’s independence on December 25, 1991, and diplomatic relations between the two countries were established on January 14, 1992.
The Embassy of Ukraine in Mexico City was opened in January 1999. Mexico initially maintained diplomatic relations with Ukraine through its embassies in Russia and later in Poland; in 2000, an honorary consulate began operating in Kyiv. The Permanent Embassy of Mexico in Ukraine began operations on May 1, 2005, and its official inauguration took place on June 20, 2005, during a state visit by Mexican President Vicente Fox.
Audencio Contreras González heads the Mexican Embassy in Ukraine and presented his credentials to the President of Ukraine on August 16, 2024.
Ukraine’s international reserves amounted to $48.7 billion at the end of August 2026, which is approximately $8.6 billion, or 15%, less than at the beginning of the year, according to an analysis by the Experts Club information and analytical center.
As of January 1, reserves stood at a record level of $57.3 billion, and by the beginning of February they had risen to $57.7 billion. After that, they declined for four consecutive months: to $54.8 billion as of March 1, $52 billion as of April 1, $48.2 billion as of May 1, and $45.7 billion as of June 1.
The main factors behind the decline were significant foreign exchange interventions by the National Bank, government debt payments, and uneven inflows of international financial assistance.
The situation changed sharply in June, when Ukraine received large tranches of external financing. Reserves increased by 12.1% over the month — to $51.27 billion. About $11.3 billion was credited to the government’s foreign currency accounts, including $6.82 billion from the EU and almost $4.5 billion through the World Bank.
In July, reserves remained almost unchanged, but in August they again decreased by approximately $2.5 billion, or 5%, to $48.7 billion.
In August, the NBU sold about $4.82 billion on the foreign exchange market, while $927.3 million was credited to the government’s foreign currency accounts. Ukraine also directed $721.8 million toward servicing and repaying government debt in foreign currency and paid $258.2 million to the IMF.
Net international reserves declined even more sharply over the month — by 6.9%, to $33.8 billion.
At the same time, the current level of reserves remains approximately 5.8% higher than a year ago, when they stood at about $46 billion as of September 1, 2025.
Experts Club founder and economist Maksym Urakin previously emphasized that the absolute size of reserves should not be regarded as a guarantee of currency security.
“Reserves at the level of $51.2 billion remain a significant foreign exchange buffer, but the absolute figure itself should not create an impression of complete protection. The sustainability of reserves depends on the regularity of international financing, the volume of NBU interventions, debt payments, and the economy’s ability to increase export revenues,” Urakin noted.
According to the NBU, the current level of reserves remains sufficient and provides financing for approximately four months of future imports.
Private landlords in the U.K. are increasingly selling properties or planning to exit the market amid rising financing costs and tax and regulatory burdens. The decline in supply is already leading to further increases in rent and is occurring at a time when the country is experiencing a change in government and a period of heightened economic uncertainty.
According to official data from the UK’s Office for National Statistics (ONS), in July 2026, the average private rent reached £1,393 per month, up 3.7% year-over-year. In England, the figure stood at £1,451, and in London, it was £2,317 per month.
A study by the Lomond agency network paints a similar picture, showing that British renters are already spending an average of 32.7% of their annual income on housing. According to the company’s methodology, the average rent was £1,369 per month, 4.3% higher than a year earlier. The discrepancy with ONS data is due to different sample sizes and calculation methods.
At the same time, supply from landlords is shrinking. A July survey by the Royal Institution of Chartered Surveyors (RICS) showed that new listings from landlords stood at -27%. Market participants report that landlords are reducing their portfolios or exiting the sector entirely. Despite more subdued demand from tenants, the balance of expectations for further rent increases rose to +28%.
A survey of more than 2,000 landlords conducted by Property118 in the second quarter paints an even bleaker picture: 40.2% had already reduced their portfolios over the previous two years, while only 6% had expanded them. Looking ahead to the next three years, 67.7% of respondents expect to sell at least part of their real estate holdings, while 27.1% intend to exit the market entirely.
One of the main reasons remains the high cost of borrowing. The Bank of England’s base rate stands at 3.75%, significantly higher than the levels seen during the era of cheap money prior to 2022. More than a third of the landlords surveyed will need to refinance their mortgages within the next year, which for many means switching from old, cheap fixed rates to significantly more expensive terms.
An additional factor has been the most significant reform of the private rental market in many years. As of May 1, 2026, the main provisions of the Renters’ Rights Act came into effect in England: Section 21 evictions without cause have been abolished, fixed-term leases are being replaced by a system of periodic tenancies, and landlords’ responsibilities have been strengthened. Starting in late 2026, the government will begin implementing a mandatory private rental housing registry, for which registration will incur a fee. Additional quality standards and a mandatory ombudsman will be introduced in the future.
That said, it would be incorrect to attribute the mass plans to sell properties solely to the new law. Pressure on the sector has been building for years due to tax changes, restrictions on mortgage interest deductions, and rising costs for insurance, repairs, and property maintenance. The new rules have merely become yet another factor forcing owners to reevaluate the economics of buy-to-let.
The situation in the housing market is unfolding against a backdrop of serious political instability in the United Kingdom. Keir Starmer stepped down as prime minister in the summer of 2026 after losing support within the Labour Party, and in September he decided to leave Parliament as well. He was succeeded by Andy Burnham, who became the UK’s seventh prime minister in a decade.
The new administration must simultaneously address the cost of living, the funding of social programs, and pressure on public finances. Yields on long-term British government bonds rose to approximately 5.26% in early September—a high not seen since 2008—which increases borrowing costs not only for the government but also, indirectly, for the entire economy. Investors are awaiting the new cabinet’s October budget and trying to understand how Burnham intends to finance his social and infrastructure initiatives.
It is still premature to speak of a full-blown economic crisis or recession in the UK. GDP grew by 0.4% in the second quarter of 2026, following 0.6% growth in the first quarter, though the pace of growth is slowing. Inflation accelerated again in July to 2.9%, unemployment reached 4.9%, and British businesses remain cautious about new investments.
It is precisely this combination of weak economic growth, high interest rates, and political uncertainty that is exacerbating problems in the rental market. The new cabinet aims to strengthen tenant protections, but as private landlords withdraw from the market, the opposite effect occurs: the fewer apartments available on the market, the greater the pressure on rent.
This presents a complex dilemma for the British government. If regulations and taxes continue to erode returns on private rentals faster than the government and institutional investors can build new housing, some of the costs of tenant protections may effectively be passed back to tenants in the form of higher rents and fewer housing options.
In the medium term, this could accelerate a structural shift in the British market: small private landlords will gradually be replaced by professional build-to-rent operators, pension funds, and investment funds capable of operating with lower returns and withstanding significantly stricter regulation.
Thus, the exit of British landlords is not an isolated real estate issue, but part of a broader picture: expensive capital, an economic slowdown, a crisis of political stability, and, at the same time, the government’s attempt to significantly tighten regulation of the housing market. For tenants, the main risk is not the mass disappearance of rental housing per se, but rather its continued rise in price and the shift in ownership from small landlords to large institutional investors.



