
As of July 1, 2026, the number of pensioners in Ukraine stood at 9,976,600, a decrease of 190,500 since the beginning of the year, according to Opendatabot, citing data from the Pension Fund of Ukraine.
In the second quarter alone, the number of pension recipients decreased by 74,400 people. The total decline for the first half of the year has already exceeded the figure for all of 2025.
The average monthly pension payment as of early July was 7,272.68 UAH. At the same time, the actual amount of payments varies significantly depending on the region, length of insurance coverage, earnings, and type of pension.
The Pension Fund’s data does not cover the temporarily occupied territories, where Ukrainian authorities are unable to maintain a complete registry of benefit recipients.
Ukraine, pensioner, pension, demographics: The number of pensioners in Ukraine has fallen below 10 million
As of July 1, 2026, the number of pensioners in Ukraine stood at 9,976,600, a decrease of 190,500 since the beginning of the year, according to Opendatabot, citing data from the Pension Fund of Ukraine.
In the second quarter alone, the number of pension recipients decreased by 74,400 people. The total decline for the first half of the year has already exceeded the figure for all of 2025.
The average monthly pension payment as of early July was 7,272.68 UAH. At the same time, the actual amount of payments varies significantly depending on the region, length of service, earnings, and type of pension.
The Pension Fund’s data does not cover temporarily occupied territories, where Ukrainian authorities are unable to maintain a complete record of benefit recipients.
According to data from the Pension Fund of Ukraine as of July 1, 2026, approximately 2.4 million Ukrainian pensioners—or 24% of the total number—receive between 3,001 and 4,000 UAH per month.
The average payment within this group is 3,581.58 UAH. Another 335,800 people, or 3.4% of pensioners, receive no more than 3,000 UAH, while 1.72 million people receive between 4,000 and 5,000 UAH.
At the same time, approximately 3.21 million people—or nearly one-third of all pensioners—receive a pension of more than 7,000 UAH. Payments exceeding 20,000 UAH are made to 436,200 people, including 29,500 pensioners who receive more than 30,000 UAH per month.
The average pension nationwide is 7,272.68 UAH; however, it exceeds the amount received by most recipients due to significantly higher pensions for certain categories.
The population in Ukraine’s government-controlled territories currently stands at 29 million people, according to Ella Libanova, director of the Mykhailo Ptukha Institute of Demography and Quality of Life Research at the National Academy of Sciences of Ukraine.
In an episode of the Open Reality special project, she reported that this joint estimate by the State Statistics Service (SSS) and the Institute of Demography—made without a census—is based on data from mobile operators and government registries. “As of today, this is the joint estimate by the SSS and our Institute—29 million. I always say that it’s plus or minus about 300,000,” Libanova noted.
Since no population census has been conducted in Ukraine since 2001, the researchers used data from three mobile operators as a basis, supplementing it with other sources.
“We used this database as our foundation and supplemented it with various available sources of information for verification and refinement: the labor market; data from the Pension Fund, aggregated with data from tax authorities, which includes not only pensioners; data from the Migration Service and the Ministry of Justice from the demographic registry; we also used the ‘school registry’ and EHealth,” the expert explained.
Libanova acknowledged that this method is not ideal, but there is currently no alternative to it.
She also noted that, according to Eurostat, approximately 4.3 million Ukrainians currently reside in European Union countries.
At the same time, according to Libanova, there is no reliable data on the number of Ukrainians who have left for Russia since the start of the full-scale war. She also noted that a policy of demographic replacement is being carried out in the territories temporarily occupied by Russia: the Ukrainian population is being displaced and replaced by people from other regions of Russia, which, in her opinion, is a continuation of the practice of population assimilation.
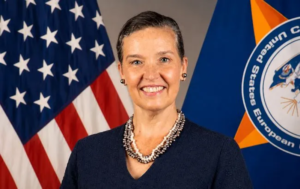
Sandra Oudkirk, who has more than 30 years of experience in the diplomatic service, has become the new U.S. chargé d’affaires in Ukraine.
This was reported on the website of the U.S. Embassy in Ukraine.
Sandra Oudkirk is a career diplomat and a member of the U.S. Senior Foreign Service who has represented the interests of the United States in various countries around the world for more than 30 years, holding positions with a steadily expanding range of authority and responsibility.
Since 2024, she has worked at the U.S. Department of Defense, where she initially served as deputy director of the George C. Marshall European Center for Security Studies and later became the civilian deputy and foreign policy adviser to the United States European Command. From 2021 to 2024, Sandra Oudkirk headed the American Institute in Taiwan.
While working in Washington, Oudkirk held positions in the Bureau of East Asian and Pacific Affairs, the Bureau of Energy Resources, and the Bureau of Economic and Business Affairs. She dealt with issues of strategic competition among major powers, energy security, countering threat financing, and imposing economic sanctions. She previously also worked as a senior watch officer at the U.S. Department of State Operations Center.
Abroad, she served in Taipei, Dublin, Ankara, Kingston, Istanbul, and Beijing.
Sandra Oudkirk was born and raised in Tampa, Florida. She graduated from Georgetown University’s School of Foreign Service. She is married to diplomat Scott Oudkirk and has three adult children. She speaks Chinese (Mandarin) and Turkish.
As reported, Julie Davis had served as U.S. chargé d’affaires in Ukraine since May 2025.
Davis’s predecessor, former U.S. Ambassador Bridget Brink, left the ambassadorial post in April 2025. She later openly stated that she had decided to resign because of the foreign policy of President Donald Trump’s administration.
In Ukraine, 1.1 million pieces of jewelry made of precious metals received the state hallmark during the first quarter of 2026, OpenDataBot reported on July 17, citing data from the Ministry of Finance of Ukraine.
The average monthly number of hallmarked jewelry items was 18% lower than in 2025. Last year, 5.4 million items passed state hallmarking inspections, which was 26% less than in 2024.
The largest decline in 2025 was in the hallmarking of silver items—down 32%. The number of gold jewelry items that passed inspection decreased by 20%.
After the outbreak of full-scale war, the market contracted sharply, but in 2023–2024 it rebounded to levels above pre-war levels. In 2023, 6.4 million pieces of jewelry received the state hallmark, and in 2024 a record was set at 7.3 million items.
The state hallmark certifies that a piece of jewelry meets the declared fineness of the precious metal. Ukrainian law prohibits the sale of jewelry without such a hallmark.
Gold jewelry surpassed silver for the first time in terms of the number of hallmarks in Ukraine
In 2025, gold jewelry surpassed silver for the first time in terms of the number of items passing state hallmarking inspections, according to data from the Ministry of Finance of Ukraine published by “OpenDataBot” on July 17.
In the first quarter of 2026, the share of gold jewelry among all hallmarked items rose to 57%, while silver accounted for 43%. By comparison, in 2020, silver jewelry accounted for 72% of the market, and gold for only 28%.
In total, since 2020, 20.8 million silver items and 15 million gold items have undergone state hallmarking. Thus, in the cumulative six-year statistics, silver still holds first place with a 58% share.
The shift in market structure is partly due to the rising price of silver and growing industrial demand for the metal. Silver is widely used in the production of solar panels, electric vehicles, electronics, and semiconductors, leading jewelry companies to compete increasingly with the industrial sector for raw materials.
Ukraine’s total trade turnover with its 50 largest trading partners in January–June 2026 amounted to approximately $66.97 billion, according to calculations by the Experts Club information and analytical centre based on foreign trade in goods data. Imports from the countries included in the top 50 reached $47.35 billion, while Ukrainian exports amounted to $19.62 billion. The trade deficit stood at $27.73 billion. Thus, imports accounted for approximately 70.7% of trade turnover with Ukraine’s main partners, while exports accounted for only 29.3%. The export-to-import coverage ratio was 41.4%, meaning that for every dollar of Ukrainian goods sold abroad, there were approximately $2.41 worth of imports.
These indicators do not characterise Ukraine’s entire foreign trade, but rather its most concentrated segment—transactions with its 50 leading partners. At the same time, it is precisely this group that determines the main geographical and structural trends in Ukraine’s trade in goods. The ratio between imports and exports indicates that the economy continues to generate significant demand for foreign industrial, technological and consumer products, while the ability of Ukrainian manufacturers to offset these purchases with export revenues remains limited. This model is partly explained by wartime needs, the reconstruction of damaged infrastructure and imports of energy equipment, vehicles, machinery, electronics and components. However, the scale of the gap also points to insufficient export diversification and a high dependence on several traditional commodity groups.
“The concentration of more than half of trade turnover in five countries makes foreign trade sensitive to changes in market conditions, logistics and trade policies in individual markets. Dependence on Chinese imports remains particularly noticeable: China accounts for more than one-fifth of turnover with the TOP 50 partners, but the share of Ukrainian exports in this direction is comparatively small,” emphasised Maksym Urakin, founder of the Experts Club information and analytical centre.
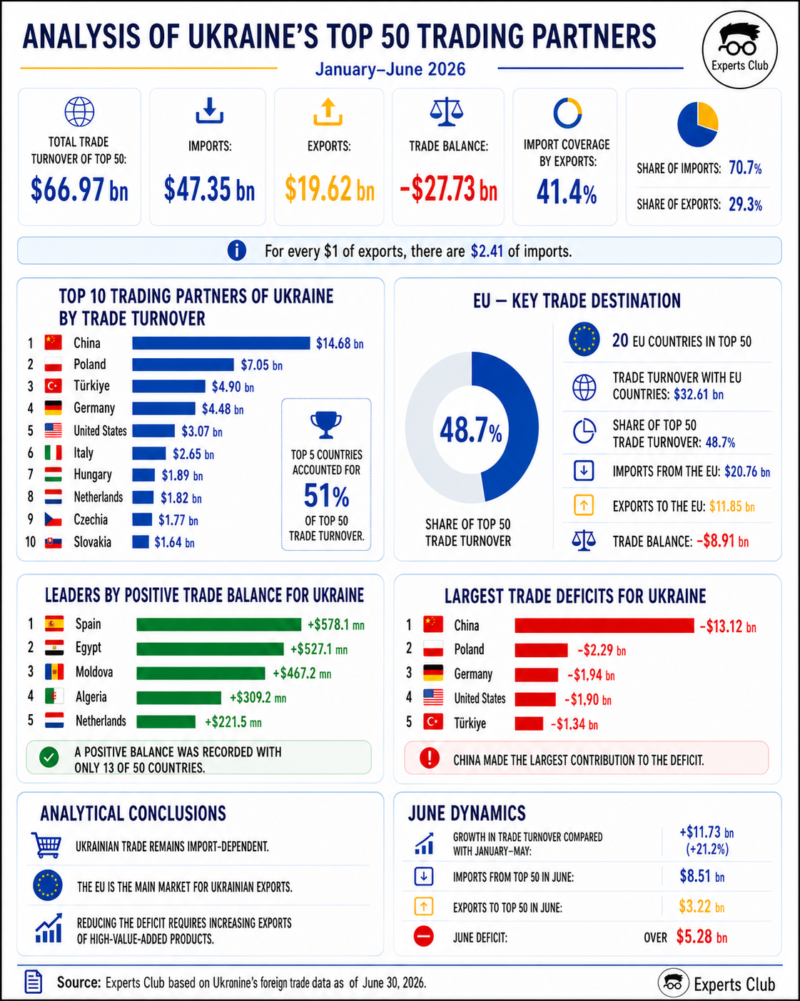
Compared with the results for January–May, cumulative trade turnover with the TOP 50 partners increased by $11.73 billion, or 21.2%. In June alone, imports from this group of countries amounted to approximately $8.51 billion, while exports reached $3.22 billion. Thus, in just one month, the trade deficit increased by a further $5.28 billion. Imports grew somewhat faster than exports in June: after the addition of the monthly data, their cumulative volume increased by 21.9%, while exports rose by 19.7%. This means that the expansion of foreign trade turnover occurred mainly due to purchases of goods abroad rather than a proportional strengthening of the positions of Ukrainian suppliers in foreign markets.
China retained its status as Ukraine’s largest trading partner by a significant margin. In the first half of the year, trade turnover with China reached $14.68 billion, of which $13.9 billion accounted for imports of Chinese goods and only $778.4 million for Ukrainian exports. The deficit amounted to $13.12 billion. China accounted for 21.9% of Ukraine’s total turnover with the TOP 50 partners and 29.4% of imports from this group of countries. At the same time, trade with China generated approximately 47.3% of Ukraine’s total trade deficit with the top 50. This imbalance demonstrates that China is primarily a source of goods, equipment and components for Ukraine, while Ukraine’s export presence in the Chinese market remains comparatively weak.
Poland ranked second with trade turnover of $7.05 billion. Ukraine imported $4.67 billion worth of Polish products and exported $2.38 billion worth, resulting in a deficit of $2.29 billion. Despite the negative balance, trade with Poland is more balanced than trade with China, while Poland has also become the largest individual market for Ukrainian exports. Türkiye ranked third with turnover of $4.9 billion, purchasing $1.78 billion worth of Ukrainian goods and supplying Ukraine with products worth $3.12 billion. Germany ranked fourth with $4.48 billion, while the United States ranked fifth with $3.07 billion. Total trade turnover with these five countries amounted to $34.18 billion, or 51% of turnover with the TOP 50. They accounted for 57.8% of imports but only 34.6% of Ukrainian exports, once again highlighting the concentration of purchases among several major suppliers.
“More than half of Ukraine’s trade turnover with its main partners is accounted for by just five countries, and this concentration is much more pronounced in imports than in exports. Trade with China is the most illustrative example: it accounts for almost one-third of imports from the TOP 50 but less than 4% of Ukrainian exports to this group of countries. This structure creates a long-term need not simply to reduce imports, but to develop domestic production and create new competitive export offerings,” emphasised Maksym Urakin, founder of the Experts Club information and analytical centre.
Italy, which ranked sixth, had one of the most balanced indicators among Ukraine’s leading partners. With trade turnover of $2.65 billion, imports from Italy amounted to $1.37 billion, while Ukrainian exports reached $1.28 billion, meaning that the deficit did not exceed $91.1 million. Hungary followed with turnover of $1.89 billion, the Netherlands with $1.82 billion, the Czech Republic with $1.77 billion and Slovakia with $1.64 billion. Together, the top 10 accounted for $43.95 billion, or 65.6% of trade turnover with the TOP 50. The top 20 partners accounted for $55.81 billion, or 83.3%. Therefore, the remaining 30 countries in the ranking accounted for less than 17% of turnover, indicating a fairly narrow geographical base for Ukraine’s main trade flows.
A significant role of European Union member states remains an important feature of the ranking. The TOP 50 included 20 EU countries, with total trade turnover amounting to approximately $32.61 billion, or 48.7% of the total figure for the top 50. Imports from these countries reached $20.76 billion, while Ukrainian exports amounted to $11.85 billion. Thus, the European Union accounted for almost 44% of Ukraine’s imports and more than 60% of its exports within the TOP 50. This means that the EU remains the main market for Ukrainian goods and, at the same time, a key source of industrial and consumer products. The trade deficit with the EU countries included in the ranking amounted to approximately $8.91 billion, although the imbalance in this area was significantly smaller than in trade with China.
Geographically, trade with Europe performs several functions for Ukraine simultaneously. Poland, Germany, Italy, the Netherlands and Spain are major sales markets; Central European countries provide transit and production cooperation; while Western European countries remain important suppliers of technology, equipment, vehicles, pharmaceuticals and chemical products. At the same time, the persistence of substantial deficits with Poland, Germany, France, the Czech Republic, Hungary, Lithuania and Greece indicates that even within the trade area most closely integrated with Ukraine, import demand is still growing faster than the ability of Ukrainian companies to increase supplies.
Poland became the largest market for Ukrainian exports, with a figure of $2.38 billion. Türkiye ranked second, receiving goods worth $1.78 billion. It was followed by Italy with $1.28 billion, Germany with $1.27 billion, Spain with $1.09 billion and the Netherlands with $1.02 billion. Unlike imports, where China had an almost threefold advantage over Poland, Ukrainian exports were distributed more evenly among the leading markets. This reduces dependence on a single buyer, but at the same time indicates the absence of a large foreign market capable of providing Ukrainian producers with sales volumes comparable to the scale of Chinese supplies to Ukraine.
Ukraine recorded a trade surplus with only 13 of its 50 largest partners, while imports exceeded exports in relations with 37 countries. The largest surplus was generated in trade with Spain, amounting to $578.1 million. High positive figures were also recorded with Egypt at $527.1 million, Moldova at $467.2 million, Algeria at $309.2 million, the Netherlands at $221.5 million and Lebanon at $220.5 million. The surplus in trade with Libya amounted to $181.3 million and with Tunisia to $155.1 million. This geography demonstrates the importance to Ukrainian exports not only of the EU but also of the markets of North Africa, the Middle East and neighbouring Moldova, where Ukrainian goods in a number of cases hold stronger positions than imported products from the respective countries.
At the same time, the list of the largest deficits demonstrates a different model of trade dependence. In addition to China, a significant negative balance was recorded with Poland at $2.29 billion, Germany at $1.94 billion, the United States at $1.9 billion and Türkiye at $1.34 billion. The five largest partners accounted for more than 74% of the total trade deficit with the TOP 50. A notable negative balance was also recorded with Greece, the Czech Republic, Hungary, France, Lithuania, Sweden, Taiwan, Vietnam and Japan. Part of this deficit is associated with purchases of products that are either not manufactured in Ukraine or are produced in insufficient quantities, but its continued accumulation creates additional demand for foreign currency and increases the economy’s dependence on external financing.
A comparison with the results for January–May shows that the composition of the TOP 50 did not change in June: the same countries were included in the ranking, although their positions within the list were noticeably redistributed. Indonesia demonstrated the largest rise, moving from 43rd to 34th place. Its trade turnover increased by almost $145 million in June and reached $320.6 million in the first half of the year. The main factor behind the rise was Ukrainian exports, which increased by approximately $107.7 million in June alone. This made it possible to almost balance bilateral trade: imports amounted to $166.8 million and exports to $153.8 million.
Canada rose from 47th to 40th place, increasing its trade turnover to $220.1 million, while Saudi Arabia moved from 27th to 23rd place with a figure of $649.8 million. Saudi Arabia’s rise was mainly driven by increased supplies to Ukraine: imports from the country rose by approximately $133.2 million in June, while Ukrainian exports increased by $41.5 million. By contrast, Jordan fell from 41st to 47th place, Switzerland from 22nd to 27th, Tunisia from 37th to 41st and Libya from 39th to 42nd. Such movements do not necessarily indicate an absolute decline in trade: in most cases, they reflect the fact that turnover with other countries grew faster.
Serbia retained 33rd place among Ukraine’s trading partners. In the first half of the year, trade turnover between the countries reached $345.9 million, of which $243.2 million accounted for imports of Serbian products and $102.7 million for Ukrainian exports. Bilateral turnover amounted to approximately $55.8 million in June. Ukraine’s negative balance for the six-month period reached $140.5 million, but Serbia’s retention of its position in the middle of the fourth group of ten countries in the ranking indicates that it has already become a notable, although still unbalanced, trading partner of Ukraine in the Balkans.
“The trade deficit cannot be assessed exclusively as a negative indicator, since part of the imports supports the restoration of production, energy facilities and infrastructure. However, a situation in which exports cover only about 41% of imports requires a systematic response. Ukraine needs to increase not only the physical volume of supplies but also the share of high-value-added products, develop processing, mechanical engineering, the food industry and technology exports. Without this, growth in trade turnover will continue to be accompanied by an accelerated accumulation of the deficit,” Maksym Urakin noted.
Overall, the results of the first half of the year indicate that Ukraine’s foreign trade remains geographically concentrated, import-dependent and uneven across individual directions. China dominates as the largest supplier and the main source of the deficit; the European Union remains the primary market for Ukrainian exports; while Türkiye, Egypt, Moldova, the Balkan countries, North Africa and the Middle East form an important additional belt of trade relations. The rise of Indonesia, Canada and Saudi Arabia demonstrates that the structure of Ukraine’s partners can change rapidly even within a single month, particularly in the case of large consignments of raw materials, industrial goods or food products.
Further improvement of the trade balance will depend on Ukraine’s ability to address several tasks simultaneously: maintaining access to traditional European markets, expanding its presence in Asian, African and Middle Eastern countries, restoring production capacity and increasing the share of processed products in exports. Simply reducing imports during reconstruction could hinder economic recovery, so the key objective should not be administrative restrictions on purchases but the accelerated growth of competitive exports. It is the transition from a predominantly raw-material-based model to broader manufacturing specialisation that can gradually reduce the trade deficit and make foreign trade more resilient to price, logistical and geopolitical risks.



