Industrial production in Germany fell 1.1% in July compared to the previous month, according to the country’s statistics office. This marks the sharpest decline since August of last year.
Analysts had expected an average increase of 0.3%, according to Trading Economics.
According to revised data, the figure remained unchanged in June, whereas it had previously been reported to have risen by 0.2%.
Output of consumer goods fell by 2.2% in July, capital goods by 3.4%, and intermediate goods by 0.2%.
Output in the automotive industry fell by 9.2%. Energy production increased by 4.7%, and construction output rose by 0.9%.
On a year-over-year basis, industrial production in Germany fell by 1.6% the month before last, following a 0.5% decline in June.
Ferrexpo, a mining and ore processing company with its main assets in Ukraine, announced the resumption of production at its facilities in Ukraine.
“We are pleased to resume production in Ukraine, and I would like to thank our team, which has once again demonstrated its dedication and determination by ensuring the resumption of operations over the weekend,” said Ferrexpo’s interim CEO, Lucio Genovese.
According to a press release, following the raising of $100 million, which was announced on September 4, 2026, the company took the necessary steps over the weekend, and production was resumed using one pellet production line.
Given the numerous documented incidents of attacks on ports and ships in the Black Sea, the company plans to focus on exporting products to customers in Europe, according to a Ferrexpo stock exchange announcement on Monday.
As reported in early August, Ferrexpo suspended production in Ukraine amid the constant threat of Russian attacks in and around Ukrainian ports in order to preserve working capital.
As of June 30, 2026, the group’s net cash position (excluding lease obligations) stood at approximately $21 million, compared to $25 million as of March 31, 2026, and $47 million as of December 31, 2025.
Ferrexpo owns a 100% stake in Yeristovsky GOK LLC, a 99.9% stake in Bilanovsky GOK LLC, and 100% of the shares in Poltava GOK PJSC.
The London Stock Exchange (LSE) suspended trading in Ferrexpo shares in May due to the company’s inability to publish its annual financial statements on time.
Issue No. 2 – May 2026
Analysis of the Current Situation in Ukraine’s Foreign Exchange Market
Throughout May, the hryvnia exchange rate slowly trended downward, but the hryvnia depreciated so gradually that a relatively stable equilibrium effectively formed in the market. Demand did not increase significantly, and in the interbank market, the NBU continues to act as the key market maker, supplying currency through interventions.
Despite the absence of panic and frenzied demand for foreign currency, the hryvnia is reaching new highs—the exchange rate has crossed the 44.2 UAH/USD threshold. There are signs that a reversal is unlikely in the near future. To meet the state budget’s needs, the government must convert financial aid and loan tranches received from partners and donors—denominated in euros and dollars—into hryvnia, which automatically contributes to the hryvnia’s weakening. The strengthening of the dollar on the global market has also worked against the hryvnia: investors are seeking opportunities to invest specifically in dollar-denominated assets, particularly U.S. Treasury bonds, which bolsters confidence in the U.S. currency; its exchange rate is strengthening despite negative foreign policy developments related to the absence of a peace agreement between Washington and Tehran. The hryvnia’s future exchange rate trajectory depends on the level of domestic demand for foreign currency, the state of the NBU’s international reserves, the Ministry of Finance’s need for new issues of government bonds, and fluctuations in the dollar’s exchange rate against the euro on the global market, as well as global oil price trends.
Global Context
The Federal Reserve, which decided at its April meeting to keep the benchmark interest rate unchanged, now faces a dilemma regarding how to curb the surge in inflation. According to Neil Kashkari, president of the Federal Reserve Bank of Minneapolis, reducing inflation in the U.S. remains the top priority, as inflation continues to exceed the Federal Reserve’s 2% target. However, he emphasized that the U.S. central bank will continue to take a “balanced approach” to its dual mandate of price stability and full employment. In effect, this implies a possible decision by the Fed to raise rates as early as its June meeting.
The war in Iran remains the main factor affecting the U.S. economy. The parties have yet to engage in substantive negotiations. In late May, the U.S. launched new strikes against Iran. In response, Iran attacked a U.S. airbase in Kuwait. U.S. President Donald Trump stated that the country could strike Oman due to its attempts to establish control over the Strait of Hormuz in conjunction with Iran. Trump is demanding complete freedom of navigation through the strait and is threatening a large-scale attack on Oman.
Geopolitical tensions in the Middle East are reflected in fluctuations in oil prices. In late May, the price of Brent crude rose by more than 2%—to approximately $95 per barrel—while the price of WTI crude also rose by more than 2%—to $91 per barrel. The price increase came after the U.S. carried out new attacks on Iran, targeting a military facility in Bandar Abbas, a strategically important port city.
Meanwhile, the U.S. dollar has been steadily strengthening against the euro in May. While the dollar traded at 1.1779 per euro at the beginning of the month, it stood at 1.1636 per euro by the end of May. As of the end of May, the DXY index shows a 0.72% increase in the U.S. dollar’s exchange rate over the past month. The dollar is being supported by yields on U.S. Treasury bonds, which remain fairly high, as well as investors’ hopes for a resolution to the conflict in the Middle East.
Domestic Ukrainian Context
In May, the Ukrainian foreign exchange market saw a moderate decline in demand for foreign currency. Average weekly foreign currency sales on the interbank market in April totaled $817 million, while the average weekly figure for the first three weeks of May was $745 million. In April, the NBU sold $4.08 billion through interventions; in the first three weeks of May, it sold $2.23 billion. The hryvnia exchange rate has been gradually depreciating since early May; however, while it stabilized at 43.96 UAH per dollar in the first half of May, it began to fall more rapidly in the last ten days of the month, and as of May 29, the NBU’s official exchange rate stood at 44.26 UAH/USD. The cash market in Ukraine was also affected by weakening demand in May; official data on sales, purchases, and the cash market balance are expected to be released in early June, but preliminary indications suggest there will be no surprises—the trend is likely to show an increase in currency sales rather than purchases.
Throughout May, the hryvnia was supported by positive sentiment regarding future inflows of funds from partners, as well as by the decline in oil prices on the international market. The European Commission recently announced that the EU plans to transfer 9.1 billion euros in financial aid to Ukraine in June.
Thus, 5.9 billion euros will be allocated to Ukraine’s defense needs, and 3.2 billion euros will go toward budget support. This constitutes the first tranche under the European Union’s loan program totaling 90 billion euros. Another inflow of funds is planned for June—2.8 billion euros under the Ukraine Facility mechanism. However, there are still doubts regarding the IMF loan program and the arrival of funds from the Fund in June.
On May 27, an International Monetary Fund mission began its work in Kyiv. It is tasked with assessing Ukraine’s compliance with the requirements for the disbursement of the next tranche. Earlier, it was reported that tax policy—particularly the taxation of electronic platforms—is the key issue in agreeing on the program’s milestones. Tax Bill No. 12360 was submitted to parliament and even reached the voting stage. However, on May 26, the Verkhovna Rada did not support key amendments to the bill, which would have eliminated tax exemptions on international parcels up to 150 euros. Failure to meet this key tax milestone of the program calls into question whether Ukraine will receive the IMF tranches anytime soon.
U.S. Dollar Exchange Rate: Trends and Analysis
Controlled devaluation in the domestic foreign exchange market in May proceeded smoothly and without surprises. The official exchange rate at the beginning of the month stood at 43.96 UAH/USD, and on May 29, it was 44.26 UAH/USD. On the interbank market, the rate stood at 43.9–43.95 UAH per dollar in early May, and by the end of the month, the interbank rate had shifted to 44.28–44.31 UAH/USD. The National Bank remains the primary seller of foreign currency, which it sells through currency interventions; no panic demand was observed in May.
The cash market was also calm in May; citizens are calmly buying and selling dollars and euros at exchange offices and banks, and there is no foreign currency shortage. As of early May, the buying rate for cash dollars was 43.55–43.8 UAH/USD, and the selling rate was 44.10–44.25 UAH/USD. By the end of the month, the buying rate was 43.95–44.15 UAH/USD, and the selling rate was 44.35–44.6 UAH/USD. Spreads at the end of May rose to 0.5–0.7 UAH/USD.
Key influencing factors:
· Slow exchange rate fluctuations and subdued demand for foreign currency in May. The hryvnia is depreciating, but there is no panic buying; the NBU is meeting importers’ requests.
· Cash market—no currency shortage. Exchange offices and banks have sufficient supplies of dollars, and the public is showing subdued demand for foreign currency.
· International factors: The latest escalation in the Middle East is affecting investment plans; however, recent trends point to growing confidence in the dollar and dollar-denominated assets, and the dollar is steadily strengthening on the international market.
· Market expectations: While attention on the international market is focused on the new Fed chair and the June meeting of the Federal Open Market Committee, where key interest rates will be discussed, in Ukraine, hopes are pinned primarily on the absence of significant infrastructure damage in the near future, which would reduce the need for foreign currency to import equipment. The exchange rate is also influenced by the situation regarding the receipt of financial aid and the state of international reserves.
Forecast
Euro Exchange Rate: Trends and Analysis
Throughout May, the euro weakened against the dollar, and this trend was fully reflected in the Ukrainian foreign exchange market. While May began at 51.46 UAH/EUR, by the end of the month the exchange rate had reached 51.43 UAH/EUR.
The cash market remained largely unchanged despite the hryvnia’s gradual strengthening against the euro. While the buying rate stood at 50.95–51.4 UAH/euro in early May, and the selling rate was within the range of 51.75–52.10 UAH/EUR, by the end of May the buying rate was 50.85–51.3 UAH/EUR, and the selling rate was 51.75–51.90 UAH/EUR. As for spreads, they range from 0.4–0.6 UAH/EUR for most participants; only for some have spreads widened to 0.9–1 UAH/EUR.
Key influencing factors:
· On the international market, the trend of a strong euro has given way to a strengthening dollar. In May, the dollar strengthened thanks to investor optimism and attractive yields on U.S. Treasury bonds, though the war in Iran continues to influence the exchange rate trajectories of major currencies.
· Inflation in the EU is rising, but the ECB is taking a wait-and-see approach and keeping rates unchanged. It is expected that the ECB may raise interest rates in June, even if the war in the Middle East ends. Experts are convinced that the EU’s central bank will increase borrowing costs by 0.25 percentage points due to rising energy prices, which are significantly driving up inflation in Europe.
· Demand for the euro in Ukraine has stabilized. The cash market is influenced by currency supply from the public; there is no shortage of cash euros.
Forecast:
· Short term (2–4 weeks): On the Ukrainian market, the euro may remain within the range of 51.45–51.85 UAH/€.
· Medium term (2–4 months): if the ECB raises interest rates, the euro exchange rate on the international market is likely to strengthen; in Ukraine, fluctuations may occur within the range of 51.80–52.50 UAH/€.
· Long term (6+ months): The euro exchange rate may remain within the range of 52.20–53.80 UAH/€. Key influencing factors include the war in the Middle East, oil prices, the inflation rate in the Eurozone, and the ECB’s decisions on key interest rates.
Recommendations for Businesses and Investors
The dollar is steadily strengthening on the international market. Confidence in the U.S. currency is growing despite the ongoing escalation in the Middle East. The dollar’s strengthening implies a possible acceleration of the hryvnia’s depreciation trend.
War in Iran is one of the factors influencing the exchange rate, but it is no longer the key one. Negotiations between the U.S. and Iran have not yet reached the home stretch, but investors are once again actively buying U.S. Treasury bonds. This signals continued investment in dollar-denominated assets, and in Ukraine, it signals buying dollars as a reliable currency for building savings.
The Fed is preparing to adjust key interest rates. Possible rate changes as early as June could briefly disrupt the strong dollar trend in the global market; however, holding a portfolio with several liquid currencies helps minimize risks.
The U.S. dollar’s dominant position in the global market leaves no doubt: investing in the dollar is a reliable source of profit. Despite accelerating inflation, the U.S. economy is growing, and the dollar remains a liquid currency; therefore, investors should keep at least 50% of their assets in dollars.
Safe investments are a guarantee of capital preservation. In all financial scenarios, investors should identify stable sources of profit and ensure the reliability of their asset allocations.
Geopolitical tensions as a factor influencing investment plans. A successful resumption of negotiations between Washington and Tehran will signal further positive prospects for the dollar’s exchange rate trajectory.
Oil prices are a key indicator of changes in the foreign exchange market. Rising oil prices could increase the EU’s dependence on high energy costs, which would weaken the euro and, conversely, strengthen the dollar.
The focus is on liquid currencies. Despite geopolitical risks and inflationary spikes in both the EU and the U.S., the dollar and the euro remain the cornerstones for investors and should be included in both short-term and long-term currency strategies.
Diversification is the key to safe investments. Investors should build currency portfolios across different currencies, and while the dollar and the euro remain the core holdings, it’s advisable to periodically allocate to other reliable European currencies—such as the British pound and the Swiss franc.
The hryvnia is for short-term trading. The national currency is on a depreciation trajectory; therefore, it is best to build long-term savings in foreign currencies and hold the hryvnia only in the amount needed for quick investments in the national currency.
What’s important in the news. It’s essential to monitor everything related to the war in Iran, as well as the trajectory of oil prices. In June, it will be essential to monitor news from the U.S. regarding the Fed’s key interest rate, as well as the ECB’s decision on its base rate. In Ukraine, the main indicators of the situation in the foreign exchange market will be developments on the front lines, information on the state of the energy sector, news from the IMF, and announcements regarding the receipt of new loan tranches and international financial aid.
This material was prepared by analysts at KYT Group, an international multi-service product-based FinTech platform, and reflects their expert, analytical, and professional judgment. The information presented in this review is for informational purposes only and should not be construed as a recommendation for action.
The company and its analysts make no representations and assume no liability for any consequences arising from the use of this information. All information is provided “as is,” without any additional guarantees of completeness, or obligations regarding timeliness, updates, or additions.
Users of this material should independently assess risks and make informed decisions based on their own evaluation and analysis of the situation using various available sources that they themselves deem sufficiently reliable. Before making any investment decisions, we recommend consulting with an independent financial advisor.
REFERENCE
KYT Group is an international, multi-service, marketplace-style FinTech product platform that provides financial companies with access to services for promoting their offerings, as well as advertising and consulting services.
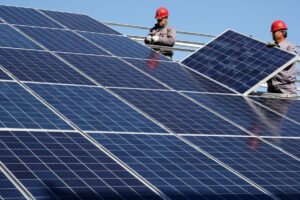
State-owned Oschadbank has provided Eco-Future “Kamianka” LLC with a EUR10.34 million loan for the construction of three solar power plants with a total capacity of 18.322 MW in the Khmelnytskyi region, the financial institution announced on Monday.
Along with the solar power plants, the company plans to install a 50 MW energy storage system. Once commissioned, the complex is expected to generate up to 22,600 MWh of electricity per year.
According to Oschadbank, this is the bank’s largest energy project in terms of financing volume in the micro, small, and medium-sized business (MSME) segment.
“Since the beginning of the year, Oschadbank has financed the construction of solar power plants with a total capacity of 42.6 MW for nearly 850 million UAH,” said Natalia Butkova-Vitvitska, a member of the bank’s management board responsible for the MSME segment.
The facilities will be built by Solar Stalkonstruktsiya LLC, which has been operating in the market since 2012 and has experience implementing over 5 GW of solar energy projects and energy storage systems in 20 countries.
According to the National Bank, as of July 1, 2026, Oschadbank, with total assets of 518.87 billion UAH, ranked second among Ukraine’s 59 banks. The bank’s total loan portfolio grew by 6.7% in the first half of the year, reaching 136.83 billion UAH.
INVESTMENT, Khmelnytskyi region, LOAN, OSCHADBANK, Solar energy
Rail shipments of grain to Danube ports in August 2026 nearly tripled compared to July—reaching 248.8 thousand metric tons, while shipments to the ports of Greater Odesa fell by 94.9%—to 68.5 thousand metric tons, according to a weekly review by the brokerage firm Spike Brokers.
Overall, rail grain shipments to seaports, including domestic shipments to Izmail, totaled approximately 317,300 metric tons in August, compared to 1.440 million metric tons in July. According to the brokerage firm, there was a sharp shift in cargo flows from the Greater Odessa region to the Danube.
In August, 1.297 million metric tons of grain were transported by rail—34.7% less than in July and 53.9% less than in August 2025. The average daily load amounted to 39.2 thousand metric tons, which is 22.5% lower than in July and 55% lower than in August 2025.
Exports of grain and milled products totaled 672.2 thousand metric tons, down 58.5% month-over-month and approximately 74% year-over-year. A total of 113,000 metric tons of vegetable oil were transported—15.4% more than in July and 54.7% more than in August 2025. Transportation of oilcake and meal totaled 167.1 thousand metric tons, down 9.3% month-over-month and 7.4% year-over-year.
In August, 501.8 thousand metric tons were transported via land crossings, compared to 208.8 thousand metric tons in July—a 2.4-fold increase.
The average daily throughput of grain cars through the main western border crossings in August was 192.8 cars, compared to 71.3 cars in July. The highest average daily figure was on the Polish route—56.6 cars. Through Hungary, 49.4 cars were transported per day; through Romania, 45.5; and through Slovakia, 41.4 cars.
Unlike in July, the August flow was distributed much more evenly among the four corridors.
As of September 3, there were 8,221 railcars en route to border crossings, of which 1,346 were loaded with grain, compared to 9,273 and 1,414 railcars, respectively, at the end of August. During the first days of the month, the total backlog decreased by approximately 11%, while the grain backlog decreased by 5%.
In August, 325,000 metric tons of agricultural products were exported via road border crossings, compared to 289,200 metric tons in July—an increase of 12.4%. Compared to August 2025, the volume was 23.7% higher.
Nearly half of August’s road freight traffic was destined for Poland—150,100 metric tons, or 46.2%. Among the largest categories in August were poultry meat—30,200 metric tons, sunflower oil—24,800 metric tons, ethyl alcohol—23,100 metric tons, sugar—18,600 metric tons, fruits and nuts—16.9 thousand metric tons, and soybean meal—15 thousand metric tons.
During the first three days of September, 33 thousand metric tons were exported by road, or about 11 thousand metric tons per day, compared to an average of 10.5 thousand metric tons per day in August.
In August, Ukraine exported 2.146 million metric tons of agricultural products in UKT ZED groups 01–24, worth $1.280 billion. The grain segment accounted for 987,100 metric tons, or 46% of the total volume, in the final August statistics: 612,700 metric tons of wheat, 305,700 metric tons of corn, and 68,700 metric tons of barley were shipped. Rapeseed accounted for another 292,600 metric tons, or 13.6% of exports. The three main vegetable oils totaled 279,100 metric tons, while sunflower and soybean meal totaled 187,200 metric tons.
The largest physical volumes went to Germany—227.1 thousand metric tons, Turkey—203.8 thousand metric tons, Italy—188.1 thousand metric tons, Poland—179.3 thousand metric tons, and the Netherlands—171.7 thousand metric tons. Together, these five countries accounted for about 45% of August’s exports.
From September 1–3, Ukraine exported 331.4 thousand metric tons of agricultural products worth $167.7 million, or about 110.5 thousand metric tons per day.