
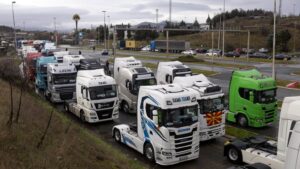
According to the Serbian business publication Parametar, Serbian carriers have officially confirmed preparations for a new regional blockade of freight traffic with the European Union. If a solution to the professional drivers’ issue is not found within the remaining week, freight traffic is scheduled to be halted at the borders of Serbia, Bosnia and Herzegovina, Montenegro, and North Macedonia with the EU starting at 12:00 a.m. on September 14. The action has been declared indefinite—until an acceptable solution is reached by Brussels.
In Serbia, the Association of International Road Carriers PUMEDTRANS plans to stage the action at 21 border crossings and transport points simultaneously. The list includes, in particular, Batrovci on the border with Croatia; Horgos and Kelebia on the border with Hungary; Vatin on the border with Romania; and Gradina on the border with Bulgaria. At major crossings, operations at inbound and outbound freight terminals are expected to be halted; at smaller ones, freight traffic on access roads will be stopped. Controlled passage of vehicles is planned at the intermodal terminal in the port of Novi Sad.
Moreover, this is no longer just a threat, as it was this summer. Following negotiations in early September, carriers decided to go ahead with the protest. On September 1, the European Commission made it clear that it has no intention of changing the basic Schengen rule of a 90-day stay within any 180-day period. Brussels acknowledges the problem faced by drivers, athletes, and other professionals whose jobs require high mobility, but suggests seeking solutions within the framework of existing rules—through long-term visas, residence permits, bilateral agreements, or, in certain cases, cross-border worker status.
For an international truck driver, every day spent in the Schengen Area counts the same as it does for a tourist, even if the driver is merely transiting through Slovenia or Hungary for a few hours. The EES system did not create this restriction, but electronic tracking of entries and exits has made it significantly easier and stricter to enforce. This is precisely what the European Commission confirms.
According to estimates by Serbian carriers, an international driver needs 120–130 days in the Schengen Area per half-year to operate normally. PUMEDTRANS claims that dozens of Serbian drivers are already being turned away at the borders every day, and that the utilization rate of the region’s fleets could have dropped by approximately 50% due to a shortage of available drivers. These are estimates from the industry association itself, not official EU statistics.
The risk is particularly high for Serbia due to the structure of its trade. From January through July 2026, the country’s foreign trade turnover reached 46.6 billion euros, an increase of 6.3% year-over-year. EU countries accounted for 58.6% of this total—approximately 27.3 billion euros in trade over just seven months. On average, this amounts to nearly 129 million euros in trade with the EU per day.
There is also a concrete benchmark for potential losses. During the previous blockade in January, Marko Čadež, president of the Serbian Chamber of Commerce and Industry, estimated the direct losses to the Western Balkan economies resulting solely from the halt in exports at approximately 100 million euros per day. Reuters cited a similar estimate at the time—about 92 million euros per day. The Chamber of Commerce and Industry also warned of fines ranging from 10 to 50 euros for late delivery of components and products
There is also a risk in the opposite direction. A prolonged blockade would delay imports of equipment, components, chemical products, food, and consumer goods into Serbia. However, shortages of food in stores or fuel are not expected after just one or two days of the blockade. A scenario in which the protest lasts a week or longer is significantly more dangerous.
There are no formal plans to block the border for ordinary motorists. But problems for travelers cannot be completely ruled out. The German-Serbian Chamber of Commerce (AHK) has already warned of possible disruptions to both freight and passenger border traffic.
The blockade of freight traffic between Serbia, Bosnia and Herzegovina, Montenegro, and North Macedonia and the European Union, scheduled for September 14, may also partially affect Ukrainian carriers. At the same time, the very reason for the protest—the restriction limiting professional drivers’ stay in the Schengen Area to 90 days within any 180-day period—also applies to Ukrainian citizens if they are traveling under the visa-free regime and do not have another status that allows for a longer stay.
For the bulk of Ukrainian trade with the EU, the direct impact should be limited. The main trucking corridors from Ukraine run directly through Poland, Slovakia, Hungary, and Romania, and Balkan carriers are not blocking these Ukrainian-European crossings. The protest also does not directly affect the main Ukraine–Romania–Bulgaria–Turkey route, nor the route to Greece via Romania and Bulgaria.
The situation is different for Ukrainian cargoes destined for Serbia, Bosnia and Herzegovina, Montenegro, North Macedonia, Albania, or parts of the Adriatic region. For example, a truck traveling from Ukraine to Serbia via Hungary must cross the Serbian-Hungarian border, where protesters plan to halt operations at freight terminals. A similar problem may arise on routes through Romania to Serbia, through Croatia to Bosnia and Herzegovina and Montenegro, as well as at the Bulgarian-Macedonian border.
At the same time, a vehicle’s Ukrainian registration will not guarantee passage. If the protest proceeds as announced and the operation of a freight terminal or access road is physically halted, the delay will affect the entire flow of freight, not just Serbian or Bosnian vehicles.
For Ukraine, the reason behind the Balkan blockade may prove to be far more significant than the blockade itself. Ukrainian international trucking companies are, in fact, in the same legal category as carriers from Serbia, Montenegro, or Bosnia and Herzegovina.
Ukrainian citizens with biometric passports have visa-free access to the Schengen Area, but the standard rules limit stays to no more than 90 days within any 180-day period. Ukraine is explicitly included in the list of visa-exempt third countries in the relevant EU regulation.
Furthermore, on February 13, 2026, the Association of International Road Carriers of Ukraine (AsMAP) issued a separate reminder to Ukrainian carriers regarding the 90/180 rule. The association recommended monitoring entry and exit dates to avoid fines or bans on future entry into the Schengen Area.
In other words, a driver for a Ukrainian transport company who regularly travels, for example, from Ukraine to Germany, France, Italy, or Spain could theoretically face the same problem that Balkan carriers are currently protesting. From the perspective of immigration law, a workday spent behind the wheel of a truck in the Schengen Area still counts as a day spent in the Schengen Area.
The problem became particularly noticeable after the full launch of the European Entry/Exit System (EES). It did not introduce the 90/180-day limit—which already existed—but automated the registration of entries and exits and the calculation of the length of stay. This is exactly how the European Commission explained the situation regarding Balkan drivers on September 1.
At the same time, Ukraine has a very important transportation advantage over most countries in the Western Balkans. The agreement on road freight transport between Ukraine and the EU—the so-called “transport visa-free regime”—has been extended until March 31, 2027. It allows Ukrainian and European carriers to carry out bilateral and transit shipments without the traditional permit system and has become an important part of the “Solidarity Lanes.”
The situation is somewhat different for Ukrainians who legally reside in one of the EU countries. For example, temporary protection or a residence permit allows a person to stay in the country that issued the document for longer than the standard 90 days. However, this does not mean unlimited movement throughout the EU. The European Commission explicitly states that after receiving temporary protection in one EU member state, a Ukrainian citizen may stay in other EU countries for up to 90 days within a 180-day period.
Thus, a Ukrainian driver who has been granted temporary protection—for example, in Poland—has no issues with long-term residence in Poland, but regular trips lasting several weeks through Germany, France, Belgium, the Netherlands, and other countries may still raise questions regarding the permitted duration of stay outside the country of residence.
Brussels itself has already effectively acknowledged the problem. In the first EU Visa Policy Strategy, published by the European Commission on January 29, 2026, international truck drivers are explicitly listed among the professions that may need to stay in various Schengen countries for more than 90 days within a 180-day period. The European Commission has stated that it will explore the possibility of creating a new pan-European “extended short-stay” regime for such professions. However, as of early September, this is merely a direction for future reform, not a current exemption.
Therefore, the Balkan conflict has implications for Ukraine that extend far beyond transportation through Serbia. If carriers in the Western Balkans succeed in securing a special regime for professional drivers at the EU level, Ukrainian international trucking companies will have clear grounds to demand that a similar mechanism be applied to them.
Conversely, if the EU maintains strict enforcement of the 90/180 rule without a pan-European professional exemption, the problem may gradually become more acute for the Ukrainian road transport sector as well. This is particularly important because, since 2022, road transport has become one of the key channels for Ukraine’s foreign trade: the European Commission estimated that, following the implementation of the transport agreement, the volume of Ukrainian road exports to the EU increased by approximately two-thirds, while imports rose by about 300,000 metric tons per month.
Regarding the blockade itself on September 14, the most realistic scenario for Ukraine appears to be as follows: 1–2 days of protests will result primarily in localized delays for cargo bound for the Balkans; a blockade lasting a week could already drive up trucking rates in Southeast Europe, cause vehicles to be rerouted, and increase queues on alternative routes through Hungary, Romania, and Bulgaria. If the protest drags on, the consequences could extend to industrial supply chains between Central Europe, the Balkans, and Ukraine.
As of July 1, 2026, 218,700 Ukrainian companies had tax debt totaling 263.32 billion UAH, according to data from the State Tax Service analyzed by Opendatabot.
On average, each debtor company owes about 1.2 million UAH in tax debt.
Since the beginning of 2026, the number of companies with tax debts has increased by approximately 3%, while the total amount of debt has risen by 4%.
At the same time, tax debt grew much more sharply in 2025. Over the past year, the number of companies in debt increased by only 4%, but the total amount of debt rose by approximately 1.6 times—nearly 100 billion UAH.
Overall, since the start of the full-scale war, the aggregate tax debt of Ukrainian companies has increased by 2.5 times. Based on current figures, it stood at approximately 105 billion UAH at the start of the full-scale invasion, meaning it has increased by roughly 158 billion UAH during this period.
Information on individual companies with the largest tax debts is currently unavailable. Since the start of the full-scale war, the State Tax Service has restricted access to some open data and has been publishing mainly aggregated statistics.
In August 2026, the volume of foreign currency purchases by Ukrainian households exceeded the volume of sales by $0.45 billion in dollar terms, compared to $0.5 billion in July of this year and $0.36 billion in August 2025.
According to data from the National Bank, in August, compared to July, cash currency purchases decreased by $68.8 million—to $1.9327 billion—while sales decreased by $17.0 million, to $1.4846 billion.
The volume of cash dollar purchases by the public in August increased by $28.9 million to $1,352.1 million, while sales decreased by $56.1 million to $1,034.6 million.
In the cash euro market in August, purchases by the public, in dollar terms, decreased by $108.1 million to $499.8 million, while sales increased by $26 million to $367.6 million.
As for bank customers’ non-cash foreign exchange transactions, both purchases and sales increased in August compared to July: purchases rose by $164.9 million to $11.1925 billion, and sales rose by $144.6 million to $7.6579 billion. At the same time, the volume of interbank transactions decreased by $409.9 million to $8,183 million.
On an annual basis, the volume of non-cash foreign currency purchases by bank customers increased by $2,904.0 million, sales by $998.2 million, and interbank transactions by $2,000 million.
In August, the official hryvnia-to-dollar exchange rate strengthened by nearly 14 kopecks compared to July—to 44.55 UAH/$1—while against the euro, the hryvnia weakened by nearly 61 kopecks—to 51.88 UAH/EUR1.
The National Bank’s net foreign exchange interventions in August rose to $4 billion 815.7 million, an increase of $24.7 million compared to July and $2 billion 119.8 million compared to August 2025.
Private landlords in the U.K. are increasingly selling properties or planning to exit the market amid rising financing costs and tax and regulatory burdens. The decline in supply is already leading to further increases in rent and is occurring at a time when the country is experiencing a change in government and a period of heightened economic uncertainty.
According to official data from the UK’s Office for National Statistics (ONS), in July 2026, the average private rent reached £1,393 per month, up 3.7% year-over-year. In England, the figure stood at £1,451, and in London, it was £2,317 per month.
A study by the Lomond agency network paints a similar picture, showing that British renters are already spending an average of 32.7% of their annual income on housing. According to the company’s methodology, the average rent was £1,369 per month, 4.3% higher than a year earlier. The discrepancy with ONS data is due to different sample sizes and calculation methods.
At the same time, supply from landlords is shrinking. A July survey by the Royal Institution of Chartered Surveyors (RICS) showed that new listings from landlords stood at -27%. Market participants report that landlords are reducing their portfolios or exiting the sector entirely. Despite more subdued demand from tenants, the balance of expectations for further rent increases rose to +28%.
A survey of more than 2,000 landlords conducted by Property118 in the second quarter paints an even bleaker picture: 40.2% had already reduced their portfolios over the previous two years, while only 6% had expanded them. Looking ahead to the next three years, 67.7% of respondents expect to sell at least part of their real estate holdings, while 27.1% intend to exit the market entirely.
One of the main reasons remains the high cost of borrowing. The Bank of England’s base rate stands at 3.75%, significantly higher than the levels seen during the era of cheap money prior to 2022. More than a third of the landlords surveyed will need to refinance their mortgages within the next year, which for many means switching from old, cheap fixed rates to significantly more expensive terms.
An additional factor has been the most significant reform of the private rental market in many years. As of May 1, 2026, the main provisions of the Renters’ Rights Act came into effect in England: Section 21 evictions without cause have been abolished, fixed-term leases are being replaced by a system of periodic tenancies, and landlords’ responsibilities have been strengthened. Starting in late 2026, the government will begin implementing a mandatory private rental housing registry, for which registration will incur a fee. Additional quality standards and a mandatory ombudsman will be introduced in the future.
That said, it would be incorrect to attribute the mass plans to sell properties solely to the new law. Pressure on the sector has been building for years due to tax changes, restrictions on mortgage interest deductions, and rising costs for insurance, repairs, and property maintenance. The new rules have merely become yet another factor forcing owners to reevaluate the economics of buy-to-let.
The situation in the housing market is unfolding against a backdrop of serious political instability in the United Kingdom. Keir Starmer stepped down as prime minister in the summer of 2026 after losing support within the Labour Party, and in September he decided to leave Parliament as well. He was succeeded by Andy Burnham, who became the UK’s seventh prime minister in a decade.
The new administration must simultaneously address the cost of living, the funding of social programs, and pressure on public finances. Yields on long-term British government bonds rose to approximately 5.26% in early September—a high not seen since 2008—which increases borrowing costs not only for the government but also, indirectly, for the entire economy. Investors are awaiting the new cabinet’s October budget and trying to understand how Burnham intends to finance his social and infrastructure initiatives.
It is still premature to speak of a full-blown economic crisis or recession in the UK. GDP grew by 0.4% in the second quarter of 2026, following 0.6% growth in the first quarter, though the pace of growth is slowing. Inflation accelerated again in July to 2.9%, unemployment reached 4.9%, and British businesses remain cautious about new investments.
It is precisely this combination of weak economic growth, high interest rates, and political uncertainty that is exacerbating problems in the rental market. The new cabinet aims to strengthen tenant protections, but as private landlords withdraw from the market, the opposite effect occurs: the fewer apartments available on the market, the greater the pressure on rent.
This presents a complex dilemma for the British government. If regulations and taxes continue to erode returns on private rentals faster than the government and institutional investors can build new housing, some of the costs of tenant protections may effectively be passed back to tenants in the form of higher rents and fewer housing options.
In the medium term, this could accelerate a structural shift in the British market: small private landlords will gradually be replaced by professional build-to-rent operators, pension funds, and investment funds capable of operating with lower returns and withstanding significantly stricter regulation.
Thus, the exit of British landlords is not an isolated real estate issue, but part of a broader picture: expensive capital, an economic slowdown, a crisis of political stability, and, at the same time, the government’s attempt to significantly tighten regulation of the housing market. For tenants, the main risk is not the mass disappearance of rental housing per se, but rather its continued rise in price and the shift in ownership from small landlords to large institutional investors.
The purchase price of sunflower seeds for domestic processing in Ukraine rose by $23 over the week—to $483 per metric ton on a CPT mill basis—while rapeseed prices rose by $5, to $485 per metric ton, according to brokerage firm Spike Brokers in its weekly market review.
According to the brokers, the rise in the purchase price of sunflower seeds was the strongest movement in the Ukrainian oilseed market. Over the week, the price of sunflower seeds on a CPT mill basis increased by 5%. The review does not contain data on changes in the export price of sunflower seeds.
Export prices for rapeseed remained unchanged over the week. On a CPT port basis, they stood at $520 per metric ton, and on an FCA Chop basis, at $555 per metric ton. The review did not provide data on changes in export prices for sunflower seeds.
Soybean prices at major Ukrainian delivery points remained unchanged. GMO soybeans were priced at $410 per metric ton CPT port, $450 FCA Chop, and $400 CPT mill; non-GMO soybeans were priced at $430 CPT port and $475 FCA Chop.
In August, Ukraine exported 147.1 thousand metric tons of sunflower oil, 110 thousand metric tons of sunflower meal, and 0.7 thousand metric tons of sunflower seeds.
Exports of rapeseed in August totaled 292.6 thousand metric tons, while rapeseed oil exports totaled 95.4 thousand metric tons. Rapeseed accounted for about 75% of the total tonnage of these two items.
During the month, Ukraine also exported 29.1 thousand metric tons of soybeans, 36.6 thousand metric tons of soybean oil, and 77.2 thousand metric tons of soybean meal. Oil and meal accounted for nearly 80% of the total export volume of these three soybean products.
Prices for food and feed wheat in Ukraine remained unchanged over the week—at $185 and $175 per metric ton, respectively, on a CPT Odessa basis, according to brokerage firm Spike Brokers in its weekly market review.
According to the broker, Ukraine exported approximately 612,700 metric tons of wheat in August. The top destinations were Spain (118,200 metric tons), Egypt (116,100 metric tons), and Algeria (78,100 metric tons). These three countries accounted for about 51% of August’s exports.
From September 1–3, Ukraine exported about 116,800 metric tons of wheat, or nearly 39,000 metric tons per day, compared to an average of about 20,000 metric tons per day in August. Destinations included Tunisia, Egypt, Indonesia, and Israel.
The price of corn also remained unchanged over the week: on a CPT Odessa basis, it stood at $185 per metric ton, and on an FCA Chop basis, at $225 per metric ton.
In August, Ukraine exported about 300,000 metric tons of corn. During the first three days of September, corn exports totaled about 69,200 metric tons. The main export destinations were Italy, Turkey, Germany, and the Netherlands.



