
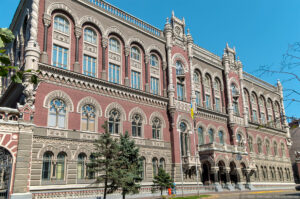
In August 2026, the National Bank of Ukraine imposed a fine of 17.6 million UAH on the state-owned Ukrgasbank for violating financial monitoring laws.
According to an NBU statement dated September 8, the regulator identified shortcomings in the bank’s application of a risk-based approach and in its conduct of due diligence on customers.
In particular, the National Bank pointed to the bank’s failure to take necessary measures in a timely manner regarding certain customers and its failure to apply enhanced due diligence measures to customers classified as high-risk business relationships.
Another reason for the fine was Ukrgasbank’s failure to properly provide information and documents in response to the regulator’s requests.
“Ukrgazbank” was the only bank against which the NBU imposed sanctions in August for violations of financial monitoring legislation. At the same time, the regulator fined four non-bank financial institutions, including the insurance company “USG,” 30.8 million UAH.
“Ukrgazbank” is one of Ukraine’s largest banks and is state-controlled. The Ministry of Finance of Ukraine owns 94.9409% of its shares.
As of the end of 2025, the bank reported a profit of 4.9 billion UAH, compared to 3.4 billion UAH a year earlier. Its assets at the end of the year totaled 215.2 billion UAH, an increase of 8.2% over the year, and its share of the Ukrainian banking system’s total assets reached 5.4%. Ukrgasbank’s share of the banking system’s loan portfolio was 8.5%.
The bank has been operating since 1993 and provides corporate, retail, and investment banking services, as well as financing for energy, infrastructure, and environmental projects.
According to the Relocation project, the European Commission has proposed new rules that will allow EU cities and regions to restrict short-term apartment rentals through Airbnb, Booking, and other platforms in areas with a severe shortage of affordable housing.
The Affordable Housing Act was presented by the European Commission on September 9, 2026, and must now be reviewed by the European Parliament and the Council of the EU. This is not about a blanket ban on short-term rentals across the entire European Union, but rather about creating a common legal framework within which local authorities can impose restrictions where they can demonstrate the negative impact of tourist rentals on the housing market.
According to the draft, an area may be designated a “housing-stressed zone” if the cost of an average apartment is equivalent to at least eight years of disposable income per capita, this ratio has been rising over the past ten years, and the housing shortage is likely to persist for at least another three years. If the housing-to-income ratio reaches ten years, the requirement for this ratio to have increased over the previous ten years will not apply.
However, high prices alone will not be sufficient. To impose restrictions, local authorities will have to prove that short-term rentals have, for at least three years, significantly worsened housing affordability or increased housing costs in a specific area, and that less restrictive measures are not capable of solving the problem with the same effectiveness.
The restrictions should primarily apply to apartments used for commercial purposes that are not the owner’s primary residence. Renting out one’s primary residence to tourists is proposed to be exempt from such restrictions. When assessing the commercial nature of the activity, authorities will be able to consider the number of apartments owned by a single owner and the frequency with which they are rented out.
Thus, cities will be able to impose limits on the volume of short-term rentals, restrict the use of investment apartments for accommodating tourists, or apply other measures; however, these must be geographically limited, justified, and proportionate to the problem. Transitional periods must be provided for existing, legally compliant properties. The maximum initial duration of the restrictions will be five years, after which the need to maintain them must be reviewed.
The new proposals supplement the European regulation on transparency in short-term rentals, which already entered into force on May 20, 2026. It requires the registration of properties and the transfer of data by platforms to local authorities, and also allows for the removal of listings with missing or invalid registration numbers.
The European Commission notes that the number of short-term rental properties in the EU increased by approximately 93% between 2018 and 2024, and such apartments now account for about a quarter of the EU’s tourist accommodation supply. At the same time, housing prices in the EU have risen by more than 60% since 2013, and rents by approximately 20%.
The new rules are likely to have the most significant impact on tourist destinations with both high demand for housing and limited hotel supply—specifically, Paris, Barcelona, Amsterdam, Rome, Florence, Venice, and other popular cities.
For tourists, the downside of these restrictions could be rising accommodation costs. In its own impact assessment of the Affordable Housing Act, the European Commission explicitly acknowledges that a reduction in the number of apartments available for short-term rentals could limit the choice of tourist accommodations and lead to higher prices, especially in places where the hotel market is already operating near full capacity.
As a point of reference, the European Commission cites the experience of New York, where, following a de facto ban on a significant portion of short-term rentals, the average cost of a hotel room, according to a study, increased by approximately $14–19 per night, and the additional revenue for hotels over the first 18 months was estimated at $2.1–2.9 billion. The study’s authors found that the revenue growth was primarily driven by higher rates rather than an increase in the number of nights sold.
The U.S. findings cannot be directly applied to Europe, as the structure of hotel supply varies significantly from city to city. However, for a major European tourist destination where a hotel room or apartment currently costs 150–200 euros per night, a comparable increase in absolute terms would mean an additional 7–13% in accommodation costs.
According to our estimates, assuming moderate restrictions that merely reduce the number of professional Airbnb listings, the average impact on tourists would most likely be 5–7%. In popular areas with strict restrictions and a shortage of hotel rooms, the increase could be 5–10%, and during holidays, trade shows, and peak tourist season, it could temporarily exceed 10–15%.
For example, if an apartment currently costs 120 euros per night, a 5–10% surcharge would mean an additional 6–12 euros per day or 42–84 euros for a week’s stay. For a property costing 200 euros per night, a 10% increase would raise a tourist’s expenses by approximately 140 euros for a week-long trip.
At the same time, the effect on permanent residents is expected to be the opposite. The European Commission anticipates that returning a portion of tourist apartments to the long-term rental market will increase the housing supply and slow the rise in rental rates. The impact assessment cites a study from Barcelona: in neighborhoods with an average level of Airbnb presence, its impact was associated with an approximate 2% increase in long-term rentals and a 4.4% rise in housing costs, while in neighborhoods with the highest concentration of tourist rentals, the effect reached 7% and 17%, respectively.
Kalshi recorded $37.17 billion in trading volume in August, down 7.3% from July’s $40.1 billion. Polymarket, together with the U.S. platform, accounted for an additional $8.16 billion, compared to $12.89 billion the previous month—a 36.7% decline, according to the Fixygen portal.
At the same time, after record activity in the summer, trading volume fell by 14.5% compared with July. This was the first monthly decline in approximately a year, according to data from The Block.
Kalshi accounted for $37.17 billion in turnover in August, which was 7.3% less than July’s $40.1 billion. Polymarket together with the U.S. platform generated another $8.16 billion compared with $12.89 billion a month earlier, meaning volume declined by 36.7%.
However, even after the decline, the August market remained significantly larger than in May, when combined turnover amounted to around $25.66 billion.
This segment is developing especially rapidly within traditional brokerage platforms.
Robinhood reported on September 8 that in the second quarter alone, 13.6 billion event contracts were traded through its service, while in the first eight months of 2026 more than 30 billion contracts were traded. Since the launch of the business about two years ago, Robinhood clients have entered into more than 45 billion such contracts.
The company is expanding the number of venues through which trades are executed. In addition to Kalshi and ForecastEx, Robinhood uses Rothera, and from September 8 began routing some contracts to the Crypto.com platform through CFTC-regulated infrastructure.
The company is also launching a separate prediction markets section for the U.S. midterm elections and expanding its offering of contracts on American football.
Prediction markets allow participants to buy and sell contracts whose payouts depend on the occurrence of a specific event — the result of a sports match, an election, an economic indicator or another measurable event.
In terms of their economic structure, such instruments lie between financial derivatives and traditional betting, which simultaneously ensures their rapid growth and creates regulatory disputes.
In the United States, more than ten states have already taken legal or administrative action against Kalshi or Polymarket, primarily over sports contracts.
CRYPTOCURRENCY, KALSHI, Polymarket, PREDICTION MARKETS, ROBINHOOD
Law enforcement officials have uncovered a large-scale scheme involving the illegal production and distribution in Ukraine of the counterfeit weight-loss drug “Biopatid,” in connection with which 27 individuals have been notified of their status as suspects, according to a Sunday announcement by the press service of the Office of the Prosecutor General on its Telegram channel.
According to the investigation, the suspects include the scheme’s organizer and owner of the underground laboratory, the owner of a well-known Kyiv clinic, a customs broker, laboratory workers, packagers, sales and advertising managers, as well as other participants in the criminal activity.
The cost of the main ingredients was about $17, while the finished product was sold for up to $1,200. According to preliminary data, products totaling more than $5 million have been manufactured since the beginning of this year.
“The mastermind behind the scheme, aware of the high demand for weight-loss drugs and the high cost of medications containing the active ingredient tirzepatide, decided to set up his own illegal ‘pharmaceutical business.’ To this end, he set up an underground laboratory where a generic version of the drug was manufactured without any permits or quality control,” according to a statement released by the press service.
The raw materials were subsequently used in the underground laboratory. The participants in the scheme created a website and social media pages, recruited sales managers, and actively advertised the drug.
They offered it to beauty salons, clinics, and healthcare professionals in various regions of Ukraine. Bloggers, actors, and other public figures were also enlisted to promote the product.
As part of the criminal investigation, law enforcement officers conducted more than 250 authorized searches at locations where the counterfeit drug was manufactured, stored, sold, and distributed, as well as at hospitals and cosmetic clinics.
Investigative actions were carried out in Kyiv and the Kyiv region, Dnipro, Zaporizhzhia, Odesa, Poltava, Vinnytsia, Zhytomyr, Mykolaiv, Rivne, Kharkiv, Khmelnytskyi, and Chernihiv.
During the searches, investigators seized the counterfeit drug and raw materials used in its production, equipment from an underground laboratory, packaging materials and finished printed materials, documentation and drafts, as well as cell phones and computer equipment.
Law enforcement officers also seized cash in various currencies totaling nearly 15 million hryvnias, luxury cars, and other property.
The issue of imposing preventive measures on all suspects is currently being resolved.
The investigations were conducted by prosecutors in collaboration with SBU officers.
In accordance with Article 62 of the Constitution of Ukraine, a person is presumed innocent of a crime and may not be subjected to criminal punishment until their guilt has been proven in accordance with the law and established by a court conviction.
Perfect Group plans to expand its rental real estate business in Kyiv and transfer some of the apartments in its complexes to professional management by hotel operators.
As the company’s CEO, Oleksiy Koval, stated in an interview with Interfax-Ukraine on September 1, 2026, the first such project is being developed in the LA MANCHE residential complex at 46 Shchekavitska Street in Podil. Forty apartments have been allocated for this income-generating real estate project.
The operator will focus primarily on long-term rentals.
Another project is being developed as part of the Stanford residential complex at 35 Predslavinskaya Street. Here, a separate section is planned for short-term rentals, and Perfect Group is in negotiations with a major professional operator.
The developer also plans to extend some hotel services to the other residents of the residential complexes. These include concierge services, babysitting, children’s playrooms, dog-walking, and other additional services.
According to Koval, after a period of competition among developers based on price, architectural concept, and infrastructure, the next key factor in market competition will be service quality.
For comfort-class housing, the company intends to develop a similar approach through digitalization. Perfect Group is developing an app to facilitate communication between residents and the management company, process requests, and vote on additional services. Its launch is planned for before the end of 2026.
In addition to income-generating real estate projects in Kyiv, Perfect Group is building the VELMY aparthotel in Polyanytsia near Bukovel.
Bitcoin mining profitability rebounded significantly in August 2026 thanks to a sharp rise in the price of the largest cryptocurrency, but the industry’s economics remain substantially weaker than last year’s levels, according to Fixygen.
According to the monthly Luxor Hashrate Index report published on September 8, the dollar-denominated hashprice—the estimated miner’s revenue per unit of computing power—started August at $31.63 per PH/s per day and ended the month at $39.33, an increase of 24.4%.
This marked the strongest monthly growth in the metric since November 2024. On August 27, the hashprice temporarily rose above $40 for the first time in 220 days.
Bitcoin was the main driver behind the improvement in mining economics. In August, its price rose from $62,889 to $78,312, an increase of 24.5%. The average BTC price for the month increased by 8.7% to $69,263.
The average hashprice for August was $34.63, compared to $31.21 in July, an increase of 10.9%.
However, even after this recovery, profitability remains significantly lower than last year’s levels. The average August hashprice was approximately 32% lower than the 2025 average of $50.68 per PH/s per day.
Relatively stable network difficulty provided additional support to miners. In August, two adjustments nearly offset each other, and the net change amounted to approximately minus 0.34%. The average difficulty was 2% lower than in July.
However, as early as September 5, network difficulty rose by 1.31% as some of the computing power that had previously been taken offline began returning to the network. Luxor notes that mining activity is recovering following the hashrate decline in June and July.
The increase in computing power could once again put pressure on profitability. The more equipment competes for a fixed block reward, the smaller the share of revenue per unit of hashrate.
The situation also remains challenging for less efficient equipment. According to Luxor’s estimates, devices with energy efficiency of 25–38 J/TH generated an average energy yield of about $45 per MWh in August, while the average grid electricity cost was about $48 per MWh. This means that some older equipment remains at or below the break-even point.
As a result, August provided miners with a noticeable respite, but the sustainability of the recovery will depend on three factors at once: Bitcoin prices, network difficulty, and the cost of electricity.



