
According to Fixygen, the cryptocurrency market is ending the week of September 14–18 with a moderate rebound following sharp volatility: Bitcoin has returned to around $78,000, Ethereum is holding above $2,500, although U.S. spot ETFs recorded net outflows, and the U.S. Federal Reserve raised interest rates for the first time in more than three years.
According to CoinGecko data as of September 18, Bitcoin is trading at approximately $78,100, Ethereum at $2,510, BNB at around $750, and XRP at around $1.33. The total market capitalization of the cryptocurrency market is approximately $2.77 trillion, with a daily trading volume of about $93 billion. Over the past seven days, Bitcoin has risen by about 1%, Ethereum by 1.2%, BNB by more than 5%, and XRP by approximately 1.5%.
The start of the week was significantly more volatile. On September 14, Bitcoin was trading around $78,200, but by September 15, it had fallen to approximately $75,600. The next day, prices remained near $76,100, after which the market began to recover through Friday.
One of the main factors putting pressure on the market was the decision by the U.S. Federal Reserve. On September 16, the Fed unanimously raised the target range for the federal funds rate by 25 basis points—to 3.75–4%. The U.S. central bank attributed the decision to persistently high inflation. This marked the Fed’s first rate hike since 2023.
An additional source of uncertainty for the crypto industry was the U.S. Senate vote on H.R. 3633, known as the CLARITY Act, which aims to establish a comprehensive regulatory framework for the digital asset market and delineate the respective authorities of the SEC and the CFTC. On September 15, a procedural vote to move the bill to the floor ended with 49 votes in favor and 50 against, while three-fifths of the Senate’s votes were required for passage.
Against this backdrop, institutional flows into cryptocurrency ETFs remained negative for most of the week. According to Farside Investors, over the four trading sessions from September 14–17, U.S. spot Bitcoin ETFs recorded a combined net outflow of approximately $427 million. Following an inflow of $159.9 million on Monday, investors withdrew $450.4 million on Tuesday and $295.9 million on Wednesday. On Thursday, the trend reversed, with a net inflow of $159.5 million. Data for Friday had not yet been compiled at the time this review was prepared.
The performance of Ethereum ETFs was even weaker. Over the same period, net outflows from U.S. spot Ethereum funds totaled approximately $284 million. On Monday, the funds attracted $121.1 million, but over the next three trading sessions, they lost $142 million, $224.1 million, and $39.3 million, respectively.
At the same time, at the end of the week, the crypto industry received a positive regulatory signal from the U.S. Securities and Exchange Commission (SEC). On September 17, the SEC introduced the so-called Innovation Exemption—a temporary five-year regime that, under certain conditions, allows for the trading of tokenized shares of U.S. companies via blockchain infrastructure and permissioned AMM pools. The SEC emphasized that tokenized shares must grant holders the same rights as the corresponding traditional securities.
The news boosted companies involved in digital assets and was one of the factors behind the recovery in market sentiment at the end of the week. In Friday’s trading, Coinbase shares rose by more than 3%, Strategy by about 4%, and Robinhood by 3.5%, while Bitcoin climbed back to the $78,000 range.
At the same time, the global macroeconomic backdrop remains challenging for risk assets. The yield on 10-year U.S. Treasury bonds exceeded 5% this week, and the price of Brent crude remained above $100 per barrel amid geopolitical tensions and risks to energy supplies. High oil prices exacerbate inflationary risks and may support a tighter monetary policy by central banks, which traditionally curbs demand for crypto assets.
Thus, according to Fixygen’s assessment, the main outcome of the week was the resilience of the largest cryptocurrencies in the face of a simultaneous deterioration in the monetary and regulatory environment. Bitcoin closed the previous week near $77,100 and, as of September 18, is trading above $78,000, while the crypto market’s total market capitalization rose from approximately $2.73 trillion to $2.77 trillion.
At the same time, negative outflows from ETFs indicate that the recovery has not yet been accompanied by a steady return of large institutional capital. Next week, the market will continue to be driven by expectations regarding the Fed’s next moves, trends in U.S. bonds and oil, inflows into cryptocurrency ETFs, and the future of legislation governing the structure of the U.S. cryptocurrency market.
According to Fixygen, the cryptocurrency market is ending the week of July 13–17 at a level close to where it started: Bitcoin is trading at around $63,000, while the total market capitalization of digital assets stands at approximately $2.2 trillion.
As of Friday, Bitcoin was trading at around $63,020, down approximately 1.7% over the past 24 hours. The leading cryptocurrency’s share of the total market capitalization is estimated at 56–58%. Ethereum, Solana, and most other major digital assets were also under pressure. SOL was trading at around $78, and XRP at around $1.06.
On Monday, Bitcoin fell below $62,000 amid a new escalation of the conflict between the U.S. and Iran, rising oil prices, and an exodus of investors from risky assets. After the release of U.S. inflation data, which came in weaker than expected, the cryptocurrency rebounded and rose above $65,500 on July 15, but was unable to sustain the gains.
By the end of the week, pressure on the crypto market intensified due to a sell-off in tech and semiconductor stocks, rising oil prices, and new geopolitical risks in the Middle East. On Friday, Bitcoin lost about 2% over the course of the day and returned to the $63,000 level.
Capital flows in U.S. spot Bitcoin ETFs remained volatile. On Monday, the funds recorded a net outflow of $424.7 million, followed by inflows of $181.1 million on Tuesday, $107.7 million on Wednesday, and $79.1 million on Thursday. As a result, the cumulative outflow over the four trading days totaled approximately $56.8 million. Data for Friday had not yet been published at the time of writing.
An additional source of uncertainty was the debate in the U.S. over the Clarity Act, a bill intended to establish regulations for the cryptocurrency market and delineate the powers of financial regulators. Progress on the bill has slowed due to disagreements in the Senate and concerns about a potential conflict of interest related to President Donald Trump’s cryptocurrency holdings.
In the corporate sector, the week’s main event was Citadel Securities’ investment in the cryptocurrency exchange Crypto.com. The market maker invested $400 million, valuing the platform at $20 billion. This is Crypto.com’s first round of institutional funding. The funds raised are planned to be directed toward the development of operations involving tokenized securities and derivatives.
At the same time, pressure remains on public companies that have built up large Bitcoin reserves. Strategy has already sold approximately $218 million worth of digital assets in 2026 to fund dividends and maintain its dollar reserves. The decline in cryptocurrency prices has led to the shares of a number of similar companies trading below the value of the digital assets they hold.
Thus, softer U.S. inflation data and the resumption of capital inflows into ETFs have failed to ensure a sustained market recovery. Next week’s market dynamics will depend on developments in the Middle East, oil prices, capital flows into cryptocurrency funds, and further progress on U.S. legislation regarding digital assets.
According to Fixygen, the cryptocurrency market ended the week with a partial recovery after Bitcoin fell below the psychological threshold of $60,000, however, the main topics for the industry remained outflows from ETFs, major banks revising their forecasts, intensifying regulatory competition surrounding stablecoins, and miners shifting to the AI data center sector.
At the time of writing, Bitcoin was trading around $62,440, while Ethereum was trading around $1,625. Earlier in the week, BTC fell below $60,000 amid weak demand from institutional investors, outflows from exchange-traded funds, and persistent geopolitical risks.
Data on U.S. spot Bitcoin ETFs served as a key negative signal. According to CoinDesk, citing SoSoValue, the funds recorded $4.5 billion in net outflows in June—the worst month since the launch of such products in January 2024. The previous record low was $3.48 billion in February 2025.
Against this backdrop, Citigroup lowered its 12-month price forecast for Bitcoin from $112,000 to $82,000, and for Ether from $3,175,000 to $2,240,000. The bank attributed the revision to waning investor interest, outflows from ETFs, and a lack of rapid progress in U.S. crypto regulation. Citi also lowered its expectations for net inflows into Bitcoin ETFs from $10 billion to zero.
The week’s regulatory agenda focused primarily on stablecoins. In the UK, the FCA eased its final requirements for stablecoin issuers, lowering the proposed capital reserve from 2% to 1% of the issuance volume. The final rules are set to bring the crypto-asset sector fully under FCA supervision starting in October 2027.
This is an important signal for the global market: jurisdictions are beginning to compete not only for crypto exchanges but also for tokenized payment infrastructure. Following increased U.S. scrutiny of dollar-pegged stablecoins, the UK is attempting to make its own regulations more proportionate so as not to lose companies working with payment tokens.
Another trend of the week is the continued expansion of Bitcoin miners into the AI and data center sectors. Reuters reported that the Hunt and Crow families—both American billionaire families—along with Nasdaq-listed company Empery Digital, have signed an agreement for a $230 million industrial facility with a capacity of 150 MW and plan to convert it into a hyperscale data center. The parties also signed a non-binding letter of intent for a $1 billion lease with a cloud computing company.
Another telling example is Ionic Digital, a company that positions itself as both a Bitcoin miner and an AI infrastructure company, which has filed for a direct listing on Nasdaq. This confirms structural changes in the sector: for some miners, the key asset is no longer so much hash rate as access to electricity, land, substations, and permits for data centers.
For miners, this diversification has been a response to the deteriorating economics of Bitcoin mining following the halving, high network difficulty, and falling BTC prices. Reuters previously noted that crypto miners are increasingly using large energy facilities for artificial intelligence (AI) computing, as mining profitability remains volatile and demand for AI data centers is growing rapidly.
The week also demonstrated a shift in investor sentiment. Following a strong first half of the year for AI-related stocks, part of the market began looking for opportunities to rotate back into Bitcoin after a deep correction. CoinDesk noted that a loss of momentum in the segment of stocks for companies involved in memory and semiconductor manufacturing could raise the question of returning some capital to BTC; however, traders are not yet showing full confidence in the sustainability of the rebound.
From a practical standpoint, the market situation looks like this: Bitcoin has recovered above $60,000 but has not received sufficiently strong institutional validation via ETFs. Ethereum remains under pressure from weaker network activity and lower forecasts, while stablecoins and AI data centers are becoming the most dynamic segments of the crypto infrastructure.
In the coming weeks, key factors for the market will remain the dynamics of inflows and outflows in spot ETFs, macroeconomic expectations regarding U.S. interest rates, regulatory signals regarding stablecoins, and Bitcoin’s ability to consolidate above $60,000. If outflows from ETFs continue, the market may revert to a defensive scenario. If, on the other hand, institutional demand stabilizes, July could be a month of technical recovery following a weak June.
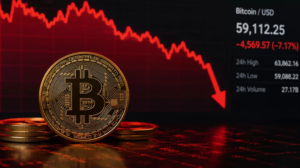
According to Fixygen, the cryptocurrency market is ending the week on a down note: Bitcoin has once again fallen below the psychological $60,000 level, Ether has approached $1,550, and most major altcoins are trading under pressure amid capital outflows from crypto ETFs, harsher expectations regarding Fed interest rates, and a strengthening dollar.
As of Thursday and Friday, Bitcoin was trading around $59,200, down approximately 3% over the past 24 hours.
The intraday low was around $58,200. Ether fell to $1,550, losing about 5.5% over the day, while Solana held steady around $68–69.
The week marked a continuation of June’s weak performance. Earlier this month, Bitcoin was trading above $70,000, but the market then faced a series of negative factors: record or near-record outflows from U.S. spot Bitcoin ETFs, growing investor interest in stocks of companies related to artificial intelligence, a strengthening U.S. dollar, and deteriorating sentiment surrounding major corporate Bitcoin holders.
This week, the pressure intensified after Bitcoin once again fell below $60,000. CoinDesk noted that the cryptocurrency’s decline is occurring even amid periodic gains in other risky assets, as capital continues to flow into the technology and AI segments of the stock market. According to CoinDesk, Deutsche Bank attributed Bitcoin’s drop below $60,000 to the Fed’s hawkish rhetoric, outflows from ETFs, and concerns surrounding companies with high Bitcoin exposure.
Ethereum has also failed to serve as a safe-haven asset within the crypto market. Trading at around $1,550, the second-largest cryptocurrency by market capitalization remains under pressure alongside the broader market. The decline in ether indicates that investors are currently reducing their exposure to crypto assets in general, not just bitcoin.
Solana appeared slightly more resilient intraday, but the overall sentiment for altcoins remains weak. When Bitcoin falls below key levels, investors typically reduce their positions in riskier tokens faster than in the market’s core assets.
The dynamics of spot Bitcoin ETFs in the U.S. remain a separate factor. In June, the market already experienced several waves of outflows from funds that had previously been one of the main sources of demand for Bitcoin. When ETFs stop supporting the market with inflows, Bitcoin becomes more sensitive to macroeconomic data, yields, the dollar, and overall risk appetite.
Globally, cryptocurrencies are now competing for capital not only with traditional assets but also with the AI sector. Reuters previously noted that investors are increasingly shifting funds toward AI-related stocks and anticipated major IPOs, while bitcoin is experiencing one of its weakest starts to the year in the past decade.
Through the end of the week, the key technical level for Bitcoin remains the $58,000–$60,000 range. Holding this range could give the market a chance to stabilize, but a sustained move below $58,000 would reinforce expectations of a further decline. In this case, the next area of focus could be $55,000, which some analysts view as a potential level for a local bottom to form.
The base case scenario for the coming days is heightened volatility and cautious attempts at stabilization following the sharp decline. For a sustained recovery, the market will need a combination of several factors: an end to outflows from ETFs, a weaker dollar, softer expectations regarding Fed interest rates, and a return of risk appetite for crypto assets.
For now, the crypto market remains in defensive trade mode: investors prefer to reduce their exposure, cut their losses, or wait for new signals from ETF flows and the U.S. macroeconomy.
According to Fixygen, the cryptocurrency market is ending the week on a cautious note: Bitcoin is holding steady near $62,500–63,000, Ethereum is around $1,700, and the total market capitalization remains in the range of $2.15–2.24 trillion.
Following the sell-off in early June, the market is attempting to stabilize, though a confident recovery has not yet materialized. The main source of pressure remains shifting expectations regarding the U.S. Federal Reserve’s monetary policy. The Fed kept its benchmark rate in the 3.50–3.75% range but sent a more hawkish signal to the market: some market participants now anticipate a rate hike by the end of the year. This is a negative backdrop for the crypto market, as Bitcoin and other digital assets are traditionally sensitive to expectations regarding liquidity and the cost of money.
Bitcoin remained within a narrow range this week following attempts to rebound. According to current data, it is trading at around $62,600, with the intraday low dropping to $62,300. Ethereum fell to $1,690 and remains weaker than Bitcoin in terms of market structure. Pressure on altcoins persists as investors favor more liquid assets and avoid elevated risk.
The total crypto market capitalization, according to aggregators, stands at around $2.15–2.24 trillion. Bitcoin’s market share remains high—around 56–58%—indicating that a protective bias persists within the crypto market itself. Investors are not completely exiting digital assets but are focusing on the largest cryptocurrency and stablecoins.
ETF flows created additional pressure. According to VanEck’s estimates, in the first half of June, Bitcoin’s 30-day average price fell to approximately $70,300, and U.S. spot Bitcoin ETFs recorded about $5 billion in net outflows during 19 of 22 trading sessions. After that, signs of stabilization emerged: on June 12, spot Bitcoin ETFs showed a net inflow of about $85.8 million, and on June 16, about $10 million. However, these volumes are not yet sufficient to indicate a full-fledged recovery in institutional demand.
Ethereum’s weakness is also linked to less stable demand for spot ETH ETFs. Last week, certain trading days saw outflows from Ethereum ETFs, while demand for Bitcoin funds began to gradually recover after a series of heavy outflows. This widens the gap between Bitcoin and the rest of the market.
The Fear and Greed Index for the crypto market remains in the “extreme fear” zone. This means that following June’s sell-off, market participants are not yet ready to actively build up their positions. The market is reacting more to macroeconomic signals than to internal industry news.
The geopolitical backdrop this week was mixed. On the one hand, the agreements between the U.S. and Iran and expectations of a resumption of traffic through the Strait of Hormuz eased pressure on the oil market and supported overall risk appetite. On the other hand, uncertainty regarding the sustainability of these agreements, sanctions policy, and the Fed’s next moves is holding investors back from aggressively buying cryptocurrencies.
For Bitcoin, the nearest technical levels remain the $60–62 thousand range as support and $65–67 thousand as resistance. A sustained move above this range could improve the short-term outlook, but without a resumption of capital inflows into ETFs and a more dovish signal from the Fed, the market may remain range-bound.
According to Fixygen, the cryptocurrency market is entering June with heightened caution: Bitcoin is trading near the $73,000 mark, Ethereum is trading around $2,000, and investors are assessing several risk factors at once—the U.S.-Iran conflict, high oil prices, outflows from crypto ETFs, the upcoming Fed meeting, and the MiCA deadline for crypto companies in the EU.
Following the May decline, the main issue for the market will be not only Bitcoin’s performance but also broader risk appetite. If geopolitical tensions in the Persian Gulf persist, investors may continue to reduce their positions in risky assets, including cryptocurrencies. For BTC, this means the risk of continued trading within a wide range without a sustained recovery, and for altcoins, even greater sensitivity to liquidity.
The first key macroeconomic indicator will be the U.S. labor market report for May, which will be released on June 5. Strong employment data could dampen expectations of Fed policy easing and support the dollar and bond yields. For the cryptocurrency market, this is traditionally a negative combination, as more expensive money reduces interest in assets without a stable cash flow.
The second set of risks is related to oil. A meeting of select OPEC+ countries, which coordinate voluntary production cuts, is expected on June 7. Under normal circumstances, this would be primarily an oil-related event, but currently, the energy factor directly influences inflation expectations, central bank policy, and investor behavior. If the market perceives a risk of an oil shortage or a new surge in prices, crypto assets could come under pressure again due to fears of tighter monetary policy.
On June 10, U.S. inflation data for May will be released. This is one of the month’s key events for Bitcoin and Ethereum. If the CPI shows an acceleration due to fuel and transportation costs, the market may price in fewer chances of rate cuts in 2026 or even begin discussing the risk of further policy tightening. If inflation turns out to be lower than expected, the cryptocurrency market could receive short-term support.
On June 11, the European Central Bank will announce its interest rate decision. This is important for the cryptocurrency market due to the euro, liquidity in Europe, and the overall revaluation of risk assets. Due to high energy prices, inflationary pressures in the eurozone have intensified again, so investors will be closely watching the ECB’s signals regarding its next steps.
The key event of the month will be the Fed meeting on June 16–17. It will be accompanied by updated economic forecasts and FOMC members’ rate expectations. For the cryptocurrency market, not only the decision itself but also the tone of the comments will be important: if the Fed acknowledges inflation risks stemming from oil and geopolitics, Bitcoin may remain under pressure. If, however, the regulator emphasizes the economic slowdown and the need to preserve room for future easing, the market may attempt a recovery.
A separate factor in June will be EU regulation. By June 30, crypto companies must obtain licenses under MiCA rules or risk facing restrictions, blacklists, and regulatory claims. For large players, this may be a step toward legalization and trust, but for small exchanges and providers, it poses the risk of losing access to EU clients.
ETF flows will remain one of the most important short-term indicators. Following an outflow of over $2 billion from Bitcoin ETFs in early June, the market will be watching closely to see if institutional investors return to buying. If outflows continue, it will be harder for BTC to hold above key technical levels. If funds show inflows again, this could signal a stabilization of demand.
The geopolitical front remains the most unpredictable. A U.S.-Iran war, risks to the Strait of Hormuz, the situation in the Middle East, the war in Ukraine, and tensions surrounding global trade could drastically shift investor sentiment. Cryptocurrencies behave erratically under such conditions: sometimes Bitcoin is perceived as an alternative asset, but in the short term, it more often reacts as a risky instrument and falls alongside stocks and the tech sector.
For Ethereum, June will be even more challenging than for Bitcoin. ETH depends not only on the broader market but also on activity in DeFi, NFTs, L2 networks, and demand for spot Ethereum ETFs. If liquidity remains weak, Ethereum may lag behind Bitcoin, while altcoins could exhibit even higher volatility.
The base case for June assumes continued high volatility and Bitcoin trading within a wide range without a clear trend until the release of inflation data and the Fed’s decision. A positive scenario for the market would be a combination of weaker inflation, oil price stabilization, a resumption of inflows into ETFs, and dovish signals from the Fed. A negative scenario would involve a new surge in oil prices, hawkish rhetoric from central banks, increased outflows from ETFs, and escalation in the Middle East.
Thus, June could be a test of resilience for the cryptocurrency market. Bitcoin remains the main indicator of institutional demand, Ethereum serves as an indicator of risk in altcoins, and key external factors will include interest rates, inflation, oil, geopolitics, and regulation in Europe.



