
According to Fixygen, U.S.-based PNC Bank has announced the launch of a service for accepting payments in the USDC stablecoin for corporate and institutional clients as part of an expanded partnership with the cryptocurrency platform Coinbase. The new solution provides for the automatic conversion of digital dollars into regular U.S. dollars, with the funds subsequently credited to clients’ bank accounts, according to an official PNC press release dated November 9, 2026.
The service uses Coinbase Payment APIs and operates with the USDC stablecoin, which is backed by the U.S. dollar. Initially, transactions are processed via the Ethereum blockchain.
Corporate clients participating in the program can receive transfers in USDC, which are automatically converted to U.S. dollars at a 1:1 ratio and credited to a designated deposit account at PNC Bank.
Thus, the payment recipient can enjoy the benefits of blockchain transfers without having to manage cryptocurrency assets on their own after the funds are received.
In the initial phase, the service is being offered to a limited group of corporate and institutional clients as part of a pilot program.
PNC Bank expects that the new technology will enable businesses to receive funds more quickly and improve the efficiency of cross-border payments.
One of the potential advantages of stablecoins is the ability to transfer digital assets via blockchain without using the traditional chain of correspondent banks at each stage of the transfer.
However, the speed of final settlement, transaction costs, and service availability depend on the specific payment infrastructure, banking compliance requirements, and service terms.
Tom Lang, Head of Product and Operations for PNC Bank’s Treasury Division, noted that corporate clients are constantly looking for new ways to settle payments with customers, suppliers, and business partners.
According to him, the launch of the service will allow the bank to explore the practical benefits of stablecoins and determine which technological capabilities are most in demand among corporate clients.
Coinbase views the expansion of its partnership with PNC as an example of the integration of the traditional banking system with digital asset infrastructure.
Alec Lovett, Head of Infrastructure Products at Coinbase, emphasized that stablecoins enable companies to make payments faster, more efficiently, and on an international scale.
The new project is a continuation of the partnership that the companies first announced in July 2025.
Initially, the collaboration involved using Coinbase’s institutional technology platform to provide bank customers with access to cryptocurrency transactions.
Now, the partners are expanding their collaboration into the realm of corporate payments, gradually integrating digital assets into traditional financial services.
PNC Bank is one of the major U.S. banks providing corporate lending, cash management, investment services, and other financial operations.
Coinbase, in turn, is developing infrastructure for storing digital assets, trading cryptocurrencies, and facilitating payments using blockchain technology.
The launch of this new service reflects one of the most notable trends in the cryptocurrency market in 2026—the shift from the predominantly investment-oriented use of digital assets to their practical application in financial transactions.
Stablecoins, whose value is pegged to traditional currencies, are increasingly being viewed as a technological tool for international trade, corporate payments, and liquidity management.
Of particular interest to businesses are solutions in which the use of blockchain does not require a complete transition to a cryptocurrency-based financial infrastructure.
PNC Bank’s model allows a company to receive a payment in a digital asset while continuing to manage funds through a traditional bank account.
This approach potentially lowers technological barriers for corporate clients who are interested in speeding up settlements but are not ready to store stablecoins or manage cryptocurrency wallets on their own.
At the same time, the use of digital payment instruments has a number of limitations. Banks must still comply with requirements regarding anti-money laundering, customer identification, sanctions compliance, and operational risk management.
In addition, stablecoins may pose additional risks related to the issuer of the digital asset, the functioning of the blockchain network, and the ability to convert tokens into traditional currency.
The expanded use of USDC in corporate banking services could become an additional driver for the development of the dollar-pegged stablecoin market.
Unlike speculative transactions involving Bitcoin and other cryptocurrencies, corporate payments generate demand for digital assets linked to real economic activity.
As such services develop, banks may become key players in the digital payments infrastructure, combining traditional financial instruments with the capabilities of blockchain.
However, it is still too early to assess the commercial results of PNC’s initiative. The bank has not disclosed the expected transaction volumes, the number of participating companies, or the timeline for a potential expansion of the program.
The project’s further development will depend on corporate client interest, the economic efficiency of transactions, and compliance with regulatory requirements.
Source: official PNC Bank press release dated November 9, 2026.
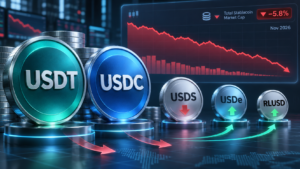
The total market capitalization of stablecoins as of November 9, 2026, stood at approximately $290.8 billion, down 1.6% over the past seven days and 4.2% over the past month. This is according to data from the DefiLlama analytics platform. Tether’s USDT remains the largest stablecoin, with a market capitalization of approximately $176.8 billion, according to the Experts Club information and analytics center.
Its share of the sector’s total capitalization reaches 60.8%, giving Tether a dominant position in the market for digital assets pegged to the value of traditional currencies.
USD Coin (USDC) ranks second, with a market capitalization of approximately $70.5 billion.
Thus, the two largest stablecoins account for approximately $247.3 billion, or more than 85% of the total market.
Over the past seven days, USDT’s market capitalization declined by approximately 1.3%, while USDC’s fell by 1.5%.
Sky Dollar (USDS) demonstrated a more significant decline, with its market capitalization falling by almost 15% over the week to $5.43 billion.
At the same time, certain digital assets demonstrated the opposite trend.
For example, the market capitalization of Ethena USDe increased by approximately 9.7% over seven days to $4.97 billion.
Growth was also recorded for Ripple USD (RLUSD), whose market capitalization reached approximately $2.69 billion, increasing by more than 11% over the week.
These dynamics indicate a redistribution of liquidity among individual stablecoins against the backdrop of an overall market contraction.
Stablecoins are used by cryptocurrency exchanges and investors for settlements, liquidity storage, facilitating trading operations, and cross-border transfers.
Digital assets pegged to the US dollar are the most widespread. Depending on the issuance model, they may be backed by cash, short-term government bonds, and other reserve assets.
A decline in the total market capitalization of stablecoins may indicate a reduction in the amount of digital dollars in circulation and a decrease in available liquidity in certain segments of the cryptocurrency market.
However, a change in market capitalization does not necessarily mean an equivalent withdrawal of funds by investors. The figures are also influenced by the issuance and redemption of tokens, fluctuations in the value of collateral, and changes in market structure.
In recent weeks, the contraction of the stablecoin segment has coincided with capital outflows from cryptocurrency ETFs and declines in the prices of Bitcoin and Ethereum.
At the same time, stablecoins continue to play an important role in the digital finance infrastructure, facilitating settlements between cryptocurrency platforms and the traditional financial system.
According to Fixygen, the European Securities and Markets Authority (ESMA) is requiring cryptocurrency companies authorized under the MiCA regulation to cease providing services to clients in the European Union related to stablecoins that do not comply with European regulatory requirements.
National supervisory authorities must require the resolution of any identified residual positions by approximately January 8, 2027.
ESMA’s position applies not only to exchange trading but also to the exchange of cryptoassets, the execution of client orders, advisory services, transfers, portfolio management, and the custody of digital assets.
The regulator emphasizes that authorized cryptocurrency service providers must not facilitate new purchases or increases in positions in stablecoins that do not comply with MiCA.
At the same time, during the transition period, certain transactions necessary for the sale, conversion, withdrawal, or secure storage of previously acquired assets are permitted.
Such services must be limited in scope, carried out within a specified timeframe, and subject to oversight by national regulators.
The document primarily concerns asset-backed tokens and electronic money tokens that do not meet the requirements of European regulations.
MiCA establishes specific rules for stablecoin issuers, particularly regarding asset reserves, disclosure, risk management, and the protection of token holders.
The conclusion of the EU-wide transition period for cryptocurrency service providers on July 1, 2026, marked an important milestone in the formation of a single regulated market for digital assets in the EU.
For international cryptocurrency exchanges, the new requirements mean they must adapt the range of available trading instruments, payment services, and asset custody operations for European clients.
For stablecoin issuers, this heightens the economic importance of MiCA compliance, as the ability to access clients through regulated European platforms increasingly depends on the legal status of tokens.
At the same time, ESMA has not announced a blanket ban on the use of all dollar-pegged stablecoins. The restrictions apply to specific assets and services that do not meet regulatory requirements.
The further implementation of MiCA may contribute to a redistribution of demand among issuers and strengthen the positions of companies that have obtained the necessary authorizations to operate in the European market.
CRYPTO EXCHANGE, EUROPEAN UNION, MiCA, REGULATION, stablecoin
Circle Internet Group, a U.S. fintech company and issuer of the USDC stablecoin, intends to expand its operations into approximately 40 emerging markets, banking on growing demand for digital payments and dollar-pegged stablecoins, according to Fixygen.
As Circle Chairman and CEO Jeremy Allaire told Reuters on October 16, 2026, the company views Southeast Asia, Latin America, Africa, and the Middle East as priority regions for international expansion.
According to him, the blockchain industry is transitioning from the initial stage of technology adoption to widespread commercial application. The main sources of demand are cross-border payments, international trade, corporate settlements, and financial services for consumers.
To strengthen its position in new markets, Circle previously entered into an agreement to acquire the Singapore-based payment company Tazapay for approximately $400 million. The deal, announced on September 8, provides access to an international payments infrastructure covering more than 100 markets and over 60 banking and fintech partners.
According to Circle, Tazapay’s annual payment volume, based on current growth rates, exceeds $25 billion, with about 60% of transactions already involving stablecoins.
The acquisition is expected to close in 2027, following the receipt of the necessary regulatory approvals.
In addition, on September 22, Circle announced an expansion of its partnership with the cryptocurrency exchange Binance, which invested $100 million in the company. The parties signed a new five-year agreement to expand the adoption of USDC, primarily in developing countries.
According to Reuters, as of the end of the second quarter of 2026, the amount of USDC in circulation had grown by 19% year-over-year, reaching $73.3 billion.
Circle controls approximately one-quarter of the global stablecoin market, trailing its main competitor, Tether, which holds a market share of about 60%.
The company is also developing its own blockchain infrastructure, Arc, designed for corporate settlements, the tokenization of financial assets, and international payments.
Financial institutions participating in the development and use of the Arc infrastructure include BlackRock, Visa, and Standard Chartered.
The expansion of the stablecoin market is supported by the gradual development of a regulatory framework. In the U.S., the GENIUS Act has been passed, regulating the issuance of payment stablecoins. Its main provisions are set to take effect in 2027.
At the same time, competition is growing from traditional banks, which are developing their own digital payment instruments and tokenized deposit infrastructure.
According to market participants, the expansion of stablecoin use could significantly change the structure of international payments by reducing transaction times and decreasing reliance on traditional correspondent banking networks.
Circle Internet Group is an American publicly traded fintech company founded in 2013. It specializes in developing blockchain-based payment infrastructure and issuing the digital currencies USDC and EURC. The company’s shares are listed on the New York Stock Exchange under the ticker symbol CRCL.
According to Fixygen, the cryptocurrency market is gradually expanding far beyond Bitcoin and traditional digital currencies. One of the most notable trends of 2026 is the rapid development of stablecoins and tokenized traditional assets, according to CoinDesk Data.
In September, the market capitalization of stablecoins rose to $313 billion. Trading volume for stablecoin pairs on centralized crypto exchanges increased by nearly 25% and exceeded $1 trillion for the first time since March.
Tether’s USDT remains the largest stablecoin, with a market capitalization of about $184 billion and a market share of approximately 59%. USDC ranks second with approximately $74 billion.
Stablecoins are gradually evolving from a crypto-trading tool into a standalone global payment infrastructure. They are used for international transfers, business settlements, storing dollar-denominated savings, and moving capital between various financial platforms.
The market for the tokenization of traditional assets is growing even faster. The value of tokenized stocks reached a record $4.87 billion at the end of September, while their trading volume directly on the blockchain rose to $15.6 billion over the month.
Overall, trading volume for tokenized stocks reached approximately $44.9 billion in the third quarter, an almost sevenfold increase compared to the second quarter.
Robinhood became the largest platform in September, accounting for about 42% of the total trading volume of tokenized stocks. The volume of transactions on its platform grew more than fivefold over the month—to $6.57 billion.
In addition to stocks, bonds, money-market funds, private loans, and commodity assets are gradually moving onto blockchains. The volume of tokenized bonds and money-market funds is estimated at approximately $17.3 billion, private loans at $5.6 billion, and commodity assets at over $6.4 billion.
According to an estimate by Experts Club, it is this segment of the digital market that may have more long-term significance than yet another growth cycle for individual cryptocurrencies.
While Bitcoin remains primarily a digital investment asset, stablecoins and tokenization are beginning to compete directly with bank transfers, depositories, brokers, and traditional stock market infrastructure.
In fact, a parallel financial system is gradually taking shape, in which dollars, stocks, bonds, and other assets can be traded on the blockchain around the clock, bypassing the traditional settlement cycle that takes several business days.
According to Fixygen, the widespread adoption of stablecoins could change not only the payments market but also the way central banks’ monetary policy operates, warned Petra Chudin, a member of the Governing Board of the Swiss National Bank (SNB).
The SNB representative outlined her position on new forms of money on September 30 at the KOF Prognosetagung 2026 in Zurich.
One of the main risks is linked to a potential shift of funds from traditional bank deposits to stablecoins.
If individuals and companies begin transferring large amounts of money from bank accounts into digital tokens, commercial banks could lose part of their relatively cheap source of funding.
As a result, resources for lending to the economy will decrease, and banks will have to seek more expensive market-based financing.
But for central banks, the problem runs even deeper. By changing the interest rate, the central bank influences the cost of money within the banking system. Banks then adjust their deposit and loan rates accordingly, which affects household spending, corporate investment, and, ultimately, inflation.
The greater the proportion of money that moves outside the traditional banking system into stablecoins, the weaker this channel for transmitting monetary policy could potentially become.
Chudin also highlighted the fundamental issue of the unity of money. Under normal conditions, one Swiss franc in a bank account is equivalent to one franc in cash or central bank money.
A stablecoin is an obligation of a private issuer and does not necessarily have the same characteristics as central bank money.
This is precisely why the widespread adoption of various private digital currencies could potentially lead to a more fragmented monetary system. At the same time, the SNB does not reject the technology of digital money itself.
Switzerland is one of the most active European markets for institutional tokenization. The central bank is already experimenting with settlements using central bank digital currency for transactions involving tokenized assets.
Thus, the question for regulators is no longer whether new forms of money will emerge, but rather which digital form of money will become the primary unit of account—stablecoins issued by private companies, tokenized bank deposits, or central bank digital currencies.
This rivalry is becoming one of the most prominent structural trends in the financial market of 2026.
In the United Kingdom alone, Barclays, HSBC, Lloyds Banking Group, and NatWest conducted the first interbank transactions involving tokenized deposits in September.
At the same time, European banks are developing their own stablecoin projects, while global financial groups are experimenting with round-the-clock settlements on the blockchain.
As a result, the market is gradually moving beyond the former “cryptocurrency versus banks” dichotomy. Banks and central banks are beginning to build their own digital infrastructure that competes with the functions currently performed by USDT, USDC, and other stablecoins.



