
Prices for construction work in Ukraine in September 2026 increased by 27.1% compared to September 2025, while the physical volume of construction over the first nine months of the year decreased by 5.1%, according to the Experts Club analytical center, citing data released by the State Statistics Service on November 9.
On a month-over-month basis, the cost of construction rose by 1.5%.
The sharpest price increase was seen in transportation infrastructure construction—up 2.4% compared to August. Prices for construction of residential buildings rose by 1.7%, and for non-residential buildings—by 1.6%.
According to Experts Club’s assessment, a significant rise in construction costs coupled with a decline in actual activity creates additional risks for the implementation of investment projects.
Rising costs may force developers to revise their budgets, postpone project completion dates, and reduce the volume of new construction.
This factor is particularly important for infrastructure restoration programs, where the amount of available funding is often determined in advance.
At the same time, the construction work price index does not mean that all materials have become more expensive at the same rate. Price trends for cement, metal, concrete, wood, glass, and other products may vary significantly.
Source: Experts Club study
According to Experts.news, accelerating consumer inflation in the U.S. and growing expectations of interest rate hikes by the Federal Reserve (Fed) were among the main factors behind the sell-off in the global cryptocurrency market in November 2026. Amid a strengthening U.S. dollar and declining investor interest in risky assets, Bitcoin fell below $70,000 on November 13, while Ethereum dropped to approximately $1,950.
According to data from the U.S. Department of Labor released on November 10, 2026, the Consumer Price Index (CPI) rose 0.4% in October compared to the previous month, following a 0.6% increase in September. Core inflation, which excludes the most volatile food and energy prices, stood at 0.3% on a monthly basis, remaining at the same level as the previous two months.
Meanwhile, food prices rose by 0.5% in October, energy prices by 0.7%, and housing prices by 0.3%. The latter category accounted for more than 30% of the total monthly increase in consumer prices.
Despite the slowdown in overall monthly price growth compared to September, inflation remains elevated, limiting the Fed’s ability to ease monetary policy.
At its October 28 meeting, the Federal Open Market Committee (FOMC) kept the target range for the federal funds rate at 3.75–4%. The decision was approved by a vote of ten to two. Two committee members voted to raise the rate by 0.25 percentage points.
In its official statement, the Fed noted the sustained growth of the U.S. economy, labor market stability, and persistent inflationary pressures. The central bank reaffirmed its intention to bring inflation back to its 2% target.
Following the release of inflation data, investors began to more actively factor in the possibility of a rate hike at the next Fed meeting, scheduled for December 9. According to CoinDesk data from November 10, futures market participants were forecasting a 0.25 percentage point rate hike, bringing the range to 4–4.25%. At the same time, some Fed officials acknowledged the need for more significant policy tightening should high inflationary pressures persist.
Interest rate hikes typically increase the attractiveness of dollar-denominated deposits and debt instruments, while simultaneously raising the cost of borrowed capital. For the cryptocurrency market, this could mean reduced liquidity and a decline in investors’ willingness to open positions in high-risk assets. Additional pressure on digital assets was caused by the deteriorating situation in the technology sector of the U.S. stock market. Investors were reassessing the valuations of the largest artificial intelligence-related companies amid concerns about massive capital expenditures and the prospects for a return on investment.
The decline in tech stocks was accompanied by a strengthening of the U.S. dollar and a reduction in cryptocurrency positions. According to data from The Block on November 13, Bitcoin fell to approximately $68,400 during trading, losing about 7% over the course of the day. Ethereum dropped 6% to $1,920, while BNB fell 6.3%. The price of XRP declined by approximately 3.5%.
The massive sell-off triggered a wave of forced liquidations in the cryptocurrency market. According to CoinGlass data cited by The Block, the volume of liquidations reached $1.47 billion over a 24-hour period, of which $1.31 billion came from long positions opened in anticipation of rising prices.
In total, liquidations affected more than 175,000 traders. Over a single four-hour period, the volume of forced liquidations reached $798 million.
Analysts attribute the accelerated decline to Bitcoin breaking through several key price levels. After falling below $72,000, the market faced increased selling pressure, and breaking through the $70,000 mark led to additional liquidations of leveraged positions.
According to a November 13 report by The Wall Street Journal, Bitcoin was heading toward its sixth consecutive week of decline, having lost more than 21% of its value relative to its late-September highs. Ethereum fell to its lowest levels in about three months.
The outlook for the Fed’s December decision will be a key factor in the future dynamics of cryptocurrencies. If inflation continues to exceed expectations, the U.S. regulator may have additional grounds to raise interest rates. In that case, pressure on Bitcoin, Ethereum, and other digital assets could persist, especially if capital outflows from U.S. spot cryptocurrency ETFs continue.
An alternative scenario envisages market stabilization should inflation slow and expectations of further monetary tightening ease. This could support demand for risky financial instruments and contribute to a recovery in cryptocurrency prices.
The next meeting of the Federal Open Market Committee will take place on December 8–9, 2026. Until then, investors will closely monitor new data on the state of the U.S. economy, inflation, and employment.
The U.S. Federal Reserve System serves as the country’s central bank and sets the key parameters of monetary policy. Its decisions on interest rates influence global financial markets, the cost of borrowing, the dollar exchange rate, and the investment appeal of various asset classes, including cryptocurrencies.
Sources: U.S. Department of Labor, inflation report dated November 10, 2026, U.S. Federal Reserve, decision dated October 28, 2026, The Block, data on cryptocurrency sell-offs dated November 13, 2026.
BITCOIN, CRYPTOCURRENCY, DOLLAR, Federal Reserve, INFLATION, INVESTMENTS
Consumer price growth in Ukraine slowed to 1.8% in October 2026, following an acceleration to 2.1% in September from 0.1% in August and 0.3% in July, the State Statistics Service (Gosstat) reported on Tuesday.
The statistics agency noted that in October 2025, prices rose by 0.9%; therefore, on a year-over-year basis, inflation as of the end of October 2026 rose to 11.0% from 10.0% at the end of September and 8.1% at the end of August.
It is noted that in October 2026, core inflation also fell to 1.4% compared to 2.0% in September. However, given that it stood at 0.6% in October 2025, year-over-year core inflation rose to 9.7% from 8.8% as of the end of September.
As previously reported, the National Bank of Ukraine raised its inflation forecast for this year from 10.0% to 12.5% in late October, and for next year from 6.9% to 7.3%. According to the NBU’s estimates, the impact of shelling alone will add about 0.7 percentage points to annual inflation. Other important factors that will affect price dynamics include the impact of rising fuel prices and the expansion of fiscal stimulus measures.
Inflation in Ukraine surged to 26.6% during the first year of full-scale Russian aggression, after which it fell to 5.1% in 2023. The following year, it rose again to 12%, but by 2025, it had been brought down to 8%, partly due to the National Bank’s fairly tight monetary policy.
Source: https://stat.gov.ua/uk/publications/indeksy-tsin-u-zhovtni-2026-roku-ekspres-vypusk
According to Interfax-Ukraine, the Board of the National Bank of Ukraine (NBU) raised the discount rate by 0.5 percentage points (p.p.)—to 16.5% per annum—effective October 30, due to a significant increase in price pressures and a deterioration in inflation expectations.
“The NBU is prepared to respond flexibly to further changes in the risk landscape, taking into account both the persistence of price pressures and the likely consequences of a slowdown in economic activity,” the regulator noted in a press release on Thursday.
The National Bank’s current forecast calls for keeping the policy rate at 16.5% until the second quarter of 2027. At the same time, the regulator will adjust monetary policy depending on actual developments, particularly the impact of Russian attacks on inflation and economic activity, the statement noted.
According to the updated forecast path, the rate is expected to decline in the second quarter to an average of 16.2%, up from 15.3% in the previous forecast, and is now projected to reach 14.6% by the fourth quarter of 2027, compared to 14.0% in the July forecast.
In September, headline inflation accelerated to 10% year-over-year, while core inflation rose to 8.8%, and this trend continued in October. The main factors were rising fuel prices due to the war in the Middle East and intensified Russian attacks on warehouse and logistics infrastructure, the NBU noted.
The regulator raised its inflation forecast for the end of 2026 to 12.5% from 10%, and for 2027 to 7.3% from 6.9%. The regulator continues to expect inflation to return to the 5% target in 2028.
According to the updated inflation forecast curve, inflation is expected to decline as early as the first quarter of this year—to 11.7% from 9.1% in the July estimate—and in the second quarter to 11.5% from 8.7%.
According to the National Bank, the previous tightening of monetary policy has already bolstered the attractiveness of hryvnia-denominated assets: even large banks have begun raising interest rates on hryvnia deposits. The current decision should also limit pressure on the foreign exchange market, which has intensified due to a decline in exports and worsening expectations amid Russian attacks.
The results of the Monetary Policy Committee’s discussion, which preceded the decision to raise the rate to 16.5% per annum, will be released on November 9.
The next meeting of the NBU’s Board on monetary policy will take place on December 17, 2026.
As previously reported, after lowering the discount rate to 15% at the end of January 2026, the NBU kept it at that level for three consecutive meetings, and since July has raised it three times in a row by 0.5 percentage points.
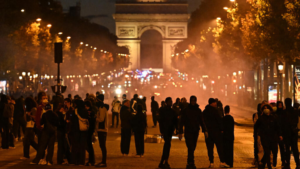
On October 17, 2026, large-scale nationwide protests took place in France against the rising cost of living, increasing fuel prices, and cuts in funding for public services. According to the country’s Ministry of the Interior, approximately 550,000 people took part in the demonstrations, while organizers estimate the number of participants at 800,000, Reuters and the French newspaper Le Monde report.
A total of 110 demonstrations took place across the country. In Paris alone, according to Interior Minister Laurent Nuñez, approximately 110,000 people took to the streets. The protests also spread to Marseille, Lyon, Lille, Bordeaux, Toulouse, and other major cities.
The participants’ main demands included higher wages and pensions, measures to curb food and energy prices, increased funding for education and healthcare, and the preservation of social guarantees.
Trade unions, student organizations, representatives of farmers’ associations, transport sector workers, and activists from the “yellow vests” movement, which emerged in France in 2018 due to rising fuel prices, joined the demonstrations.
The current wave of protests began in September with student demonstrations against teacher shortages, the poor condition of educational institutions, and insufficient government funding for education. Subsequently, the demands expanded to include issues of purchasing power, social inequality, and the government’s economic policy.
Despite the predominantly peaceful nature of the demonstrations, clashes with police, vehicle arson, vandalism and looting of shops, and attacks on administrative buildings occurred in several cities.
In Paris, the most tense situation was observed near Place de la République, where some groups of rioters threw stones and pyrotechnic devices at police officers. Law enforcement officers used tear gas and water cannons. There were also reports of shops being looted and bank branches being damaged.
In Marseille, a group of protesters entered the city council building; in Lyon, a tourist office was set on fire; and in Limoges, a fire damaged the town hall building. Incidents involving damage to administrative buildings were also recorded in other cities.
According to preliminary data from the French Ministry of the Interior, police detained approximately 400 people. Authorities reported injuries among law enforcement officers and civilians. A separate investigation was launched following the serious injury of a minor participating in a protest in Saint-Étienne.
French President Emmanuel Macron condemned the violence and stated the need to hold those responsible accountable. Prime Minister Sébastien Lecornu emphasized that the government would not allow the unrest to be used to exert pressure on state institutions.
At the same time, protest organizers emphasize that the overwhelming majority of participants demonstrated peacefully and demanded a revision of the state’s socioeconomic policy.
The mass demonstrations are taking place against the backdrop of a difficult situation in France’s public finances. According to the draft state budget for 2027 presented on October 1, the government plans to reduce the deficit from a projected 5.4% of GDP in 2026 to 5% of GDP in 2027.
To achieve this goal, overall fiscal consolidation measures totaling €54 billion are envisaged, including €43 billion within the framework of the draft laws on the state budget and the financing of the social security system.
At the same time, the government forecasts a slowdown in France’s economic growth to 0.5% in 2026, with a possible acceleration to 1% in 2027. Public debt servicing costs could rise from €79.2 billion in 2026 to €91.2 billion the following year.
Trade unions fear that measures to limit public spending will increase the burden on households, primarily those with low and middle incomes.
The protests have already caused disruptions to urban public transport, the temporary closure of certain Paris Metro stations, and damage to commercial properties. A final assessment of the economic damage caused by the unrest has not yet been released.
The new wave of social discontent is increasing political tensions in France ahead of the 2027 presidential election and complicating discussions on fiscal policy. Further developments will depend, among other things, on negotiations between the government, trade unions, and representatives of the student movement.
France is the second-largest economy in the eurozone after Germany and one of Ukraine’s largest trade and economic partners in the European Union.
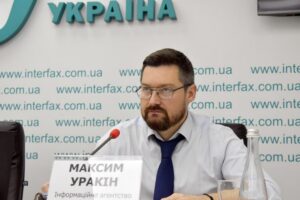
According to Interfax-Ukraine, Ukraine’s economy showed the first signs of emerging from a recession in the first half of 2026, however, the high foreign trade deficit, inflationary pressures, and the dependence of public finances on international aid remain key macroeconomic risks, according to the latest issue of “Economic Monitoring.”
As noted by Maksym Urakin, Ph.D. in Economics and founder of the Experts Club information and analytical center, after real GDP fell by 0.6% year-over-year in the first quarter, the economy returned to growth in April–June.
In the second quarter, Ukraine’s real GDP increased by 0.4% compared with the same period last year and by 0.3% compared with the previous quarter. At the same time, the National Bank’s forecast projected growth of the Ukrainian economy at only 1.3% for the full year of 2026.
“Positive factors in the first half of the year included the resumption of at least minimal GDP growth, the return of international reserves to above $50 billion, stability in the foreign exchange market, more consistent international financing, and the adaptability of Ukrainian businesses. The main risks remain the war, the state of the energy sector, high production costs, a labor shortage, weak commodity exports, and a growing trade imbalance. Ukraine has a significant supply of external liquidity, but it cannot replace domestic economic growth,” Urakin noted.
Consumer inflation slowed to 7.2% in June, while core inflation accelerated to 8.1%. The NBU’s discount rate remained at 15%.
At the same time, after four months of decline, Ukraine’s international reserves increased by 12.1% in June—to $51.27 billion. The NBU’s foreign exchange interventions remained substantial.
Foreign trade remains one of the main structural risks to the Ukrainian economy. From January through June 2026, merchandise imports totaled approximately $49.3 billion, while exports amounted to about $21 billion. Thus, the merchandise trade deficit reached approximately $28.3 billion.
Public finances also remain under significant strain. Revenues to the General Fund of the state budget for the first half of the year totaled nearly 1.9 trillion UAH, while expenditures amounted to approximately 2.23 trillion UAH.
Approximately 1.4 trillion UAH, or about 63% of all General Fund expenditures, was allocated to the security and defense sector. The volume of international grants totaled 569.6 billion hryvnia.
According to Urakin, one of the main objectives of economic policy should be to transform significant imports of equipment, international funding, and defense spending into a foundation for creating new domestic production capacity.
“The next phase of economic policy should consist not only of maintaining financial stability, but also of transforming imported equipment, international funds, and defense spending into new production assets. The foundation for long-term development should be energy self-sufficiency, the defense-industrial complex, agricultural processing, machine building, production localization, logistics, digital technologies, and exports of high-value-added products,” says the founder of Experts Club.
At the same time, the first half of the year revealed significant differences between the world’s largest economies and emerging markets.
The Chinese economy grew by 4.7% in the first six months of 2026, while India posted a growth rate of about 7.8% in April–June.
Turkey continued to combine economic growth with extremely high inflation. In the second quarter, its GDP increased by 2.3% year-over-year and by 1.1% compared to the previous quarter, while annual inflation in June remained near 32%.
Brazil showed more moderate growth: its GDP in the second quarter increased by 2% year-over-year and by 0.5% compared to the previous quarter. In the first half of the year, the country’s economy grew by 1.9%, and annual inflation in June slowed to 4.64%.
“Key emerging economies ended the first half of the year with very different growth patterns. China grew by 4.7%, but its second quarter was weaker than the first, and domestic consumption lags significantly behind industrial output and exports. India continues to grow by nearly 8%, driven by the size of its domestic market and investment. Turkey remains an example of how inflation exceeding 30% limits the quality of economic growth, while Brazil is showing more moderate growth with gradual control of inflation. For Ukraine, the main conclusion remains the same: long-term growth requires its own industrial, technological, and export base,” Urakin emphasized.
In his assessment, the first half of the year confirmed the viability of Ukraine’s macrofinancial stabilization model, but at the same time revealed its limitations.
“The return of GDP to modest growth and the replenishment of reserves are positive signs; however, the $28.3 billion merchandise trade deficit, high underlying inflationary pressures, and the budget’s dependence on external financing reveal the limits of this model. Only by developing its own production and export base will Ukraine be able to transition from an economy of wartime stabilization to a model of sustainable postwar growth,” concluded Maksym Urakin.
“Economic Monitoring” is a monthly analytical and statistical publication led by Maksym Urakin, Ph.D. in Economics. The publication analyzes the main macroeconomic indicators of Ukraine and the world’s leading economies, as well as trends in GDP, inflation, public finances, international reserves, foreign trade, and key risks to economic development.



