
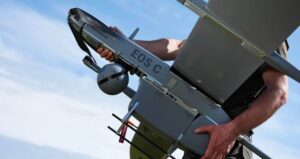
Estonian Defense Minister Hanno Pevkur stated that the republic provided Ukraine with military aid totaling over EUR50 million in 2026, of which over EUR40 million consisted of products from the Estonian defense industry.
“This year’s contribution of at least 0.28% of GDP and the growing share of Estonian defense products in our aid to Ukraine demonstrate the consistency of our support. Ukraine can count on both us and its other allies,” said Pevkur, as quoted by the ministry’s press service.
He noted that in 2023, the Estonian government set a goal of providing support to Ukraine at a level of at least 0.25% of GDP per year. In 2025, this aid reached 0.35% of GDP.
The bulk of Estonia’s military aid is provided in the form of products from Estonian companies. Part of the aid package for 2026 has already been delivered: Estonia has purchased drones and related equipment for Ukraine. Aid measures for 2027 will be announced shortly.
As part of the NATO PURL (Prioritized Ukraine Requirement List) initiative, products from the U.S. defense industry are also being procured for Ukraine. Estonia has contributed EUR 21 million to the initiative.
In total, since the start of the war in Ukraine in 2022, Estonia has provided over EUR 850 million in support to the country through various military aid initiatives, according to the Ministry of Defense.
The Norwegian government will propose to the Storting (parliament) to extend emergency aid to Ukraine in the amount of 85 billion Norwegian kroner (approximately $9.1 billion) into 2027 as well, the government’s press service reported.
“Norway will continue to support Ukraine’s defense efforts. Ukraine is facing a difficult winter. We are now sending a clear signal that Norway will continue to support Ukraine, both through civilian and military aid,” said Prime Minister Jonas Gar Støre.
As noted, the government’s proposal was conveyed to Ukrainian President Volodymyr Zelenskyy during a meeting between Stere and Zelenskyy in Kyiv on Sunday.
The Norwegian prime minister noted that supporting and rebuilding Ukraine is also important for European security. Norwegian support is provided through the Nansen Program for Ukraine and is directed toward both civilian and military purposes.
“The bulk of the funds will go toward military support, specifically purchases from the Ukrainian defense industry. The government will revisit the distinction between military and civilian services at a later date,” the press release states.
The Nansen Program for Ukraine is Norway’s long-term government program to support Ukraine, launched in February 2023 with broad cross-party support from the Norwegian parliament—the Storting. It initially allocated 75 billion NOK for 2023–2027, but the program was subsequently expanded and extended through 2030.
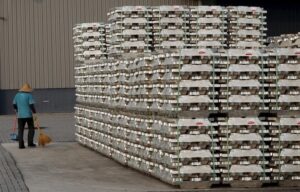
According to Experts Club, the price of zinc on the London Metal Exchange rose to its highest level in over four years amid shrinking available inventories and risks of production disruptions in the largest supplier countries.
At the close of trading on August 21, the metal’s price stood at approximately $3,820 per metric ton, up about 2% for the day. During the session, prices rose even higher, hitting a new high not seen since mid-2022.
Over the past month, zinc has risen in price by about 6.5%, and over the past year—by more than 36%, making it one of the fastest-rising base metals.
Physical market tightness remains the main driver of the rise. Zinc stocks in the LME system have fallen below 100,000 metric tons, and the spread between the spot price and three-month futures has widened significantly, indicating increased demand for available metal. According to the Shanghai Metals Market, LME stocks stood at about 94,400 metric tons on August 20.
Production issues are putting additional pressure on supply. Heavy rains and flooding in certain regions of China have created risks for mining and smelting operations. Adjustments to production volumes at one of the deposits in the country’s southwest could reduce August concentrate output by approximately 1,000 metric tons, while maintenance at one of the plants in Central China could cut refined zinc production by another 1,000–1,500 metric tons.
Major international companies are also reporting declines in production. Glencore’s own zinc production fell in the first half of the year, Boliden’s concentrate output declined compared to the previous quarter, and MMG reported a year-over-year decline in production in the second quarter.
Zinc is primarily used for galvanizing steel and protecting metal structures from corrosion, so demand for it is closely linked to construction, automotive manufacturing, and infrastructure investments. Renewable energy and new energy storage technologies are emerging as additional long-term drivers.
At the same time, high prices could stimulate a resumption of production and supply. Previously, the market had been under pressure for several years following the price peak in 2022, which led to the closure or mothballing of some of the less profitable facilities.
Experts Club previously published a ranking of the largest zinc producers based on data from the USGS and the International Lead and Zinc Study Group. At the end of 2024, China led the way with approximately 4 million metric tons, followed by Peru with 1.3 million metric tons and Australia with 1.1 million metric tons.
According to Experts Club, copper prices ended the last trading week on an uptrend: on August 21, three-month contracts on the London Metal Exchange (LME) traded at around $14,230 per metric ton, gaining approximately 1.4% for the day.
The market was supported by a weaker U.S. dollar and statements by Chinese authorities regarding their intention to increase the role of government spending in stimulating domestic demand. China remains the world’s largest consumer of copper, so expectations of additional government spending traditionally provide support for the industrial metal’s prices.
Volatility remained high throughout the week. On Monday, the price of copper rose to $14,396 per metric ton—a six-month high. The rise was primarily driven by concerns over limited supply of available metal outside the U.S.
However, the situation then stabilized somewhat thanks to copper deliveries to LME warehouses. The premium of spot copper over the three-month contract narrowed from $436 per metric ton on Monday to about $55 by Friday, indicating an easing of supply tightness for immediate delivery.
At the same time, the fundamental risks of a shortage have not completely disappeared. In mid-August, a brief squeeze occurred on the LME: large long positions proved to be comparable to available exchange stocks, leading to a sharp rise in the price of metal for immediate delivery. After that, additional copper from the U.S. and Asia began arriving at exchange warehouses.
Signals from China remain mixed. The Yangshan premium, which reflects Chinese buyers’ demand for imported copper, rose by approximately 7% by the end of the week—to $93 per metric ton. At the same time, copper inventories at the Shanghai Futures Exchange rose by 28% over the week.
In the longer term, the market remains in a pronounced uptrend. Indicative copper prices as of August 21 were approximately 47% higher than a year ago.
The growth in demand is driven by the expansion of power grids, the construction of data centers, and the development of electric vehicles, solar, and wind energy, while it is difficult to rapidly increase copper production due to the long lead times required to bring new deposits online.
Earlier, the Experts Club information and analytical center published a short video on the dynamics of global copper production from 1970 to 2024. According to the data presented, Chile remained the largest producer in 2024 with 5.3 million metric tons, followed by the Democratic Republic of the Congo with 3.3 million metric tons and Peru with 2.6 million metric tons.
Watch the Experts Club video on global copper production – https://youtube.com/shorts/_h8iU50z8C0?si=dDXmg9cHOYbbGUaX
https://www.experts.news/posts/svitovi-tsiny-na-mid-znovu-zrostayut
According to Fixygen, the cryptocurrency market ended the week of August 17–23 with a sharp rally: Bitcoin rose by approximately 23%, Ethereum by more than 30%, and a number of major altcoins showed even stronger gains. The main drivers were an influx of funds into U.S. spot cryptocurrency ETFs, a weaker dollar, shifts in the U.S. Treasury market, and positive regulatory signals from Washington.
As of August 23, Bitcoin was trading at approximately $77,200, compared to about $62,900 at the end of the previous week. On August 21, the price rose to $79,300, marking a three-month high. Thus, BTC posted its best weekly performance in more than two years.
Ethereum rose even faster. ETH climbed from approximately $1,880 to $2,460—an increase of more than 30%. On August 19 alone, the second-largest cryptocurrency by market capitalization gained about 17.5%, and on August 21, it rose another 8%.
The rally also spread to altcoins. XRP rose by about 40% or more over the course of the week, Solana by more than 20%, and Chainlink, Hyperliquid, Dogecoin, and a number of other major digital assets also showed significant gains. Thus, this time the growth was not limited to Bitcoin alone.
One of the main factors was a sharp reversal in inflows into U.S. cryptocurrency ETFs. Over the five trading sessions from August 17–21, spot Bitcoin and Ethereum ETFs in the U.S. attracted a combined total of about $2.6 billion, marking their best weekly performance since October 2025.
Bitcoin ETFs accounted for about $1.92 billion, while Ethereum ETFs accounted for about $697 million. Meanwhile, Bitcoin funds recorded net inflows for all five consecutive trading days. Bitcoin ETF trading volume for the week exceeded $22 billion, more than tripling the previous week’s figure.
The market received an additional boost on August 19 following the U.S. Treasury Department’s decision to increase the volume of long-term Treasury bond buybacks. This led to a decline in yields on some government securities and a weakening of the dollar, prompting investors to step up purchases of gold and Bitcoin as alternative assets.
According to Reuters, by the end of the week, the dollar had fallen to a three-month low against the euro, which also created a favorable backdrop for cryptocurrencies. During this period, some investors viewed Bitcoin, alongside gold, as part of the so-called “debasement trade”—betting on assets with limited supply amid concerns over U.S. debt and fiscal policy.
The closing of large short positions was also a key factor. Bitcoin’s rapid surge past the $65,000, $70,000, and $75,000 levels forced traders who had bet on a further decline to close their positions en masse. According to various estimates, during the most active phase of the rally, more than $4 billion in short positions were liquidated in the crypto market, which further accelerated the rally.
The regulatory backdrop in the U.S. also proved positive for the sector. On August 18, the U.S. Securities and Exchange Commission (SEC) proposed a new specialized framework for certain cryptoasset transactions and offerings. The SEC notes that the goal of the changes is to adapt the rules to the unique characteristics of digital assets, facilitate capital raising, and at the same time maintain investor protection requirements.
Thus, several favorable factors converged on the market simultaneously over the course of a single week: strong institutional demand driven by ETFs, a weaker dollar, improved liquidity expectations, and a reduction in regulatory uncertainty.
At the same time, the weekend showed that after such rapid growth, investors began to partially lock in profits. After peaking above $79,000, Bitcoin returned to the $76,000–$77,000 range, while Ethereum, after surpassing $2,500, traded around $2,400–$2,500. For now, this looks more like consolidation following a sharp rally than a full-fledged trend reversal.
U.S. monetary policy will be a key test for cryptocurrencies as early as next week. An economic symposium will take place in Jackson Hole on August 27–29, and Federal Reserve Chair Kevin Warsh is scheduled to speak on August 28. The market will be closely watching his assessment of inflation, interest rates, and the situation in the bond market.
For Bitcoin, the immediate key resistance zone remains the $79,000–$80,000 range. Holding above this level could pave the way for a continued recovery following the drop from record highs in 2025. At the same time, after a gain of more than 20% in a single week, the risk of a short-term correction remains high.
For Ethereum, the key will be holding the $2,300–2,400 range and continued inflows into spot ETH ETFs. It is the resilience of institutional demand following the best week for ETFs in 2026 that will determine whether the current rally will evolve into a longer-term uptrend.
Fixygen will continue to monitor inflows into cryptocurrency ETFs, Fed policy, the dollar’s performance, and Bitcoin’s behavior near the $80,000 level, all of which could determine the market’s direction in late August.
As of July 2026, sole proprietors registered in Kyiv owed the state 2.61 billion UAH in taxes, the highest figure among Ukraine’s regions, according to data from the State Tax Service analyzed by Opendatabot.
The capital accounts for about 16% of the country’s total tax arrears owed by sole proprietors, which amount to 16.6 billion hryvnias.
In second place is the Odesa region, with entrepreneurs owing about 1.6 billion hryvnias; in third place is the Kyiv region, with 1.37 billion hryvnias.
Collectively, Kyiv, Odesa, and Kyiv regions account for approximately one-third of all tax debts owed by Ukrainian sole proprietors.
At the same time, Kyiv region leads in the number of debtors, with 182,640 sole proprietors owing tax debt. Over the past year, their number has increased by approximately 1.5 times.
The Odesa Oblast has 119,470 individual entrepreneurs in debt, while the Kharkiv Oblast has 101,500.
In total, approximately 1.5 million individual entrepreneurs in Ukraine owe taxes, amounting to a total of 16.6 billion hryvnias.
Source: Opendatabot, data from the State Tax Service of Ukraine as of July 2026.



