The office real estate market of Kyiv and Ukraine’s largest cities by May 2026 is demonstrating cautious stabilization after several years of shocks caused by the pandemic, the full-scale war, business relocation and the transition of some companies to a hybrid work format. The main demand factors remain building safety, completed renovation, autonomous infrastructure, the availability of shelters and the ability to move in quickly without significant capital expenditures.
Kyiv still remains the country’s largest office market. According to InVenture estimates, the total competitive supply of office real estate in Kyiv in 2025 decreased to 2.10 million sq. m, while the vacancy rate fell to 18.5%. The annual volume of gross take-up amounted to about 160 thousand sq. m, which is 26% more than a year earlier. At the same time, about 40% of take-up was related not to the organic expansion of business, but to the forced relocation of companies from damaged properties.
According to the Confederation of Builders of Ukraine, citing a CBRE Ukraine presentation, in the first half of 2025 demand for offices in Kyiv grew by 16%, to 82 thousand sq. m, while supply decreased by 3%, to 2.1 million sq. m, due to damage to office buildings. Vacancy in the market stood at about 21%, while 20% of demand was formed by tenants forced to relocate from properties affected by strikes.

“The office market in Kyiv can no longer be assessed according to pre-war logic. Today, a tenant chooses not simply an address or a building class, but the ability of a property to ensure business continuity. A shelter, generators, engineering systems, the safety of the district and the readiness of the premises for quick move-in have become parameters as important as the rental rate,” says the founder of the Experts Club analytical center, Candidate of Economic Sciences Maksym Urakin.
Rental rates in Kyiv remain relatively stable, but the market retains pronounced differentiation. According to InVenture, effective rates for class A offices without renovation at the end of 2025 amounted to $14-18 per sq. m per month excluding VAT and operating expenses, while for offices with renovation they amounted to $19-25 per sq. m. Asking rates for class A were in the range of $16-27 per sq. m, and for class B — $8-18 per sq. m.
In 2026, Kyiv’s office market remains a tenant’s market: property owners are forced to offer flexible terms, divide large areas into smaller blocks, invest in ready-made finishing and increase the autonomy of buildings. At the same time, the best class A and B+ properties with shelters, stable power supply and high-quality operation are holding demand better than outdated buildings and premises without renovation.
CBRE Ukraine senior office real estate consultant Anastasiia Kachan noted that in Kyiv the connection between the rate and the specific location of a business center has strengthened: now not only proximity to the metro matters, but also the location relative to infrastructure or military facilities. According to her, each business center can effectively operate outside the typical rules of its submarket or district.
IT companies remain the key tenants in Kyiv, but the structure of demand has become broader. Activity is also being formed by the defense sector, medical companies, professional services, consulting, logistics, representative offices of international organizations and part of the business related to reconstruction. According to CBU/CBRE Ukraine, in 2025 demand from the military sector increased noticeably, and the market began adapting offers to such needs.
“The office has ceased to be a place of daily presence for all employees, but it has not lost its significance for management, communication and corporate culture. Companies are optimizing space, but they are not abandoning a quality office. Therefore, demand is shifting from large monofunctional spaces to more flexible, safe and technological formats,” Experts Club notes.
Development activity remains minimal. In 2025, not a single new business center was commissioned in Kyiv, and by the end of 2026, according to InVenture’s estimate, about 27 thousand sq. m may enter the market, but commissioning deadlines may be postponed due to security risks, limited financing and a weak level of pre-leasing.
The situation in Ukraine’s major cities is heterogeneous. Lviv remains one of the most active regional office markets thanks to business relocation, the presence of the IT sector, proximity to the EU border and a relatively higher level of safety compared with the eastern and southern regions. According to Forbes Ukraine, by the end of 2025 vacancy in Lviv business centers decreased to 25%, while rental rates remained at $7-15 per sq. m.
In 2026, the Lviv market can be considered the second most important after Kyiv in terms of office demand, but its scale is limited. For tenants, ready-made premises, transport accessibility, energy resilience and the possibility of accommodating small or medium-sized teams are important. Large deals remain rare, while some companies prefer hybrid formats or coworking spaces.
Dnipro retains the role of an industrial, logistics and service center, but the city’s office market remains more local and less institutionalized than in Kyiv or Lviv. Demand is formed by regional companies, service businesses, retail operators, logistics, medical services and part of production structures. Due to proximity to an area of increased risks, tenants are especially sensitive to the safety, cost and autonomy of premises.
Odesa remains an important southern business center, but the city’s office market is strongly dependent on the overall security situation, port and logistics activity, tourism, trade and service business. The market includes both classic offices in central districts and premises in new multifunctional complexes. Demand in 2026 remains selective: tenants choose ready-made small premises, while large corporate deals are limited.
Kharkiv remains the most difficult of the large office markets due to the high level of security risks and proximity to the frontline zone. A significant part of business operates in a reduced, distributed or remote format. Nevertheless, the market has not stopped completely: demand remains for small offices, service premises, spaces for local business and properties with minimal operating costs.
“In regional cities, office real estate has ceased to be a single segment. Lviv operates as a market of relocation and IT, Dnipro as a market of industrial and service business, Odesa as a southern trade and logistics hub, and Kharkiv as a market of survival and adaptation. Therefore, comparing them only by rental rate is no longer correct: it is more important to look at safety, the tenant profile and the resilience of the local economy,” Maksym Urakin believes.
A common trend for all major cities has been the reassessment of office space. Companies more often choose smaller areas, completed renovation, flexible lease terms and buildings where the owner assumes part of the capital expenditures. Premises without renovation and large blocks in outdated properties remain less liquid, since tenants are not ready to invest in expensive fit-out amid high uncertainty.
Another factor is autonomy. After energy crises and attacks on infrastructure, offices with generators, stable internet, backup systems, shelters and high-quality management gained a competitive advantage. In some cases, such characteristics allow properties to maintain their rate even with overall high market vacancy.
According to InVenture’s assessment, the investment logic of office real estate in 2026 has become more cautious: before the pandemic and the war, the typical payback period for office premises was estimated at about 7-8 years, whereas in 2026, 10-12 years is already becoming the norm for most assets. At the same time, the best properties with a strong tenant and a successful location may show more attractive results, but this is rather an exception.
According to Experts Club’s forecast, by the end of 2026 Ukraine’s office market will move according to a scenario of slow recovery without a sharp increase in rates. Kyiv will retain the status of the main market, Lviv the status of the main regional center of demand, while Dnipro, Odesa and Kharkiv will develop mainly at the expense of local tenants and selective deals.
“The main risk for the market is not the absence of demand, but its quality. Demand exists, but it has become cautious, rational and demanding. Tenants want to pay not for meters, but for a guaranteed ability to work. This means that office real estate in Ukraine is gradually moving from a space model to a service and resilience model,” Experts Club summarizes.
Thus, by May 2026, the office real estate market of Kyiv and major Ukrainian cities remains in a transitional phase. It has already passed through the period of a shock decline, but has not yet returned to a full-fledged investment cycle. The most sought-after offices are becoming safe, ready-to-use, energy-resilient and flexible ones. Outdated properties without renovation, autonomy and a clear operational model will continue to lose competitiveness.
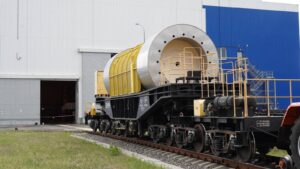
On Thursday, May 28, at the Centralized Spent Fuel Storage Facility site, Oleg Korikov, Chairman of the State Nuclear Regulatory Inspectorate of Ukraine (SNRIU), officially handed over the license for the “nuclear facility operation” life cycle stage of the Centralized Spent Fuel Storage Facility to Pavlo Kovtonyuk, Acting Chairman of the Board of NAEK “Energoatom.”
“Obtaining the license to operate the repository confirms the Ukrainian nuclear industry’s ability to implement large-scale and technologically complex projects in accordance with the highest global safety standards,” stated the head of Energoatom during the handover of the licensing documents.
According to him, the facility’s operation over the next 100 years will strengthen the energy resilience of Ukraine’s nuclear power generation, ensure the safe management of spent nuclear fuel, and provide the state with significant economic benefits—currently, Ukraine saves approximately $200 million annually, which was previously spent on transporting fuel abroad.
In turn, as noted by SNRIU Chairman Korikov, the issuance of a license for the “nuclear facility operation” life cycle stage of the CSFSF marks the completion of the process of establishing Ukraine’s own system for the safe management of spent nuclear fuel (SNF).
Prior to the issuance of this license, the storage facility operated under a separate commissioning license.
“From the perspective of the state regulatory body for nuclear and radiation safety, it is important that the operation of the CSFSF ensures compliance with nuclear and radiation safety requirements and IAEA standards,” Korikov emphasized.
He explained that, in accordance with these standards, the spent fuel storage pools of each reactor unit at a nuclear power plant must have sufficient free volume to accommodate the complete unloading of the core at any point during operation.
“The CSFSF is a practical solution to the issue of spent nuclear fuel management following the termination of cooperation with Russia in this area,” added the head of the SNRA.
The decision to issue the license was the result of a state review of the nuclear and radiation safety of the supporting documentation for Energoatom’s application and an inspection of the operating organization.
As Energoatom noted, construction of the CSFSF began in 2017. In 2020, construction of the first launch complex was completed, and in 2021, the special Vilcha-Yaniv railway line was completed, connecting the storage facility to Ukraine’s general railway network.
On the eve of the full-scale Russian invasion, Energoatom completed a series of cold tests of all the facility’s systems, and on April 25, 2022, the State Nuclear Regulatory Inspectorate issued a separate permit to commission the CSFSF.
In other words, until May 25, 2026, the storage facility operated under a separate permit and a special license for commissioning. After completing all necessary procedures and inspections, the State Nuclear Regulatory Inspectorate issued the CSFSF a permanent operating license.
The stable operation of the CSFSF ensures the continued operation of nine Ukrainian power units in the territory controlled by Ukraine and guarantees the continuity of electricity generation.
Previously, Ukraine shipped spent nuclear fuel from the Rivne, Khmelnytskyi, and South Ukraine NPPs to Russia annually for storage and reprocessing, spending approximately $200 million on this. The creation of the CSFSF made it possible to completely abandon this practice and eliminate critical dependence on Russian nuclear infrastructure.
The repository is designed for at least 100 years of operation and uses the “dry” storage technology developed by the American company Holtec International, which is used in the United States, Spain, the United Kingdom, and other countries.
American billionaire and tech investor Peter Thiel has temporarily moved his family to Argentina and is considering the country as a potential fallback base amid political, economic, and security risks in the U.S., according to the Financial Times and The New York Times.
According to media reports, Thiel has frequently visited Buenos Aires in recent months, meeting with Argentine President Javier Milei and representatives of his government. The investor has also purchased a mansion in a prestigious neighborhood of the Argentine capital and enrolled his children in a local private school.
One factor cited for Thiel’s interest in Argentina is Javier Milei’s policies. The Argentine president is implementing a program of large-scale deregulation, cuts in government spending, and libertarian economic reforms. These ideas align with Thiel’s views, as he has long advocated for reducing the role of the state, taxes, and regulation.
According to The New York Times, Argentine authorities have also explored the possibility of granting Thiel permanent residency or citizenship, though the investor himself has not yet applied for Argentine citizenship.
Thiel’s move to Argentina is being discussed against the backdrop of a broader trend among some American tech entrepreneurs and investors who are seeking alternative jurisdictions for residency, asset management, and capital protection. Among the reasons cited by the media are tax risks, political polarization, security concerns, and interest in countries with more flexible regulations.
For Argentina, Thiel’s presence holds symbolic significance. One of Silicon Valley’s most famous investors is effectively demonstrating interest in Milei’s economic agenda, as he seeks to transform the country into a hub for capital, tech companies, and entrepreneurs focused on minimal regulation.
Peter Thiel is a co-founder of PayPal, one of Facebook’s earliest investors, and chairman of the board of directors at Palantir Technologies. He is also known as a major political donor in the U.S. and an ally of parts of the Republican establishment, including Donald Trump’s inner circle. His fortune is estimated at tens of billions of dollars.
The Odesa Investment Congress 2026, dedicated to Ukraine’s investment potential and new regional development strategies, will take place on July 10 in Odesa at the SPATIUM Hotel, according to the event organizers.
The national-level congress is organized by DMNTR Media Group, with SPATIUM Group serving as the general partner. The event will be the Odesa leg of the UBC project and will be held in Odesa for the first time.
Developers, investors, architects, urban planners, representatives of the government, the international community, the banking sector, and the business community, as well as designers and brokers from various regions of Ukraine, are invited to participate.
The Odesa Investment Congress 2026 will focus on investment trends for 2027–2030, the profitability of various asset types, developers’ expansion into new regions, site evaluations, project risks and payback periods, as well as the integration of UNESCO heritage preservation with modern urban development.
Special attention will be given to accessibility as a fundamental principle of shaping the modern environment, the development of apart-hotels, the revitalization of industrial zones, a new architectural code, healthcare, the wellness sector, and recreational architecture as drivers of the new economy in Ukrainian cities.
The congress program includes four thematic halls, panel discussions, a press conference, a presentation of SPATIUM investment projects, a gala evening, a fashion show, and the presentation of the Vasyl Kandinsky Special Award.
A special program is also planned for guests on July 9 and 11, including visits to construction sites, presentations, and a dinner.
Among the announced participants and market companies are SPATIUM, Zezman, “Gefest,” Kreator-Bud, KADORR, SAGA, RIEL, “Akvareli,” “Dva Akademika,” Stolitsa Group, Sigma+, Vlasne Misto, and other companies working in the field of development and growth of Ukrainian territories.
“The Odesa Investment Congress 2026 will serve as a platform to discuss where investments are heading, which regions of Ukraine could become new growth hubs, and how development, architecture, medicine, wellness, and modern urban infrastructure are shaping the economy of the future,” the organizers note.
The event will take place on July 10, 2026, at the SPATIUM hotel in Odesa. The event will run from 8:00 AM to 9:00 PM.
To join the congress as a VIP guest, speaker, or partner, please call: 044 461 91 28.
More details about the congress: www.ubc-ua.info/oic
Organizer: DMNTR Media Group. General partner: SPATIUM Group.
Interfax-Ukraine – information partner
Kyivstar, Ukraine’s largest mobile operator, has announced its vision to increase the share of revenue from digital services to 50% in the future, a figure that has risen to 20% in recent years.
“Our vision is that one day our revenue from digital services will equal our revenue from telecommunications. We’ve reached 20% now. We still need 30%,” Kyivstar CEO and President Oleksandr Komarov said at Forbes Money on Thursday.
According to him, thanks to this year’s acquisition of Tabletki, the company already has more digital customers than telecom customers: the group’s digital businesses reached a three-month audience of 28 million users, compared to 22 million in the telecom business.
“In other words, we are moving forward with the implementation of our strategy. We understand that the core value today, unfortunately, is not created by the presence of a telecom connection,” Komarov added.
He clarified that the company is currently building an ecosystem of various digital services around its core offering, which is the telecom business.
“But perhaps in five years, the core offering will be, for example, the ‘Uklon’ offering. In other words, this creates a field of opportunities for the development of the Kyivstar Group,” said the president of Kyivstar.
Komarov noted that the company’s investment payback period is estimated at around 5–6 years.
“We don’t factor synergies into the deals, but we certainly keep in mind what synergies we can achieve. For example, the synergies between Kyivstar and Tabletki are quite insignificant, but the synergies between Tabletki and Helsi are quite significant,” the mobile operator’s CEO cited as an example.
He emphasized that it is also important for Kyivstar to reduce its dependence on its core telecom business, as investors are less interested in this sector.
“There is hope that at some point we will be able to position this group as a set of digital assets with a completely different perspective on its valuation,” Komarov explained.
As reported, Kyivstar increased its consolidated EBITDA by 28.5% in the first quarter of 2026—to 7.5 billion UAH—while revenue grew by 31.3%—to 13.9 billion UAH.