
Net inflows from non-residents for real estate purchases in Egypt for the 2025/2026 fiscal year, which ended on June 30, increased by 47.4% compared to the previous fiscal year—rising from $1.9 billion to $2.8 billion. This is according to data from the Central Bank of Egypt (CBE) published on October 12, 2026.
Thus, revenues increased by approximately $900 million over the course of the year. This positive trend is driven by growing international demand for Egyptian real estate, the development of major construction projects, and government initiatives aimed at attracting foreign capital.
However, the Central Bank’s statistics include real estate purchases by all non-residents, including foreign nationals and Egyptians permanently residing abroad. Therefore, the $2.8 billion figure cannot be attributed entirely to foreign nationals.
The growth in real estate investment has become part of an overall increase in the inflow of foreign capital into Egypt’s economy. According to Central Bank data, the net inflow of foreign direct investment in the 2025/2026 fiscal year reached approximately $18 billion, compared to $12.2 billion a year earlier.
In particular, investments in the establishment of new enterprises and capital increases for existing companies rose to $8.8 billion from $5.5 billion. Reinvested earnings increased from $4.2 billion to $6.2 billion, while net proceeds from the sale of companies and production assets to non-residents totaled $433.2 million, compared to $399.8 million a year earlier.
Large-scale real estate development projects along the Mediterranean coast, in New Cairo, and in Egypt’s new administrative capital play a significant role in attracting investment.
In May 2026, Egypt’s Ministry of Justice finalized a draft law regulating the purchase of completed real estate and undeveloped land plots by foreign nationals. Its goal is to simplify property registration procedures and make the market more accessible to foreign investors.
The government is also developing digital mechanisms for real estate purchases by foreigners, which involve processing transactions and transferring funds through Egypt’s banking system.
Against the backdrop of growing foreign demand, the authorities are paying increasing attention to the transparency of development projects, property registration, and the protection of buyers’ interests.
Unlike Turkey, where the statistics agency publishes monthly data on the number of transactions with foreigners broken down by citizenship, Egypt does not provide a comparable nationwide ranking of real estate buyers that is publicly available.
Therefore, the structure of foreign demand must be assessed based on studies by consulting firms, reports from Egyptian developers, and regional real estate agencies.
One of the largest groups of buyers consists of citizens of Gulf states, primarily Saudi Arabia, Qatar, the UAE, and Kuwait.
According to an assessment by Basem Kalila, CEO of Kalila—the company that organizes the international Nile Property Expo—published by the Egyptian publication Osoul Misr on October 1, 2026, the most active foreign buyers of Egyptian real estate are citizens of Saudi Arabia and Qatar.
Saudi buyers are showing particular interest in real estate in Egypt’s new administrative capital. Qatari citizens are primarily considering projects on the northern coast of the Mediterranean Sea, while investors from other Gulf states are actively interested in the western districts of Cairo.
It should be noted that this is a market participant’s assessment, not an official statistical ranking based on the number of registered transactions.
The second largest category of buyers consists of Europeans and citizens of former Soviet Union countries, who traditionally purchase real estate in Red Sea resorts.
According to a September 19, 2025, article in the Egyptian newspaper Al-Masry Al-Youm, representatives of the local real estate development industry cited citizens of Russia, Germany, the United Kingdom, and Italy as among the most active foreign buyers in Hurghada.
Buyers from Poland, the Netherlands, the Czech Republic, and other European countries are also showing significant interest in resort housing.
Unlike investors from the Persian Gulf, who tend to focus on large residential complexes and high-end real estate in the capital region and along the Mediterranean coast, European buyers primarily consider apartments for vacation use, long-term residence, and subsequent rental.
The main centers of this demand remain Hurghada, El Gouna, Sahl Hasheesh, and other Red Sea resort areas. Sharm el-Sheikh holds a special place, as it has specific rules governing the registration of property rights for foreigners.
Ukrainian citizens are also among the foreign buyers of Egyptian real estate, primarily in the Red Sea resorts. According to a study by Experts Club and the Relocation.com.ua project, published on September 14, 2025, Ukrainians are among the most prominent groups of buyers of resort properties in Egypt, especially in Hurghada.
According to market participants, Ukrainian citizens began actively purchasing real estate in Egyptian resorts as early as the 2010s, and after the outbreak of full-scale war in 2022, some buyers began to view Egypt not only as a tourist destination but also as a place for long-term residence.
Ukrainians are most interested in relatively affordable apartments ranging from 40 to 70 square meters, which are purchased for personal use, seasonal vacations, or rental purposes.
A study by Experts Club noted that Ukrainian buyers are primarily concentrated in the affordable price segment, while wealthier investors are looking at properties priced at $300,000 and above, particularly due to the opportunity to participate in Egypt’s investment migration programs.
However, the country’s Central Bank has not published official data on the number of properties purchased by Ukrainian citizens in Egypt during the 2025/2026 fiscal year. Consequently, it is not yet possible to determine the exact share of Ukrainians in the total volume of non-resident investments or their current standing among foreign buyers.
The program for obtaining Egyptian citizenship through investment provides, in particular, for the purchase of real estate valued at no less than $300,000, subject to compliance with the conditions set by the state. This program is designed for a specific category of investors and does not reflect the typical budget of buyers of resort apartments.
Egyptian authorities view international real estate sales as one of the tools for attracting foreign currency, increasing investment, and developing the construction sector. One of the largest markets remains the northern coast of the Mediterranean Sea, where large-scale projects involving Arab capital are being implemented.
A neutral stance continues to dominate Ukrainians’ attitudes toward Egypt: in August 2026, 61.3% of respondents expressed this view. 28.1% of those surveyed view the country positively, while 6.9% view it negatively. Compared to March, the share of positive assessments has decreased, while the share of negative ones has increased, according to the Experts Club Information and Analytical Center.
According to the results of the August survey, 7.2% of Ukrainians have a completely positive attitude toward Egypt, while 20.9% have a mostly positive attitude. A neutral stance is held by 61.3% of respondents. 6.3% view the country mostly negatively, 0.6% view it entirely negatively, and another 3.7% were undecided.
The balance of positive and negative assessments based on these indicators is +21.2 percentage points. Thus, positive attitudes toward Egypt are roughly four times more prevalent than negative ones; however, the high proportion of neutral responses remains the defining characteristic of how the country is perceived.
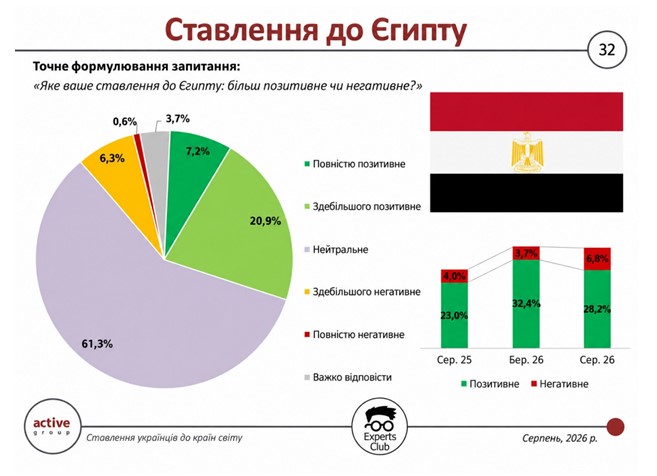
Compared to March 2026, attitudes have deteriorated slightly. In the previous survey wave, 10.5% of respondents rated Egypt entirely positively, and 21.9% rated it mostly positively—meaning the overall positive rating stood at 32.4%. 62.5% of respondents were neutral, and the share of negative ratings in the aggregated results was about 3.7%.
Thus, over the course of five months, the share of positive responses decreased by 4.3 percentage points—from 32.4% to 28.1%—while the share of negative responses increased by approximately 3.2 percentage points—to 6.9%. The share of neutral assessments changed only slightly—from 62.5% to 61.3%. The balance between positive and negative attitudes decreased from approximately plus 28.7 to plus 21.2 percentage points, respectively.
Maksym Urakin, founder of the Experts Club information and analytical center and a candidate of economic sciences, believes that the case of Egypt clearly illustrates the difference between a country’s economic importance to Ukraine and the extent of its presence in the public consciousness.
“Egypt is a very important export market for Ukraine, primarily for agricultural and food products. At the same time, for most Ukrainians, this country remains more of a tourist destination than an economic partner. That is precisely why we see such a high proportion of neutral assessments: economic ties are significant, but they are not always visible to the general public,” Urakin noted.
According to him, the positive trade balance with Egypt makes this market particularly important for Ukraine amid a general foreign trade deficit.
“When a country provides Ukraine with a significant trade surplus, it is no longer a secondary partner. Such markets must be viewed strategically—in terms of maintaining exports, expanding the range of goods supplied, and fostering long-term economic ties. In the case of Egypt, the potential for this is obvious, but public perception has simply not yet caught up with the country’s actual economic role,” Urakin added.
Thus, Egypt demonstrates a noticeable gap between its economic significance and public perception. Despite the fact that the country is one of Ukraine’s most profitable trading partners in terms of the trade balance, over 60% of Ukrainians continue to view it neutrally. This indicates limited awareness and low emotional engagement rather than a negative attitude.
The survey was conducted in August 2026 using self-administered online questionnaires in the SunFlowerSociology panel among 800 Ukrainian citizens aged 18 and older. The previous wave also included 800 respondents; the sample was representative by age, gender, and region, with a maximum theoretical margin of error of ±3.5 percentage points for indicators at the 50% confidence level.
ACTIVE GROUP, EGYPT, EXPERTS CLUB, FOREIGN TRADE, international relations, NORTH AFRICA, PUBLIC OPINION, SOCIOLOGY, UKRAINE, URAKIN
According to Experts Club, Egypt has the highest level of positive sentiment among Ukrainians among the North African countries included in the study: 28.2% of respondents view it positively, and the net positive rating stands at 21.4 percentage points. At the same time, neutral assessments dominate perceptions of all four countries in the region—their share ranges from 59.3% to 67.3%. This is evidenced by the results of the third wave of the study “Ukrainians’ Attitudes Toward Countries Around the World,” conducted by Active Group in collaboration with Experts Club, reports the Experts Club Information and Analytical Center.
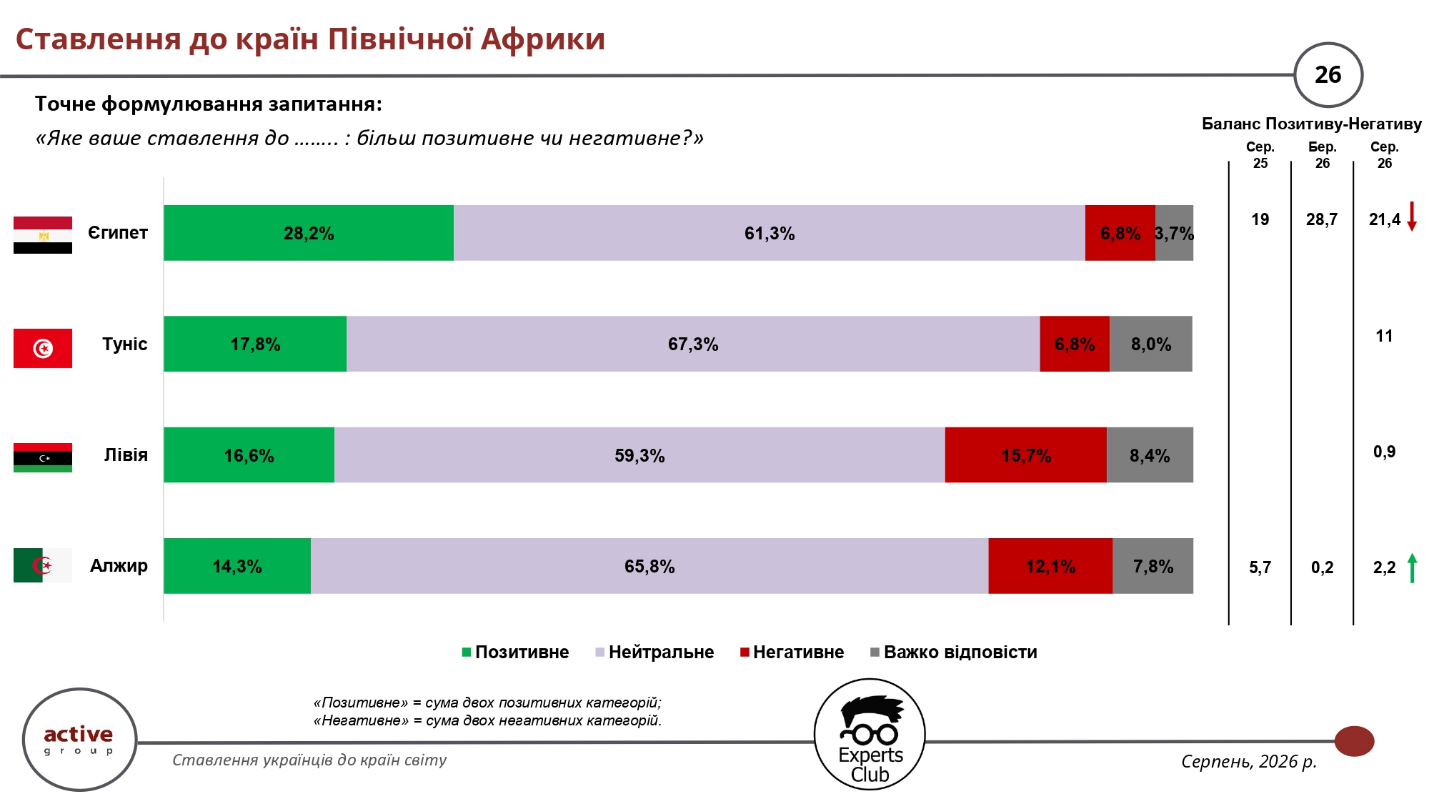
28.2% of Ukrainians surveyed view Egypt positively, 61.3% neutrally, 6.8% negatively, and another 3.7% were undecided. The balance of positive and negative assessments in August 2026 stood at 21.4 percentage points, compared to 28.7 percentage points in March and 19 percentage points in August 2025. Thus, following a spring increase, the indicator has declined but remains slightly higher than it was a year ago.
Neutral attitudes toward Tunisia predominate—67.3% of respondents expressed this view. 17.8% view the country positively, 6.8% negatively, and another 8% were undecided. The balance stands at plus 11 percentage points, placing Tunisia in second place among the North African countries surveyed.
In Libya, positive and negative assessments are virtually equal: 16.6% of respondents view the country positively, 15.7% negatively, and 59.3% neutrally. Accordingly, the balance is only +0.9 percentage points.
For Algeria, the share of positive assessments is 14.3%, negative—12.1%, neutral—65.8%, and another 7.8% of respondents were undecided. The balance stands at plus 2.2 percentage points. In March 2026, it was only plus 0.2 percentage points, and in August 2025, it was plus 5.7 percentage points.
Thus, none of the North African countries surveyed has a negative sentiment balance; however, the high proportion of neutral responses indicates that Ukrainians’ attitudes toward these countries are significantly less well-defined compared, for example, with their attitudes toward European countries. At the same time, Egypt and Algeria are also economically important to Ukraine: according to data presented at the press conference, in the first half of 2026, Ukraine’s trade surplus with Egypt amounted to $527.1 million, and with Algeria—$309.2 million.
Maksym Urakin, founder of the Experts Club Information and Analytical Center, deputy director of the Interfax-Ukraine news agency, and candidate of economic sciences, emphasized the need for partner countries to communicate more actively with the Ukrainian audience.
“The first recommendation is to regularly highlight specific projects, concrete actions, and the presence here of foundations, embassies, teams, and diplomats in the humanitarian sphere and in science. Second, to be open to questions and inquiries from the media and the public,” Urakin noted. According to him, it is also advisable to use sociological survey results to strengthen bilateral relations, particularly in the trade sector.
The survey was conducted in August 2026 using self-administered online questionnaires in the SunFlowerSociology panel among 800 Ukrainian citizens aged 18 and older. According to the organizers, the sample is representative in terms of age, gender, and region, with a maximum theoretical margin of error of ±3.5 percentage points. This is the third wave of the study, following surveys conducted in August 2025 and March 2026.
ACTIVE GROUP, ALGERIA, EGYPT, EXPERTS CLUB, international relations, LIBYA, NORTH AFRICA, SOCIOLOGY, TUNISIA, UKRAINE
The Egyptian government has approved the creation of “The Spine,” a special private investment zone in the Madinaty district of New Cairo. The project, valued at approximately $27.4 billion, involves the construction of 165 residential, office, and hotel towers and is positioned by the developer as the first large-scale “cognitive city” in Egypt and the Middle East, where artificial intelligence will be widely used to manage its infrastructure.
Approximately 2.1 million square meters of land within the existing Madinaty project will be allocated for development. In addition to residential, office, and hotel buildings, the project will include retail, entertainment, tourism, medical, and other infrastructure.
Orion Urban Development, a subsidiary of one of Egypt’s largest developers, Talaat Moustafa Group Holding (TMG), has been granted the right to establish and develop the investment zone. Back in April, Egypt’s General Authority for Investment and Free Zones (GAFI) approved the creation of the country’s first private investment zone of this type for the project.
Investments in The Spine are estimated at over $27.4 billion, and the project’s paid-in capital amounts to approximately $1.35 billion. TMG’s partner is the National Bank of Egypt. The developer expects that the project will create 55,000 direct jobs and about 100,000 indirect jobs.
TMG Chairman Hisham Talaat Mustafa estimates The Spine’s potential contribution at approximately 1% of Egypt’s GDP, with total tax revenues from the project over its entire operational period amounting to approximately $16 billion. The company also expects to attract international corporations, tourists, and business visitors to the area. These figures are projections provided by the developer itself.
One of the distinctive features of The Spine is expected to be the extensive digitization of urban infrastructure. TMG states that it will use artificial intelligence systems and self-learning technologies to manage urban services. The project also includes an underground logistics and road network, which should free up a significant portion of the surface area from vehicular traffic.
Approximately 70% of the surface area—or more than 1.5 million square meters—is planned to be allocated to green spaces and open areas. Medical infrastructure will also be integrated into the project, including a partnership with the American hospital Houston Methodist Hospital.
The special status of the investment zone is intended to simplify registration, licensing, import, and export procedures for companies operating there. The project will feature its own customs infrastructure and a special support program for investors, which is a key part of the effort to transform The Spine not only into a residential area but also into an international business cluster.
TMG officially unveiled The Spine on April 18–19, 2026, in the presence of Egyptian Prime Minister Mustafa Madbouly, following approximately five years of preparation and research involving international consultants.
The project is in the early stages of implementation, though some elements of Madinaty’s infrastructure are already under construction: a medical complex in partnership with Houston Methodist is scheduled to open in April 2027. The overall timeline for completing construction of all 165 towers of The Spine has not yet been publicly announced.
Egypt has begun integrating the resorts along the northern Mediterranean coast into a single year-round tourist and investment destination. The new model will be based on the Yalla Sahel initiative, which aims to connect existing and developing resort areas through a shared digital platform, an events calendar, and tourism services.
The project was unveiled in July 2026 in Sidi Abdel Rahman. It was spearheaded by Egyptian entrepreneur Naguib Sawiris. Major developers, tourism companies, telecommunications operators, and Egyptian government agencies have joined the platform.
Yalla Sahel is not a standalone construction project. Rather, it involves creating a unified brand for Egypt’s northern coast, which is expected to gradually transition from a short summer season to year-round operations.
Traditionally, the region known in Egypt as the Sahel sees its highest volume of visitors in July and August. Many residential complexes, restaurants, and retail and entertainment venues operate at limited capacity or are closed entirely for most of the year.
The initiative’s organizers hope to change this model by developing event-based tourism, digital services, transportation, and infrastructure for year-round living.
On the Yalla Sahel platform, users will be able to book apartments, villas, and chalets; purchase tickets to beaches, concerts, and other events; and select tourism services.
The service covers New El Alamein, Ras el-Hekma, Sidi Abdel Rahman, Marassi, Marina, Fouka Bay, Hacienda, and Almazah Bay. Property owners will also be able to list their properties for short-term rentals.
A separate component of the project will be the TELLR digital concierge, through which tourists can obtain information about restaurants, hotels, events, entertainment, and transportation between resorts.
The state-owned company Telecom Egypt intends to provide the project with telecommunications infrastructure and digital solutions. The authorities view the northern coast as an emerging international tourism, residential, and investment hub.
To extend the tourist season, there are plans to hold concerts, festivals, sporting events, and cultural activities not only in the summer but also during other times of the year. EgyptAir, TikTok, and regional airlines are participating in the promotion of this destination.
New Alamein will become the key city of the new Egyptian Riviera. According to data from Egypt’s official tourism portal, the city is being developed on an area of approximately 50,000 acres and is projected to have a population of more than 3 million residents.
Residential neighborhoods, hotels, universities, administrative buildings, and recreational facilities are being built in New Alamein. The city features a waterfront stretching about 14 km, home to restaurants, shops, a movie theater, a beach club, and concert venues.
Egyptian authorities are positioning New Alamein as the first fully-fledged, year-round city on the northern coast, designed not only for tourists but also for permanent residents.
Another important center will be Ras el-Hekma, where a large-scale project involving capital from the United Arab Emirates is underway. Together with New Alamein, Sidi Abdel Rahman, and other resorts, it is expected to form a continuous belt of tourist and residential development along the Mediterranean Sea.
The transition to a year-round model could boost demand for property purchases and long-term leases, as well as increase investor interest in hotels, retail properties, restaurants, and service companies.
For property owners, a longer season means the opportunity to increase occupancy rates and reduce their reliance on income from just the two summer months.
At the same time, the region’s development will require the construction of schools, medical facilities, transportation infrastructure, and affordable housing for permanent resort workers.
The project’s success will depend on whether Egypt can transform seasonal residential complexes into full-fledged cities with permanent jobs and sustainable demand for services.
Egypt hopes that the new Riviera will enable the country to attract more tourists from Europe and the Gulf states, increase real estate investment, and reduce the strain on traditional Red Sea resorts.
Egypt’s largest developers maintained high sales levels in early 2026, despite cooling demand and the real estate market entering a more cautious phase, according to a report by The Board Consulting.
According to the report, the total value of contracts signed by Egypt’s ten largest developers in the first quarter of 2026 amounted to 271 billion Egyptian pounds, or more than $5 billion. This is 6.5% less than the record 290 billion pounds a year earlier, but the figure remains significantly higher than in previous years and confirms the resilience of the market’s largest players.
In physical terms, sales declined more sharply—by approximately 15%—to about 15,500 units. This reflects more cautious buyer behavior amid rising construction costs, currency volatility, changing financing conditions, and general macroeconomic uncertainty.
However, the market has not collapsed but is rather undergoing a structural shift. The main cash flows are concentrated among the largest and financially stable developers, while small and medium-sized developers face pressure due to the cost of capital, competition, and the need to offer long-term installment plans.
East Cairo remains the geographic leader, generating contracts worth 130 billion pounds over the quarter. Demand is driven by new residential complexes, proximity to the New Administrative Capital, and large-scale infrastructure development in the eastern part of the metropolitan area.
For foreign buyers, Egypt remains one of the most affordable major real estate markets in the region. The weakening of the Egyptian pound has made housing relatively cheaper for buyers holding dollars, euros, or Gulf currencies. According to Global Property Guide, real estate prices in Egypt rose by 13.25% year-over-year in October 2025, but in real terms—adjusted for inflation—growth amounted to only 0.67%.
External demand is driven primarily by several groups. The first consists of investors from Gulf countries, primarily the UAE, Saudi Arabia, Kuwait, Qatar, Bahrain, and Oman. Egyptian developers are actively promoting projects in the GCC, and Gulf buyers have high purchasing power and interest in large resort and urban projects. Invest-Gate notes that buyers from Gulf countries and the Egyptian diaspora already account for about one-third of sales under the “real estate export” initiative.
The second group is the Egyptian diaspora. For Egyptians living in Europe, the U.S., the Gulf states, and other regions, real estate in Egypt remains a way to maintain a connection with the country, protect capital from inflation, and acquire housing for their families or for a future return.
The third group consists of buyers from Arab countries experiencing political or economic instability. Among them, citizens of Syria, Iraq, Sudan, and Palestine are frequently mentioned. For some of these buyers, real estate in Egypt is linked not only to investment but also to residency, obtaining resident status, and long-term security.
The fourth group consists of buyers from Russia, Ukraine, and Kazakhstan, primarily in Red Sea resort locations, including Hurghada, El Gouna, and the areas around Sahl Hasheesh. For them, Egypt is attractive due to its low entry barrier, warm climate, tourist demand, and the opportunity to purchase housing at a lower cost than in Turkey, the UAE, or certain European markets.
The fifth group consists of European buyers, including citizens of Germany, the UK, Italy, and other EU countries, who view Egypt as a market for affordable resort real estate, rentals, and seasonal living.
For foreign buyers, an important feature of the market is the long-term installment plans offered by developers. In Egypt, a significant portion of housing is sold off-plan, and buyers often make a 5–10% down payment and pay the remainder over 7–10 years. This mechanism makes the market accessible but simultaneously increases the importance of choosing a reliable developer and conducting a legal review of the contract.
The Egyptian government is also seeking to more actively develop “real estate exports” as a source of foreign exchange revenue. Authorities view the sector as a tool for attracting foreign capital, especially following the $35 billion Ras El-Hekma deal with Abu Dhabi’s ADQ, which became the largest foreign direct investment agreement in the country’s history.
Thus, the Egyptian real estate market is not entering a crisis phase, but rather a phase of weeding out weaker players. Buyers are becoming more cautious, and the volume of transactions is declining, but the largest developers continue to generate billions of dollars in sales. For foreign investors, the main concern now is not just price, but the reliability of the project, currency risks, the legal soundness of the transaction, and the developer’s ability to complete the project on time.



