
Heavy rains in Brazil have degraded the quality of the new coffee crop and could lead to a shortage of high-quality Arabica beans on the global market, while futures for this variety have risen by approximately 35% since June, according to Bloomberg.
Brazil is the world’s largest producer of Arabica and accounts for about 45% of global production, so problems with harvest quality could affect the supply of premium coffee far beyond the country’s borders.
The main problem was extremely heavy rainfall during the harvest. In June, rains knocked a large number of ripe coffee cherries off the trees, after which they lay on waterlogged ground for several days, increasing the risk of fermentation, mold, and undesirable flavors.
According to Simao de Lima, president of the Expocacer cooperative—which unites more than 800 producers in the Cerrado Mineiro region in southeastern Brazil—the rains knocked down an average of about 20% of the coffee cherries, compared to the usual 5–7%.
Thus, this does not represent a 20% loss of Brazil’s entire harvest, but rather significant damage to the crop in one of the most important regions for the production of high-quality Arabica.
The situation was exacerbated by a second wave of rainfall in July. The rains fell on beans that had already been harvested and laid out to dry, forcing some producers to start the drying process all over again.
According to data from the meteorological company Vaisala, rainfall in certain areas of Brazil’s coffee belt in June and July reached 250–500% of the climate norm, and in some places, up to eight times more rain fell than usual.
Quality issues are already affecting the market. Arabica futures have risen by about 35% since June, offsetting a significant portion of the price decline since the beginning of the year.
In the physical market, high-quality Brazilian coffee is selling at a premium of up to 15 cents per pound compared to futures in New York.
The reduction in the volume of coffee meeting the delivery standards for Intercontinental Exchange (ICE) certified warehouses in the U.S. and Europe could prove particularly significant.
In a typical year, approximately 30–35% of the Cerrado Mineiro region’s production meets ICE requirements. Following this year’s rains, de Lima estimates that this share could drop to 10–15%. Meanwhile, coffee stocks in ICE-certified warehouses are already approaching their lowest levels of this century.
This could intensify competition among international roasters for high-quality beans. Bloomberg notes that Brazilian Arabica is used, in particular, by companies such as Starbucks, Lavazza, and Illy.
However, it is still too early to speak of a general coffee shortage. The U.S. Department of Agriculture expects that in the season beginning in October, global coffee supply will exceed consumption by approximately 10 million bags, which would be the largest surplus in six years. One of the main factors is expected to be record production in Brazil itself.
Therefore, the market’s main problem lies not so much in the total volume of coffee as in the availability of high-quality Arabica. Major producers can partially offset the shortage by adjusting the composition of their coffee blends and sourcing beans from other regions; however, for the premium segment, the situation could lead to further increases in purchasing and retail prices.
Weather remains an additional risk for the market. Reuters notes the intensification of the El Niño phenomenon, which in the 2026–2027 season could further increase volatility in the markets for coffee, cocoa, and other tropical agricultural commodities.
Wheat trade in Ukraine remains sluggish, while the corn market continues to see some activity, primarily along the western border, consulting firm Barva Invest reported on its Telegram channel.
According to the firm, prices for Ukrainian wheat with an 11.5% protein content on a DAP-Danube basis stand at $166–168 per metric ton.
“An imbalance between supply and demand persists in the Ukrainian wheat market. A shortage of EU quotas, logistics at the western border booked months in advance, and the absence of panic among importers are holding back trading activity and putting downward pressure on prices,” the report states.
Quotes for Ukrainian corn on a DAP Izov basis stand at $173 per metric ton.
“The Ukrainian corn market is in the off-season and awaiting the resumption of deep-water exports. Some activity continues along the western border for both the old crop and forward contracts,” analysts note.
Prices for food and feed wheat in Ukraine remained unchanged over the week—$195 and $185 per metric ton, respectively, on a CPT Odessa basis, according to the brokerage firm Spike Brokers.
“Ukrainian wheat exports in August are estimated at 500,000 metric tons, compared to the usual 2 million metric tons for this month. Russian wheat exports in August are expected to reach 2 million metric tons, compared to 4.5 million metric tons last year. The flow of Ukrainian wheat to Constanta has begun to increase but remains limited for now. Efforts are being made to compensate for the shortage of Ukrainian wheat on the global market through other exporters,” the report states.
The price of corn also remained unchanged at $190 per metric ton on a CPT Odessa basis and $220 per metric ton on an FCA Chop basis.
According to brokers, the price of sunflower seeds also remained unchanged at $440 per metric ton (including VAT) on a CPT mill basis.
At the same time, rapeseed prices at the western border rose by $5—to $550 per metric ton on an FCA Chop basis. The price of rapeseed on a CPT port basis was $500 per metric ton, and on a CPT mill basis—$485 per metric ton.
Soybean prices also remained unchanged: GMO soybeans were priced at $420 per metric ton on a CPT port basis, $435 on an FCA Chop basis, and $425 on a CPT plant basis, while non-GMO soybeans were priced at $440 per metric ton on a CPT port basis and $470 on an FCA Chop basis.
According to Spike Brokers, global corn prices rose over the week, but Ukrainian prices remained unchanged due to physical export constraints. At the same time, the highest premium in the soybean market remains in the non-GMO segment along the western border.
On the Ukrainian grain and oilseed market, prices showed mixed trends over the week: wheat remained at the previous level, sunflower seed prices fell significantly, while rapeseed prices for export rose, according to the brokerage firm Spike Brokers.
According to data from analysts published on their Telegram channel, wheat with 11.5% protein on CPT Odessa terms was priced at $195 per metric ton, while feed wheat was priced at $185 per metric ton. On FCA Chop terms, wheat traded mainly at EUR180–185/metric ton for loading onto a European train.
The price of corn on CPT Odessa terms fell by $5 per metric ton over the week to $190 per metric ton, while on FCA Chop terms it remained at $220 per metric ton. The new October–March crop was trading at EUR188–193 per metric ton FCA Chop at the western border.
The price of sunflower seeds on CPT mill terms fell by $110 per metric ton over the week to $440 per metric ton. According to the broker, the market continues to transition to pricing for the new crop, and the external rise in prices for soybean oil and crude oil has not yet been reflected in Ukrainian raw material prices.
In the rapeseed market, the price on CPT port terms remained at $500 per metric ton, while on FCA Chop terms it rose by $5 per metric ton to $550 per metric ton. At the same time, the price of rapeseed for domestic processing fell by $15/metric ton to $485/metric ton. Thus, the difference between the FCA Chop export price and the price for domestic processing is $65/metric ton.
As of August 10, Ukraine had harvested 3.22 million metric tons of rapeseed from 1.191 million hectares—or 89% of the planted area—with a yield of 2.71 metric tons per hectare. Current pricing is determined by the distribution of supply among the western border, ports, and domestic processing.
The price of GMO soybeans on CPT port terms was $420 per metric ton, FCA Chop – $435 per metric ton, and non-GMO soybeans – $440 per metric ton and $470 per metric ton, respectively. The price of GMO soybeans for domestic processing rose by $5 per metric ton over the week, reaching $425 per metric ton.
“Thus, sunflower seeds are adjusting to the purchase price of the new crop; competition is intensifying in rapeseed between FCA Chop and processing; and soybeans are receiving an external boost from the CBOT and Chinese demand, which is not yet being strongly reflected in the Ukrainian physical market,” analysts note.
Prices for housing in Turkey in July 2026 rose by an average of 23.3% in local currency compared to last year; however, high inflation completely offset this increase: in real terms, real estate prices fell by 6.6%, according to the July market review by the platforms Emlakjet and Endeksa. The data was published on August 14.
The average price per square meter of housing nationwide reached 41,700 Turkish lira, or approximately $871, while the average price of a property sold was 5.21 million lira, which corresponds to approximately $109,000.
At the same time, July saw the first small positive sign in short-term trends: prices rose by 1.9% in nominal terms over the month and by approximately 0.5% when adjusted for inflation. However, one month is not yet enough to speak of a sustained recovery in the real value of Turkish housing.
Ankara’s Prices Are Rising Faster Than Istanbul’s and Antalya’s
Among the 30 provinces with the highest number of transactions, the most notable growth was recorded in Ordu—32.4% over the year. This is the only province among those analyzed where growth was positive even after adjusting for inflation—about 0.4%.
Ankara ranks second with a nominal increase of 28.7%, although in real terms, housing in the capital became approximately 2.5% cheaper. Next are Kocaeli—up 28.5%, Denizli—27.1%, and Elazığ—26.9%.
In Istanbul, a square meter of housing cost an average of 65,100 liras in July, and the average price of a property was about 7.16 million liras, or $149,500.
In Antalya, one of the main markets for foreign buyers, the average price per square meter reached 55,500 lira, and the average price per property was about 6.1 million lira, or $127,500. In Izmir, the average price was about 54,000 lira per square meter and 6.48 million lira per property.
Muğla remains Turkey’s most expensive province, home to resort centers such as Bodrum and Marmaris. Here, the average price per square meter reached 87,200 lira, and the average price per property was 11.34 million lira, or nearly $237,000. This is more than double the national average.
Housing sales have fallen sharply
The rise in prices is occurring against the backdrop of a significant decline in the number of transactions. According to the Turkish Statistical Institute (TÜİK), statistics on residential and commercial real estate sales for July were published on August 13, 2026. A total of 123,603 residential properties were sold nationwide during the month, which is approximately 17% less than a year earlier.
Istanbul remained the largest market with 22,600 transactions, followed by Ankara with 9,640, Izmir—6,550, and Antalya—6,300.
At the same time, the sales breakdown sends mixed signals. The number of mortgage transactions rose by 23.7%, while sales of new homes fell by 8.6% and those of existing homes dropped by as much as 20.8%. This may indicate a gradual return to the market of some buyers who are able to take advantage of bank financing.
Thus, the rise in the value of Turkish real estate in lira remains, to a large extent, a consequence of inflation. For investors, it is more important to pay attention not only to nominal growth of 20–30%, but also to real price trends, exchange rates, and rental yields. As of the end of July, the average property in Turkey is nominally significantly more expensive than a year ago; however, its real value continues to decline.
Open4Business recently conducted a separate analysis of the composition of foreign buyers of Turkish real estate. As of June 2026, Russian citizens ranked first with 381 purchases, while Ukrainians acquired 170 properties and tied for second place with Iranian citizens. In total, foreigners purchased 2,015 residential properties in June. From January through June, foreign demand totaled 9,083 properties, down 9.2% from the previous year.
Ukrainians remain one of the largest groups of homebuyers in Turkey, even over the long term. In 2025, Ukrainian citizens purchased 1,541 properties and ranked third among foreign buyers, trailing only Russians and Iranians. Thus, the decline in real prices for Turkish housing is of direct interest to Ukrainian private investors, who continue to maintain an active presence in this market.
The cost of construction and installation work on civil engineering projects in Ukraine in June 2026 rose by 24.3% compared to June of last year—the highest rate among the major construction segments. According to data from the State Statistics Service, nonresidential construction rose in price by 23.8% over the same period, while residential construction rose by 19.2%. On average across the construction industry, the increase was 23.1%.
Civil engineering also led the way in terms of monthly trends. In June, compared to May, prices in this sector rose by another 1.8%, compared to 1.3% in non-residential construction and 0.8% in residential construction.
In the second quarter of 2026, civil engineering and installation work cost 22.4% more than in April–June of the previous year. A similar increase—22.4%—was recorded in non-residential construction, while residential construction prices rose by 18.2%.
The quarterly trends are particularly telling. Compared to the first quarter, prices for engineering work rose by 12.4% in the second quarter, and for non-residential construction by 12%, while the residential sector saw an increase of only 0.4%.
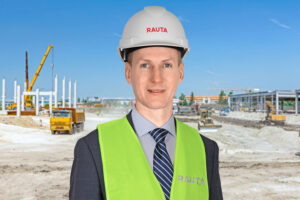
According to Andriy Ozeychuk, owner and director of the engineering and construction company Rauta, the shortage of skilled workers remains one of the key factors driving up construction costs.
“The market is currently short about 30% of construction specialists,” Ozeychuk noted, commenting on the situation in the industry in February 2026.
According to his data, the labor shortage has already led to a noticeable acceleration in wage growth. While wages in the construction sector grew by an average of approximately 15–20% annually between 2022 and 2024, the growth rate reached 25–30% in 2025. Wages rose particularly sharply for concrete workers—by 50%, surveyors—by 44%, and concrete pourers—by 38%.
Thus, the current rise in the cost of construction work is not driven solely by prices for building materials and equipment. The cost of construction work itself and labor is playing an increasingly important role.
Ozeychuk also drew attention to the long-term nature of the labor shortage. According to him, vocational schools are facing both a shortage of students enrolling in construction programs and a high dropout rate as early as the first years of study.
“In the long run, this could lead to an even greater labor shortage and slow down Ukraine’s recovery,” says the owner of Rauta.
According to the company’s estimates, the labor shortage is already forcing the construction industry to seek workers outside Ukraine, particularly in India, Nepal, Bangladesh, and Pakistan.
The rising cost of civil engineering is of particular importance to Ukraine due to the massive need to rebuild energy, transportation, utilities, and other critical infrastructure. According to Rauta’s estimates for 2025, the segment of critical infrastructure restoration and protection already accounted for about 20% of the Ukrainian construction market.
Therefore, further increases in the cost of civil engineering work could directly impact the cost estimates for restoration projects. If the cost of construction and installation work rises by 20–25%, projects whose budgets were established much earlier may require additional funding or a revision of technical solutions and implementation timelines.
At the same time, non-residential and infrastructure construction remain among the most active segments of the market. In 2025, the main targets for investment in commercial real estate were warehouse, industrial, and retail buildings, while the most attractive regions for new construction were the Kyiv, Lviv, and Ivano-Frankivsk regions, Ozeychuk noted.
In the first half of 2026, civil engineering construction costs rose by 16.1% year-over-year, non-residential construction by 16.5%, and residential construction by 13.7%.
“Rauta” operates in the fields of design, construction, and installation of buildings and is a member of the European Construction Industry Association. According to data from the Unified State Register, Andriy Ozeychuk owns 100% of the company’s authorized capital.
CONSTRUCTION, INFRASTRUCTURE, OZEYCHUK, PRICE, RAUTA, RESTORATION, STAFF



