
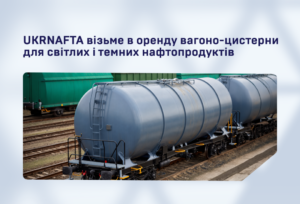
UKRNAFTA is seeking reliable logistics partners.
The company is announcing a commercial procurement for the long-term lease of rail tank cars.
We are accepting proposals for two categories:
• steam-jacketed tank cars for the transportation of dark petroleum products;
• non-steam-jacketed tank cars for the transportation of light and dark petroleum products.
The location for service provision is Ukraine.
We are accepting proposals from September 23 until 3:00 p.m. on October 14, 2026.
Let’s work together to support Ukraine’s energy resilience!
For more details, see this link.
JSC “Ukrnafta” is Ukraine’s largest oil producer and operates the country’s largest national network of gas stations—UKRNAFTA. In 2024, the company began managing Glusco’s assets. In 2025, it finalized a deal with Shell Overseas Investments BV to acquire the Shell network in Ukraine. In total, it operates nearly 700 gas stations.
The company is implementing a comprehensive program to resume operations and modernize the format of the gas stations in its network. Since February 2023, it has been issuing its own fuel vouchers and “NAFTACard” cards, which are sold to legal entities and individuals through Ukrnafta-Postach LLC.
The largest shareholder of Ukrnafta is NJSC Naftogaz of Ukraine, with a stake of 50% plus one share.
In November 2022, the Supreme Commander-in-Chief of the Armed Forces of Ukraine decided to transfer to the state the portion of the company’s corporate rights previously held by private owners; the company is now managed by the Ministry of Defense.
LOGISTICS, PETROLEUM PRODUCTS, PROCUREMENT, TANKER, UKRNAFTA
According to the Serbian business publication Parametar, the Serbian oil and gas company NIS has submitted a new request to the Office of Foreign Assets Control (OFAC) of the U.S. Department of the Treasury for a special license that would allow the company to continue its operations beyond September 30. The current license expires on that very day.
NIS emphasizes that the company’s uninterrupted operations, the stable operation of the oil refinery in Pančevo, and the regular supply of petroleum products to the Serbian market are crucial for the country’s energy stability.
U.S. sanctions against NIS were imposed in early 2025 due to Russian ownership stakes in the company. Since then, OFAC has repeatedly issued temporary licenses allowing NIS to continue its operations.
At the same time, the process of restructuring NIS’s ownership continues. Hungary’s MOL is in negotiations with Gazprom Neft regarding the acquisition of a 56.15% stake in NIS. In June, the Serbian government and MOL already signed a shareholders’ agreement outlining the future governance model for the company should the deal be finalized.
To finalize the deal, not only is a purchase and sale agreement between MOL and Gazprom Neft required, but also additional approvals from regulatory authorities, primarily OFAC. Serbia has also agreed to the possibility of increasing its stake in NIS by another 5 percentage points.
Serbian authorities had previously reported that a company from the UAE might also participate in the future structure of the deal. This refers to the possible entry of a Middle Eastern investor into NIS’s capital following the completion of the deal with MOL.
As of June 30, 2026, Gazprom Neft owned 44.85% of NIS, the Republic of Serbia owned 29.87%, and another 11.3% was held by JSC Intelligence. The remaining shares are held by minority investors.
NIS remains Serbia’s key oil company. It owns an oil refinery in Pančevo, and the company’s network of gas stations also operates in neighboring countries in the region.
Currently, the main question for the Serbian energy market is whether OFAC will extend the license before the current permit expires on September 30, while negotiations regarding the change in NIS ownership are still ongoing.
The European Union is not yet ready to review the volume of quotas for Ukrainian agricultural products, but Ukraine will continue the dialogue on expanding them, particularly with regard to bioethanol, said Minister of Agrarian Policy and Food Taras Vysotsky at a briefing on Thursday.
“The current socio-political situation in the EU does not allow for a review of agricultural product quotas in any category. We will nevertheless continue the dialogue and make our case for what is important,” he said.
According to the minister, one of the areas where Ukraine considers it appropriate to review the quota is bioethanol. Among his arguments, he cited the reduction in EU corn production for bioethanol to about 15 million metric tons and the European Union’s continued imports of corn.
“Essentially, increasing the quota is really just a way to allow the export of bioethanol, which will then be re-exported to Ukraine,” Vysotsky noted.
The head of the Ministry of Agrarian Policy added that Ukraine imports gasoline from the EU that contains about 7% bioethanol.
“We are requesting a quota to export approximately the same amount of bioethanol that Ukraine already imports as part of fuel—in gasoline from the European Union—plus 60,000 metric tons,” the minister explained.
Toronto and Vancouver saw the most significant declines in housing prices among the 23 largest global markets analyzed by UBS in 2026.
Over the past four quarters, real housing prices in both Canadian cities have fallen by approximately 10%, according to the UBS Global Real Estate Bubble Index 2026.
The correction was particularly severe in Toronto. From 2014 to 2022, real prices there doubled due to rapid population growth, investment demand, and cheap financing.
After 2022, the situation changed. Due to rising interest rates, restrictions on foreign buyers, and an increase in supply, real prices are now nearly 30% below their peak, according to UBS.
In Vancouver, real prices have fallen by nearly 10% since mid-2025 and are about 20% below their 2022 peak. Home sales have dropped to their lowest level in about 25 years, while the number of properties on the market remains significantly above the long-term average.
As a result, UBS now classifies both cities as only moderate risk: Toronto’s index stands at 0.63, and Vancouver’s at 0.62. Just a few years ago, the Canadian markets were considered among the most overheated in the world.
A correction is also underway in Germany, though less sharply. Real prices in Frankfurt and Munich have fallen by nearly 4% over the past year. In Frankfurt, housing prices—adjusted for inflation—are already about 25% below their 2021 peak.
At the same time, UBS notes that a structural housing shortage persists in both Germany and many other major cities, which limits the potential for further price declines.
Kyiv was not included in this study.
The Turkish company ASTOR Enerji A.Ş., which specializes in electrical equipment manufacturing, plans to implement a project worth up to $200 million in the Kyiv region, which will involve the production of energy storage systems and transformers, according to the Kyiv Regional Development Agency.
“The company is considering investing up to $200 million in the creation of a modern manufacturing complex in the Kyiv region. The project involves the production of energy storage systems, battery solutions, electrical equipment, and transformers,” the agency stated in a post on LinkedIn on Tuesday.
It notes that a corresponding memorandum with ASTOR Enerji A.Ş. was signed by the Kyiv Regional Military Administration with the agency’s support during the Carpathian Eight Summit.
The agency notes that for the Kyiv region, the implementation of such a project will mean the creation of new production capacity and jobs, further industrial development, the introduction of advanced technologies, and enhanced energy resilience.
It explained that it will continue to support the project through the next stages: from selecting potential investment sites and engaging with local communities to coordinating further steps with the investor.
Zurich and Tokyo were the only two of the world’s 23 largest cities that UBS classified in 2026 as having a high risk of a housing real estate bubble.
According to the UBS Global Real Estate Bubble Index 2026, published on September 22, Zurich’s index stood at 1.69 and Tokyo’s at 1.54. UBS considers an index above 1.5 to indicate high risk.
The “elevated risk” category included Miami with an index of 1.41, Dubai at 1.16, Seoul at 1.13, Geneva at 1.12, and Lisbon at 1.04.
Moderate risk was recorded in Amsterdam at 0.95, Madrid at 0.86, Los Angeles at 0.69, Sydney (0.68), Frankfurt (0.64), Toronto (0.63), Vancouver (0.62), Munich and Hong Kong (both 0.61), Singapore (0.54), and Milan (0.50).
UBS classified Paris (0.33), London (0.32), New York (0.28), San Francisco (-0.02), and São Paulo (-0.24) as low-risk markets.
In Zurich, real housing prices have risen by nearly 140% over the past 20 years, while rental rates have increased by approximately 40% and household incomes by 30%. The ratio of purchase price to rental cost has reached 46 years—the highest figure among all cities studied by UBS.
In Tokyo, inflation-adjusted housing prices are now about 50% higher than they were seven years ago. Over the past year, they have risen by another 6% or so.
UBS notes that, on average, real housing prices in all surveyed cities rose by only 0.5% over the past year; however, a significant gap has emerged between individual markets.
The bank emphasizes that a high index reading does not predict an inevitable crash. A correction could occur due to changes in interest rates, investor sentiment, or a significant increase in housing supply.



